
PJM may be ‘too big to function’: FERC Chairman Swett
Source: Utility Dive
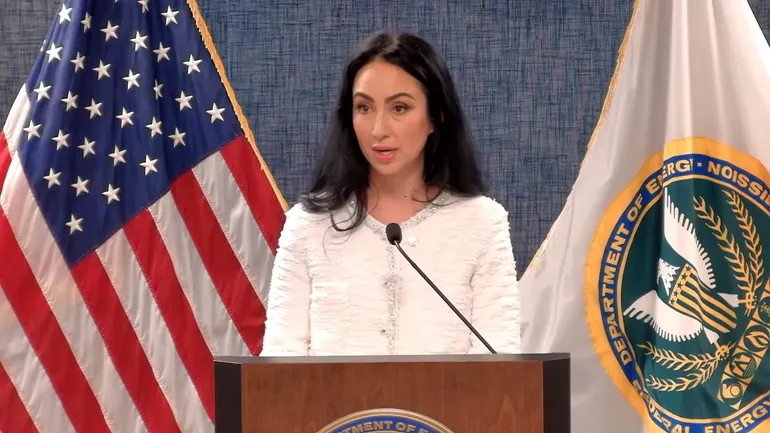
FERC Chair Laura Swett said PJM Interconnection may be "too big to function" and criticized its governance as "unacceptable," as the grid operator faces a legitimacy crisis amid surging demand from data centers. PJM recently failed to procure enough capacity in its December auction to meet reserve margin targets, while 8.2 GW was being built and 3.2 GW was partly in service as of January. FERC will hold a July 23 technical conference to examine governance flaws and potential fixes.
Analysis
The real market signal is not the governance rhetoric; it is that PJM is likely entering a regime where administrative friction becomes a pricing input. When a large load-growth region cannot clear enough capacity and cannot quickly approve new supply, the marginal winner is not the existing utility complex but the developers that can self-supply, finance, and interconnect fastest. That favors merchant generation, gas turbines, transmission-enabling equipment, and firms with balance sheets or contracts that let them bypass the slowest parts of the queue.
The second-order effect is that this shifts power from centralized market design toward bilateral contracting and behind-the-meter solutions. Data-center customers will increasingly seek long-dated PPAs, on-site generation, and “always-on” capacity hedges, which should widen spreads for assets that can deliver firm power in 12-24 months versus projects that depend on the normal interconnection path. The longer this governance dispute lasts, the more it validates higher forward capacity prices and the more it pressures incumbent load-serving entities that are exposed to wholesale volatility without equivalent control over supply additions.
The near-term catalyst set is political, not operational: the July conference is a path to procedural change, but meaningful supply relief is likely months to years away. That asymmetry creates a tactical setup where the market can rerate reliability-sensitive names before fundamentals fully improve. The main reversal risk is if FERC uses the process to force faster approvals or carve-outs for large-load interconnection, which would compress scarcity premiums and cool the strongest trades.
Contrarian take: the market may be underestimating how much of the current tightness is self-inflicted by process bottlenecks rather than true physical scarcity. If governance gets fixed even incrementally, the most crowded scarcity trades could mean-revert faster than consensus expects. But absent a concrete reform package, any dip in PJM-exposed power names is more likely a buying opportunity than a structural top.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Key Decisions for Investors
- Long NRG or CEG on a 3-6 month horizon; thesis is that higher forward capacity pricing and load-growth urgency monetize faster than consensus models. Use a 10-15% stop if FERC signals aggressive reform that accelerates new supply approvals.
- Long grid and equipment beneficiaries such as ETN or PWR for 6-12 months; order backlogs should improve as utilities and data-center developers prioritize transmission, substations, and interconnect work. Favor pullbacks over chasing strength.
- Pair trade: long merchant/flexible generation vs short regulated utility beta (e.g., long CEG/NRG vs short a regional utility ETF or low-growth utility names) to express widening dispersion between firms that can capture scarcity and those capped by regulation.
- Buy upside exposure via call spreads on a PJM-exposed power name for the July-to-year-end window; the asymmetric catalyst is a governance reset or further auction stress, both of which can reprice the forward curve quickly.
- Avoid shorting scarcity beneficiaries until after the technical conference; the risk/reward is poor because policy headlines can keep extending the repricing for several quarters even if physical additions are only modestly improved.
More News
- A blue wave sends futures into the green
- Elon Musk’s record election bet backfired. The backlash may reach beyond one billionaire
- Americans have said 'NO TO WAR,' Iran speaker says as Democrats take Congress
- Binance attackers used fake job interviews to pull off $6.3 billion crypto heist
- The Strait of Hormuz closure has cost Europe an extra $142 billion for the same energy it was already buying
- Democrats’ Midterm Wins Threaten to Slow the AI Data Center Boom