
Hemlo Mining Corp. Intersects 89.9 g/t Au over 3.0 Metres at South-Rim, Further Defining High-Grade Mineralization Adjacent to C-Zone
Source: PR Newswire
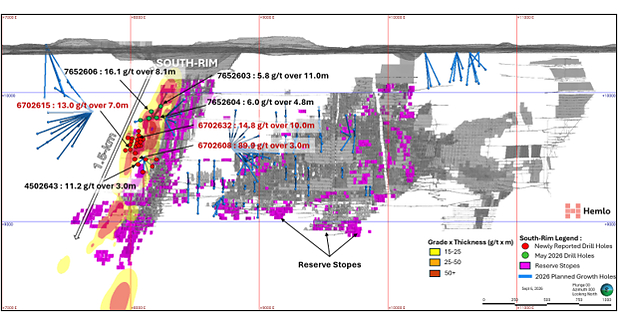
Hemlo Mining reported high-grade South-Rim drill intercepts of 89.89 g/t gold over 3.0m, 14.81 g/t over 10.0m and 12.97 g/t over 7.0m, supporting a potentially low-capital resource expansion adjacent to active C-Zone infrastructure. The company has defined roughly 500m of high-grade mineralization across an interpreted 1.5km zone, with about 1km still to be tested; the 2026 results were excluded from the June resource estimate. Hemlo expanded the program to include conversion drilling, has completed approximately 75,000m of its planned 130,000m campaign, and targets a comprehensive resource and reserve update in H2 2027.
Analysis
The relevant valuation mechanism is not headline grade but whether infill drilling converts a coherent portion into mineable Indicated tonnes with recoverable widths, dilution control and no incremental development bottleneck. If that occurs, HMMC can add higher-margin feed close to existing workings, improving fixed-cost absorption and potentially deferring larger sustaining or replacement-development requirements. The market is likely to capitalize this only modestly until a reserve-backed mine-plan impact is quantified; isolated bonanza intercepts carry limited NAV value without continuity and reconciliation data.
Near-term price sensitivity is to the next assay batches and evidence that tighter-spaced drilling reduces grade variability rather than exposes nugget effects. Over the next 1-3 months, a series of consistent intercepts across the untested corridor could support a speculative rerating, but the durable catalyst is the 2027 resource/reserve update and accompanying production, cost and capital guidance. The key falsifiers are weaker deeper extensions, an inability to convert material to Indicated classification, rising underground development costs, or funding terms that transfer the exploration upside to lenders/stream holders.
A second-order implication is that successful low-capital ounces would make HMMC a more credible consolidation target or joint-venture candidate for Ontario-focused operators, although NEM and AEM should not trade materially on this release given their diversified asset bases. Conversely, the company-specific upside may be diluted if expanded drilling materially raises cash burn before reserve conversion, particularly in a weaker gold-price environment. Consensus may overvalue the proximity argument: nearby mineralization is economically valuable only if ground conditions, access geometry, metallurgy and scheduling allow it to displace lower-grade planned feed rather than simply extend the tail of mine life.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Do not chase an opening spike in HMMC; establish only a small tactical long after confirming liquidity and a close above the post-release high, with a 1-3 month horizon into follow-on assays. Size as venture-risk exposure: failure of continuity/infill results can plausibly erase the assay-driven premium.
- Add to HMMC only upon evidence of repeatable conversion drilling and explicit disclosure of expected resource-to-reserve timing, development metres and incremental capital; these data are required to translate grade into NAV rather than exploration optionality.
- Use a long HMMC / short GDXJ or comparable junior-gold beta basket only if HMMC's valuation remains below a reserve-backed peer NAV multiple after multiple consistent releases. This isolates execution upside from gold-price beta; exit if gold weakens materially or drilling demonstrates discontinuity.
- Maintain no directional positions in NEM, AEM or GLEN on this development. Monitor AEM and NEM only as potential strategic-buyer comparables if HMMC demonstrates reserve conversion and balance-sheet funding capacity; that is a 6-18 month scenario, not a current catalyst.
More News
- Newmont Q3 Earnings: Investors Are Walking On Thin Ice
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI for Sell-Side Models, Estimates, and Internal Data
- How to Write an Investment Memo with AI: A Decision-Record Template