
HiTHIUM dépasse les 200 GWh de livraisons, faisant progresser le stockage d'énergie de longue durée à l'échelle mondiale grâce à une intégration complète de la chaîne.
Source: PR Newswire
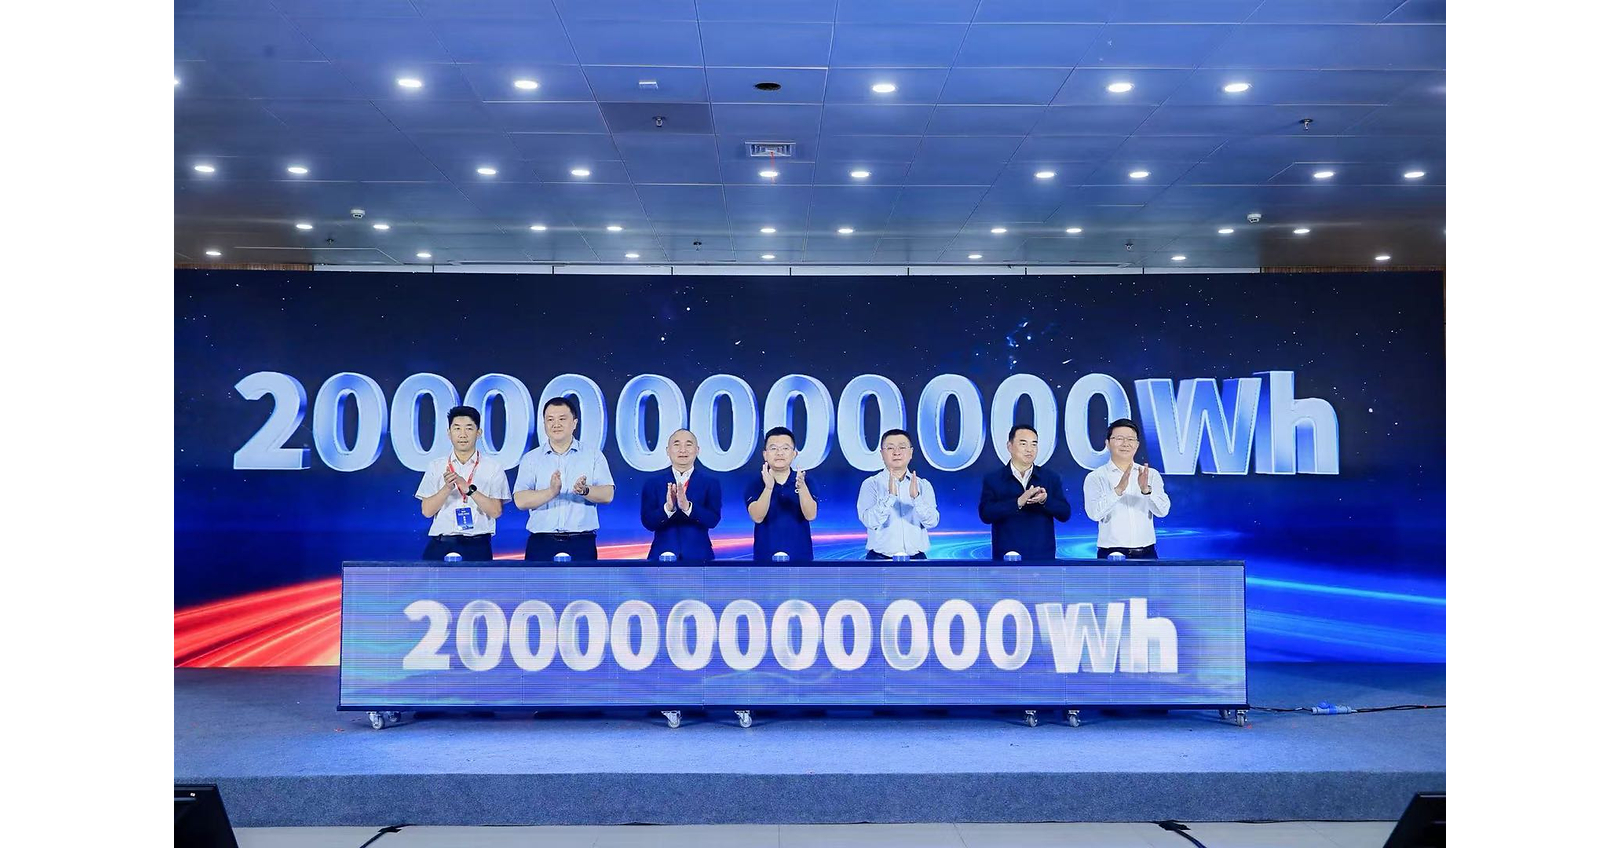
HiTHIUM said cumulative energy-storage deliveries reached 200 GWh on October 15, 2026, up from more than 100 GWh in August 2025. The company said it moved from fifth globally in 2023 to second in 2025 and the first half of 2026, and plans to scale LDES technology, manufacturing and global delivery capacity toward its next 100 GWh. The milestone indicates rapid reported growth, though the article provides no financial results or market reaction.
Analysis
The investable signal is not the cumulative-volume milestone itself; it is whether HiTHIUM can convert scale into lower delivered system costs without intensifying price competition. The release provides no independently verified shipment definition, revenue conversion, utilization, margins, or project-level economics, and its claimed rank should be treated as company-reported. More capacity and integrated delivery could pressure pricing across cells and systems, benefiting developers and utilities only if savings reach project economics; otherwise the gain accrues to customers while manufacturers absorb margin dilution. Relevant competitive read-throughs include CATL, BYD, EVE Energy, Tesla, Fluence, and Sungrow, but the article does not establish direct share loss for any of them.
Near term, this is weak evidence for a trade: HiTHIUM is not mapped to a listed security here, and a PR milestone is not an earnings revision. Over 1–3 months, the key catalysts are independent shipment data, peer commentary on storage pricing, and order/backlog conversion. Over 6–18 months, LDES claims matter only if deployed systems demonstrate reliability, competitive cost per delivered MWh, and repeat orders; scaling factories ahead of demand or localization requirements could instead raise execution risk. Contrarian view: investors may overread cumulative GWh as proof of profitable leadership. The thesis turns constructive only with corroborated volumes and stable economics; it weakens if peers flag price erosion, project delays, or falling utilization.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- No immediate position based on this release alone. Put HiTHIUM’s claimed shipment scale on the watchlist, not in a valuation model, until the GWh scope, shipment verification, revenue recognition, and profitability are clarified.
- Over the next 1–3 months, track CATL, BYD, EVE Energy, Tesla, Fluence, and Sungrow disclosures for storage pricing, order conversion, and margin commentary. Treat evidence of broad price cuts without corresponding demand or utilization gains as a negative for cell and system suppliers.
- Consider a relative-value trade only if corroborated data show storage demand and deployments strengthening while cell pricing compresses: favor diversified project integrators over undifferentiated cell exposure. Do not initiate until peer disclosures establish the pricing and margin direction.
- Falsify the bullish scale thesis if independent shipment evidence diverges materially from the company claim, peers report worsening storage margins or utilization, or LDES deployments fail to produce repeat orders and reliable project economics.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- All the news about the iPhone Duo
- The Tesla Roadster should go into production in 2028, but don't get your hopes up
- Ukraine advances in occupied Donetsk as Trump hands Putin diesel deal
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Research Systems for Hedge Funds: A Pilot Design
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations