
Centellian24 Flexing Muscle in US Market, Surpassing Expectations & Growing Retail Footprint
Source: PR Newswire
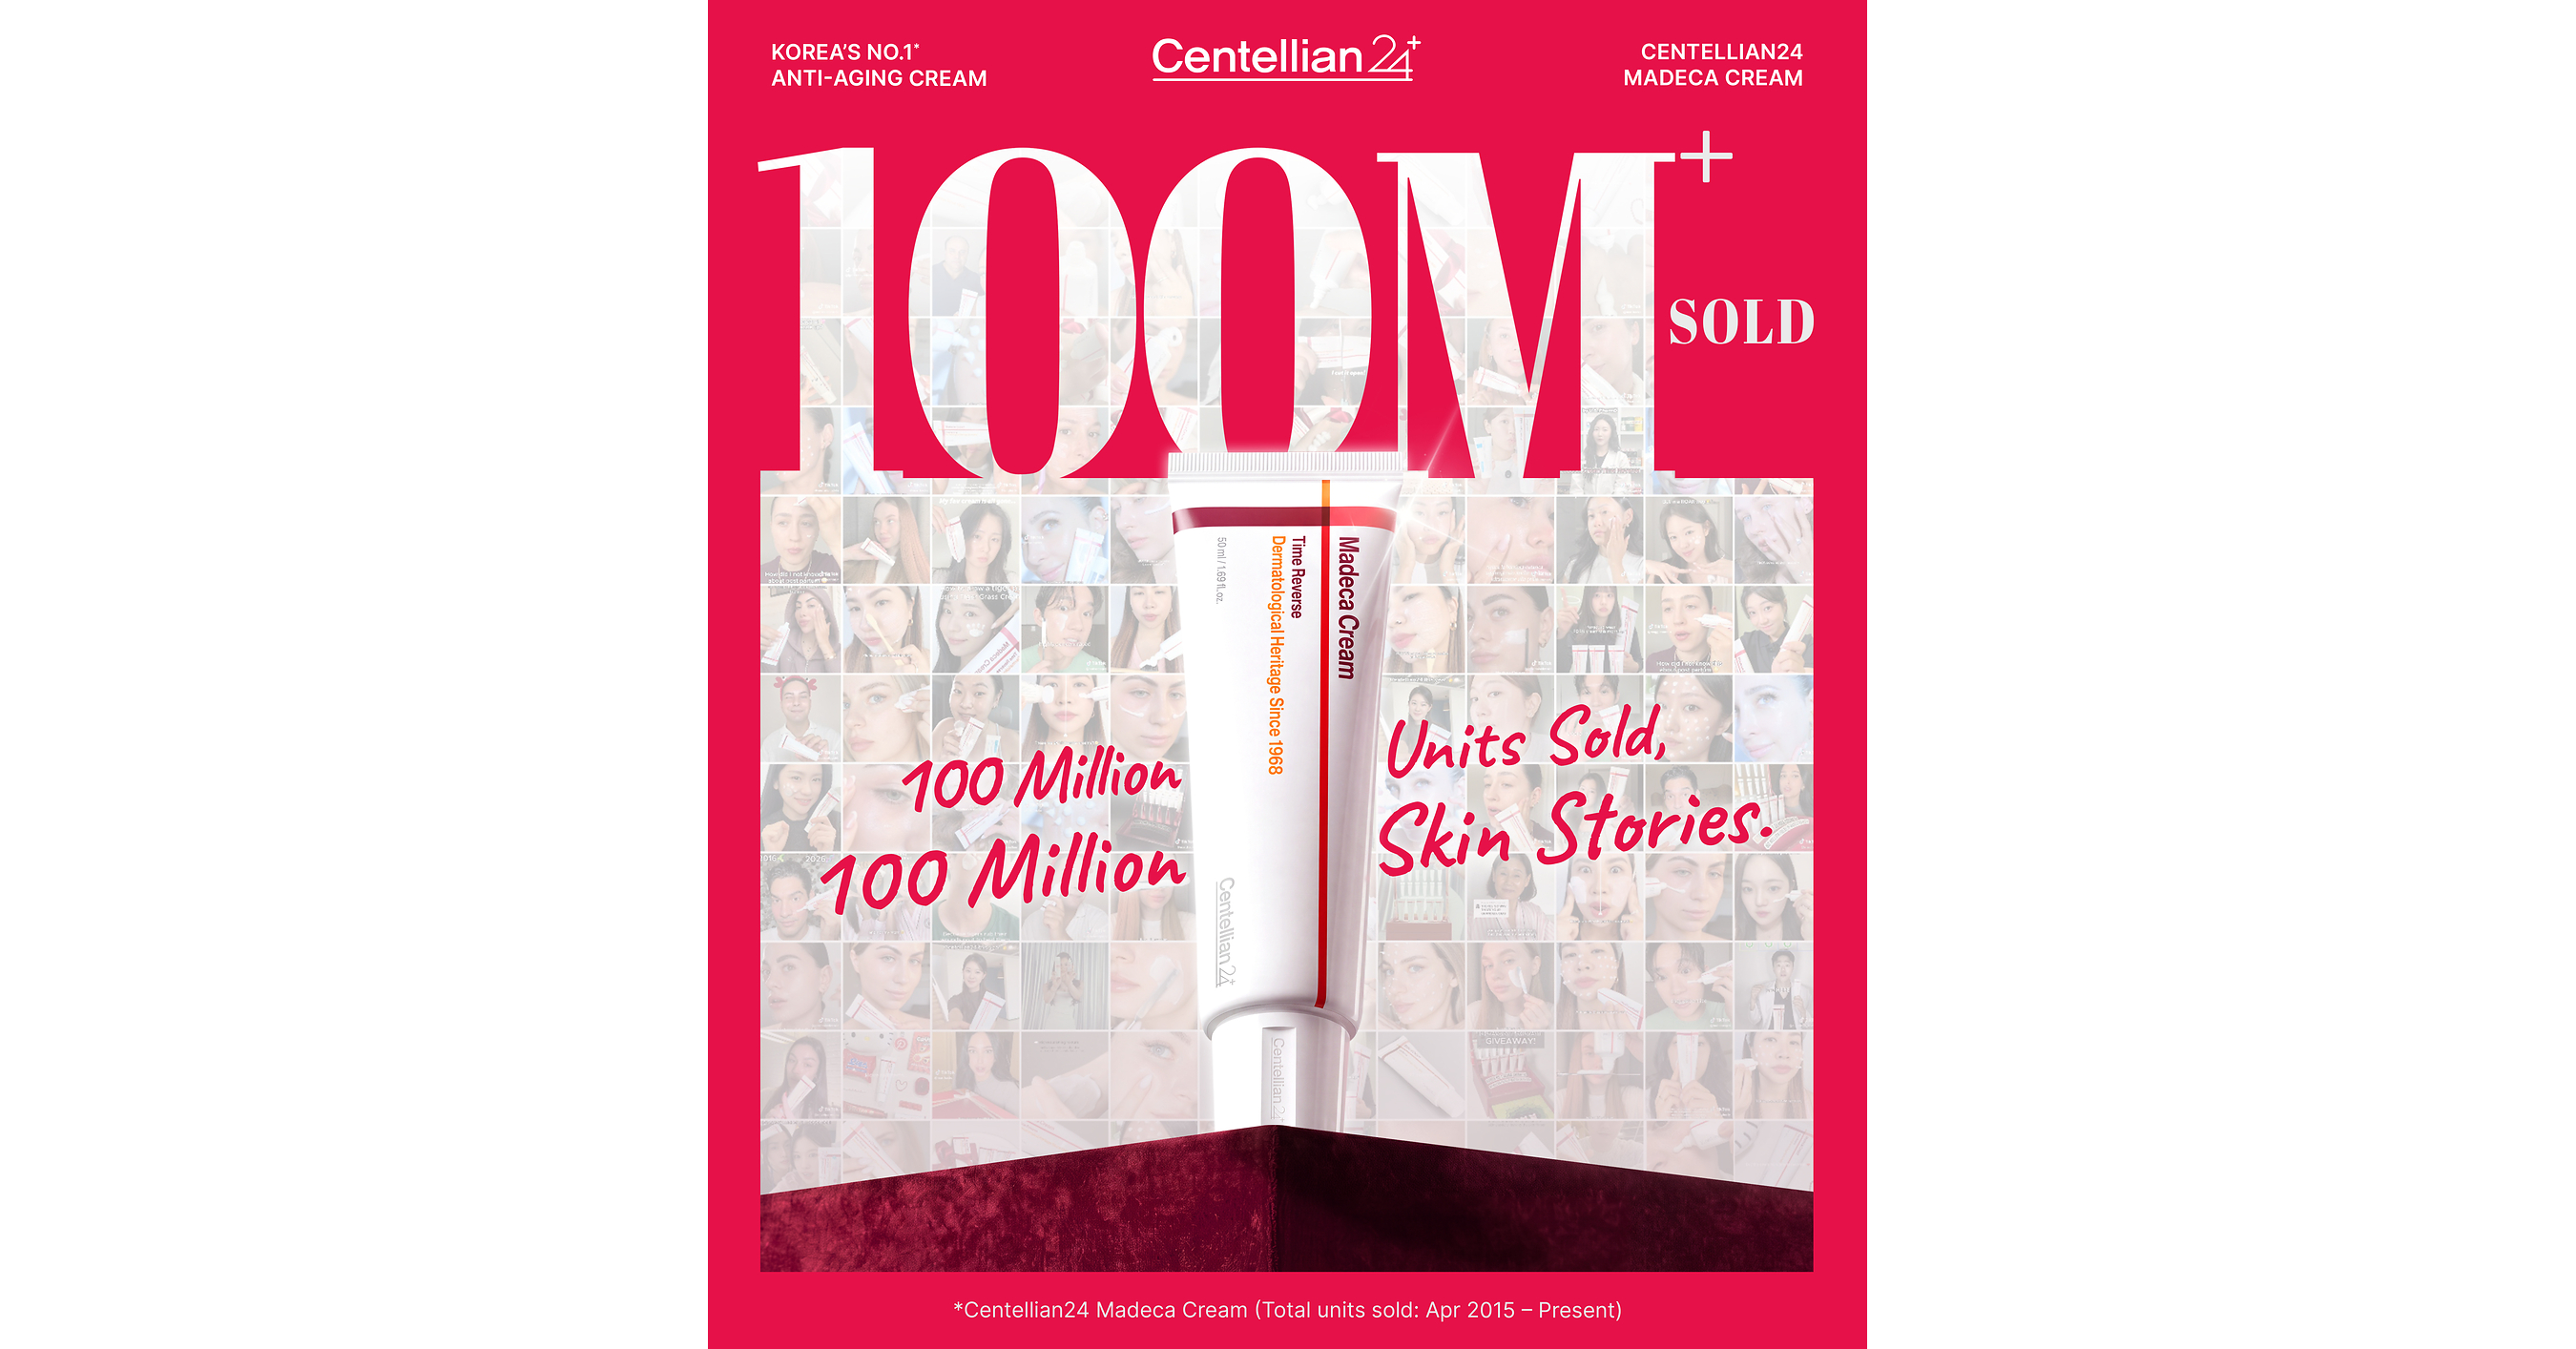
Centellian24’s hero product, Madeca Cream Time Reverse, has surpassed 100 million units sold worldwide, with the brand scaling U.S. distribution since late 2024. In 2026 it expanded offline footprint across Ulta (1,500 stores; launch May, plus additional SKUs in 760 stores in August), Nordstrom (~89 stores; June), and Costco (~200 locations plus Costco.com; July). The article frames the momentum as an early-stage but solid brand build, suggesting continued long-term growth momentum rather than a near-term earnings catalyst.
Analysis
This is more a distribution signal than a true fundamentals update. The near-term winners are the retailers that can turn skin-care trial into higher-frequency basket behavior: ULTA has the best shot because specialty beauty converts discovery into repeat purchasing, while COST gets lower-margin traffic and AMZN gets search-driven access but little pricing power. The second-order effect is channel mix: if K-beauty keeps gaining share, incumbent prestige skincare names may need heavier promo support to defend shelf space, which would pressure category margins more than revenue.
The main risk is that global unit claims do not equal durable U.S. sell-through. The next 1-3 months matter most: watch repeat orders, SKU expansion, and whether these placements stay in front-of-store or migrate to slower-moving aisles. If sell-through decelerates after the initial novelty period, this becomes a one-time trial event rather than a structural share shift; if replenishment holds, the upside lasts 6-18 months through mix improvement and incremental beauty traffic.
Contrarian view: the market may be overpaying for the idea of "K-beauty momentum" when the real evidence needed is reorder velocity, not brand awareness. That makes this a better retailer-share story than a product-company story. The clearest falsifier is weak ULTA beauty comps or evidence of discounting/markdowns in the next two earnings prints; without that, the upside is mostly limited to modest basket lift rather than a material earnings revision.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Long ULTA / short TGT for 4-8 weeks: express the view that specialty beauty will capture the incremental share of discovery and repeat skincare spend. Risk/reward is attractive only if ULTA beauty comps and basket data hold; cover if ULTA guidance does not improve or if TGT shows unexpected beauty stabilization.
- Add a small tactical long COST on weakness, 1-3 month horizon: club-channel trial can add traffic and basket mix, but the upside is modest and already partly reflected in quality premium. Use this as a defensive consumer-staples exposure, not a high-conviction alpha idea.
- Monitor AMZN rather than trade it immediately: buy-side signal would be improving search rank, review velocity, and subscribe-and-save adoption for the brand. If those metrics accelerate, AMZN benefits from a low-cost customer acquisition loop; absent that, the impact is too diluted to matter.
- Set a watch item on ULTA into the next two reporting cycles: if skincare comps, transaction growth, or repeat purchase indicators do not inflect, fade the bullish narrative. That would imply the brand is a shelf novelty, not a durable category driver.
More News
- OpenAI projected to bring in $20bn less in revenue than expected
- New data shows Starbucks turnaround is working, but Chipotle takeover report slams shares
- Trump admin suspends green cards to Microsoft as Vance accuses the company of replacing laid-off workers with ‘foreign indentured servants’
- This cybersecurity stock is already growing revenue at a 20% clip. And now here comes the AI boost
- Costco's sales resilience is giving Cramer a reason to feel better about the stock
- Amazon overhauls aging devices lineup with higher priced Alexa tablet, dumping the budget Fire
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect
- Fintool Alternatives After the Microsoft Acquisition