
Branch Brings Flex EWA to Banks and Credit Unions
Source: PR Newswire
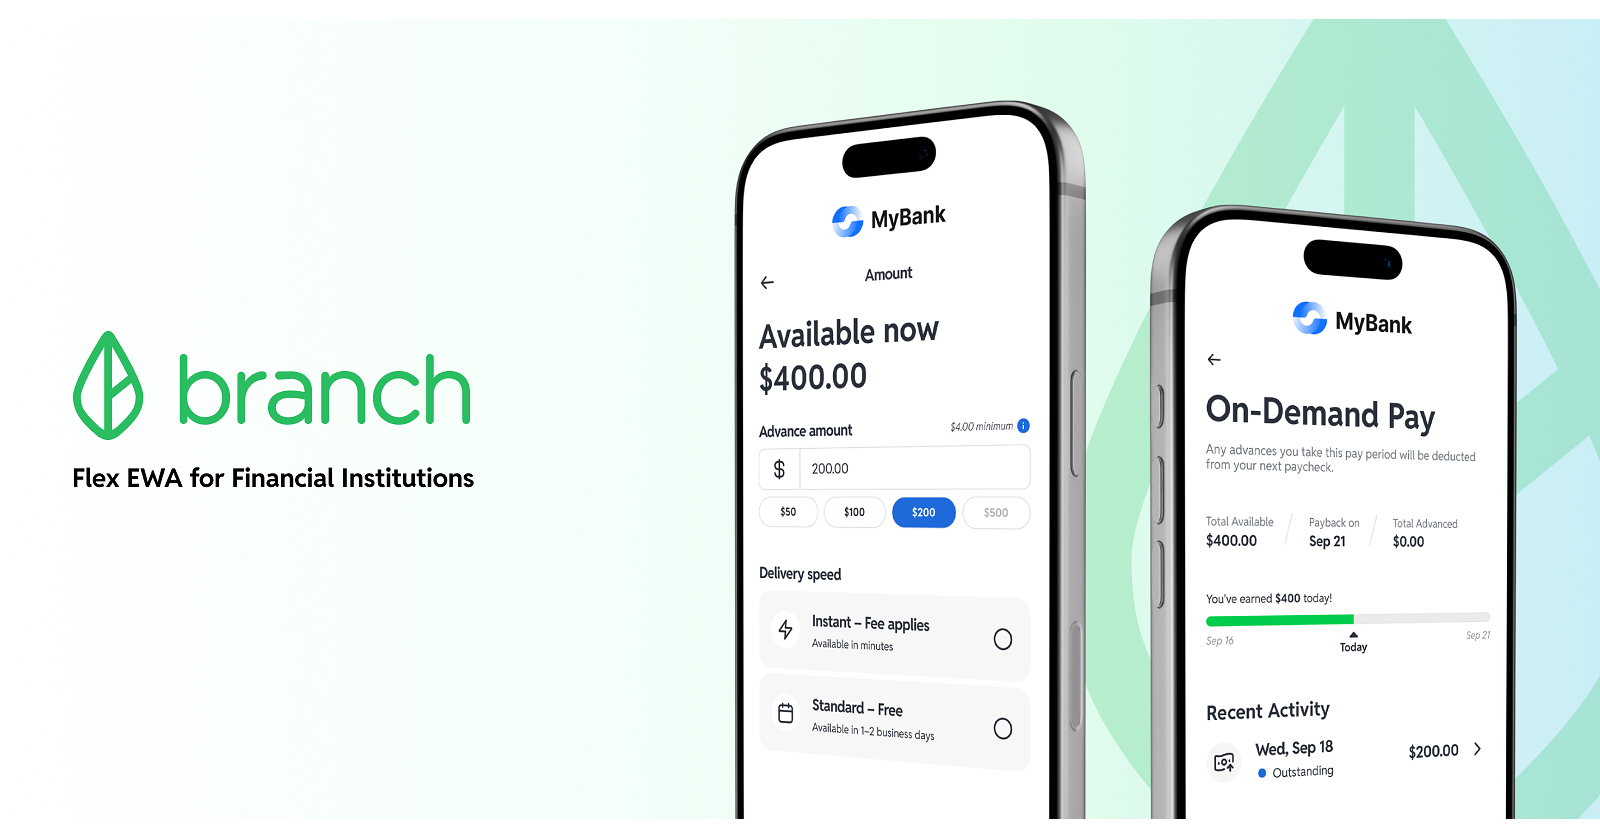
Branch launched its Flex earned wage access model for banks and credit unions, allowing institutions to embed branded EWA in existing apps without funding advances or taking balance-sheet risk; Branch also handles compliance and integrations. The company says institutions can launch through a 60-day sprint, and customers can choose a fee-based instant transfer or free standard delivery. The product is available now; the announcement did not provide adoption, revenue, or financial-impact figures.
Analysis
The strategic value is distribution, not a new credit product: Branch supplies funding and operating infrastructure while the institution owns the customer interface. If adoption is meaningful, banks could defend primary-account status and card activity against digital-first competitors without building EWA in-house. But Branch’s retention claims are company-supplied; the economic case depends on incremental funded accounts and activity, net of integration costs, instant-transfer fees, and any displacement of existing overdraft or liquidity products. Wider bank access may also commoditize EWA and shift bargaining power toward institutions, pressuring provider economics as rivals compete for white-label distribution.
The risk is not eliminated, only moved outside the institution: Branch funds advances, while Lead Bank provides banking services; provider funding capacity, repayment performance, compliance and partner concentration therefore remain diligence items. Consumer-protection or wage-access rule changes could raise costs or constrain fees. Near term, this is a product announcement with no named launch partners or disclosed volumes, so it does not establish material revenue or earnings impact. Over 1–3 months, validate signed institutions and actual launch timing; over 6–18 months, track adoption, repeat usage, repayment outcomes and whether deposits/card activity are genuinely incremental. The thesis weakens if launches slip beyond the stated implementation window, usage is low, or institutions report no measurable deposit retention.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate public-equity trade: Branch has no supplied ticker, and no partner, pricing, volume or financial contribution is disclosed. Do not treat the announcement as an earnings catalyst for banks broadly.
- Set an alert for named bank or credit-union launches and subsequent disclosures on active users, advance frequency, fee revenue and deposit retention. Upgrade the theme only if usage and incremental account activity are evidenced.
- For diligence, monitor Branch’s funding and repayment performance, Lead Bank’s program role, partner concentration, and regulatory developments affecting EWA fees or classification. Deterioration here could impair the service even without direct bank balance-sheet exposure.
- Contrarian watch: bank-branded EWA may protect deposits, but could primarily shift customer activity from one liquidity channel to another rather than create new relationships. If bank uptake is rapid but provider economics or customer outcomes weaken, the likely beneficiaries may be institutions gaining bargaining leverage—not EWA platforms.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Bank of America Has 'Accountability' in Face of Fines, Says Moynihan
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- UBS considers leaving Switzerland over capital rule plans, WSJ reports
- Banks, CoreWeave, Nvidia, migration: Australia Briefing