
China Xplained | Der China-Druck oder die China-Chance?
Source: PR Newswire
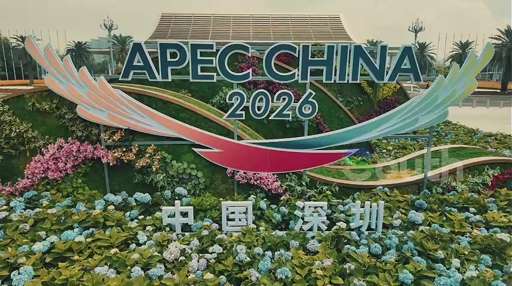
A China-focused PR news report frames China’s manufacturing expansion as a question of whether it displaces other economies or creates supply-chain and investment opportunities. More than 400 Asia-Pacific and international representatives attended the Asia-Pacific Media Forum in Shenzhen, opened September 5, ahead of China hosting the APEC summit in November 2026. The article provides no company-specific financial results, policy changes, or market-moving economic data.
Analysis
This is promotional, non-price-sensitive content rather than evidence of a policy or demand inflection; no immediate directional trade is justified. The investable issue is whether China’s manufacturing scale continues to compress global goods prices while shifting value capture toward Chinese component ecosystems. That would pressure low-complexity exporters in ASEAN and Latin America, but can lower input costs for downstream global assemblers and retailers over the next 6-18 months.
The more actionable second-order effect is competitive bifurcation: countries and companies integrated into Chinese intermediate-goods supply chains can gain export capacity, while those competing directly in finished goods face margin and utilization pressure. Watch Chinese export-price indices, ASEAN PMI new-export orders, and freight rates over the next 1-3 months; a renewed export-price decline alongside weak regional orders would support a disinflationary-goods thesis rather than a broad emerging-market growth thesis.
Consensus may overstate simple "China versus rest of world" displacement. Supply-chain diversification is increasingly additive at the component level: Vietnam, Mexico and India can expand final assembly even as China retains higher-value tooling, batteries, power electronics and industrial inputs. The thesis fails if tariff escalation forces rapid localization of these intermediate inputs, or if China’s domestic demand weakness drives another round of aggressive capacity exports that overwhelms partner-country absorption.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No immediate position: treat this as a policy/supply-chain watch item, not a catalyst. Require evidence from China export prices, regional PMIs and corporate guidance before adding risk.
- Over the next 1-3 months, monitor a relative-value basket of long Mexican industrial/nearshoring exposure (GMEXICOB, VESTA) versus short broad China-export-sensitive Asian manufacturing exposure only if ASEAN export-order data deteriorate materially; use a 5-7% relative stop because tariff headlines can reverse the spread quickly.
- For 6-18 months, maintain a watch list for long global downstream beneficiaries of cheaper Chinese inputs, including WMT and home-improvement/import-heavy retailers, versus short higher-cost discretionary goods producers; initiate only after gross-margin guidance confirms input-cost pass-through.
- Set a trade-policy alert around APEC-related announcements and new US/EU tariff or local-content measures. A credible expansion of restrictions into batteries, power electronics or industrial machinery would favor domestic-capex proxies such as XLI over China-linked global industrial supply chains.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- France is flashing euro crisis signals. This time, the fault lines are different
- EU entering winter with lowest gas reserves on record, IEA boss warns
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- ‘They are trying to intimidate us’: Indonesia’s Prabowo remains defiant in the face of an MSCI double downgrade
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.