
One Provident Place Posts Strong Leasing Momentum Following Recent Acquisition
Source: PR Newswire
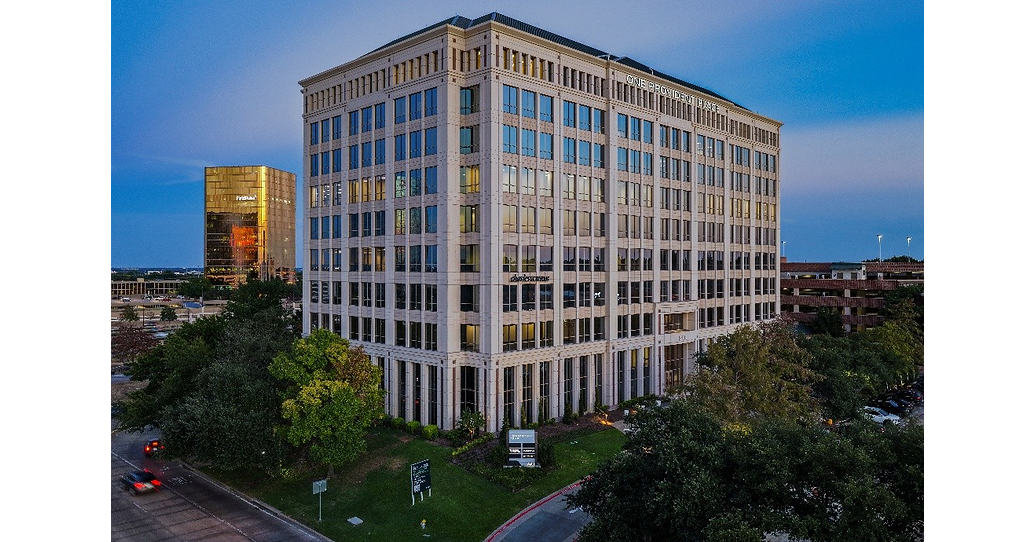
Provident’s newly rebranded One Provident Place in Dallas has secured 102,000 square feet of commitments, with nearly half of its 257,496-square-foot office building leased or under active negotiation. A private technology company signed a 56,000-square-foot, nine-year lease—the property’s largest since Provident acquired it—while Charles Schwab renewed its tenancy. Premium renovations and new tenant amenities are supporting leasing momentum ahead of Provident’s planned early-2027 relocation to the building.
Analysis
This is not a SCHW earnings catalyst: a single-office renewal is immaterial to its expense base and does not alter the brokerage, bank-deposit, or net-interest-income debate that drives the stock. The relevant read-through is narrower: tenant demand appears concentrated in amenitized, transit-accessible submarkets, reinforcing a bifurcated Dallas office market in which renovated assets can preserve rent and occupancy while commodity space faces further effective-rent pressure.
For office owners, the economic question is whether leasing velocity converts into rents sufficient to earn back tenant-improvement, free-rent, and amenity capital. A long-duration lease can improve lender perception and refinancing capacity, but only after disclosed cash rent, concessions, and build-out costs establish positive NOI accretion; the release provides none of those metrics. The near-term effect is therefore primarily a local leasing-data point, not a valuation reset for publicly traded real estate.
The contrarian implication is that headline occupancy momentum can mask a widening capital-expenditure gap. Private owners with flexible capital may be able to fund upgrades and wait for lease-up, whereas highly levered public-office landlords face a more punitive refinancing math if they must match the same concessions. Over 6-18 months, that favors owners with low near-term debt maturities and high-quality portfolios, but the evidence here is insufficient to support a direct sector trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No directional SCHW trade: treat the renewal as immaterial unless management identifies a broader corporate-real-estate cost initiative or material restructuring charge in upcoming filings.
- Monitor Dallas Class-A office leasing reports over the next 1-3 months for net absorption, effective-rent growth, and concession trends; a sustained improvement would be a watch catalyst for higher-quality office REIT proxies such as BXP, not a signal from this transaction alone.
- For any office exposure, require lease economics before acting: cash rent versus prior rent, tenant-improvement allowances, free-rent period, and debt maturity schedule. Falsify a quality-office recovery thesis if effective rents remain negative despite rising signed lease volume.
More News
- Meta AI agent triggers heavy selloff in banks, insurers, and travel stocks
- Financial stocks fall with AI and flattening yield curve in focus
- PayPal surges on Meta AI deal as tech rotation sinks financials
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- How Kevin Warsh’s rate hike exposed a 2-speed U.S. economy, with AI and housing at the poles
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts