
TJX Companies' Digital Reach: Can Engagement Lift Store Traffic?
Source: zacks.com
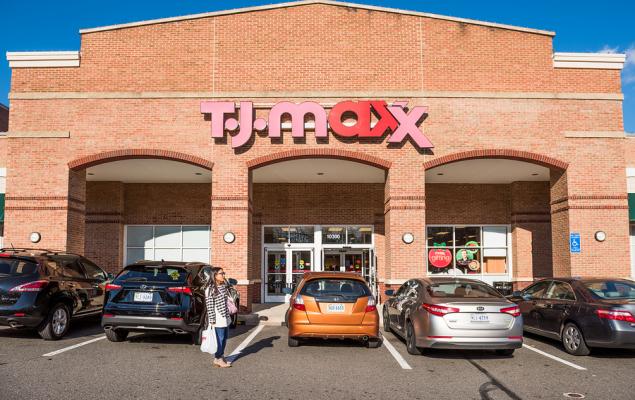
TJX recorded roughly 1.4 billion video views across its retail banners in the first half of fiscal 2027, with TikTok and YouTube completion rates significantly above industry benchmarks, supporting a larger digital and social-media push for fall and holiday shopping. The company is adding brands to TJ Maxx, Marshalls and Sierra e-commerce sites while using fresh merchandise and gifting initiatives to drive repeat store traffic. TJX shares are down 6.9% over the past month, but fiscal 2027 and 2028 consensus EPS estimates each rose $0.04 to $5.22 and $5.74, respectively.
Analysis
The investable question is not digital reach but whether paid/owned engagement converts into incremental transactions at an acceptable customer-acquisition cost. For TJX, a traffic-led comp acceleration would carry unusually high incremental margin because store labor and occupancy are largely fixed; conversely, a shift toward e-commerce fulfillment could dilute the off-price model’s cost advantage. The key holiday read-through is transaction growth, not online assortment breadth or video-view metrics, which are not independently validated measures of purchase intent.
ROST appears better positioned for a near-term traffic comparison given its demonstrated customer-frequency momentum, while BURL has the greatest upside torque if marketing begins converting flat transactions into traffic. TJX’s scale and vendor relationships make it the more defensible 6-18 month compounder: stronger demand visibility can improve opportunistic buying from branded suppliers managing excess inventory, reinforcing assortment quality and inventory turns. That same mechanism pressures department stores and full-price apparel retailers, which must clear inventory through markdowns rather than wholesale it into off-price channels.
Consensus may be over-attributing marketing to off-price demand that is more sensitive to real-income pressure, tariff-driven apparel inflation, and the availability of branded closeout inventory. A strong holiday could lift multiples across TJX/ROST/BURL, but sustained rerating requires evidence that traffic rises without a material increase in SG&A as a percent of sales. The thesis is falsified if holiday transactions lag basket growth, digital spending drives SG&A deleverage, or management reduces comp/operating-margin guidance at the next earnings update.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest long TJX over the next 1-3 months only on confirmation of traffic-led holiday comps; target a 10-15% upside from earnings revisions and modest multiple normalization, with a stop/review if management signals SG&A deleverage or transaction growth turns negative.
- Express the higher-beta traffic-recovery view through long BURL / short TJX in equal dollar amounts into BURL’s next earnings cycle, but only if channel checks show transaction growth improving from flat levels. Upside is a BURL multiple rerating on traffic inflection; exit if BURL remains basket-led or promotional spend rises without comp leverage.
- Prefer ROST over TJX tactically through the holiday sales read: its existing traffic momentum creates a lower evidentiary hurdle for an upside comp surprise. Reassess after holiday results; the trade fails if ROST’s traffic gains normalize sharply or gross-margin commentary points to elevated markdowns.
- Set an alert for reported holiday transaction growth and SG&A rate at all three off-price retailers. Do not underwrite a durable revenue benefit from engagement statistics alone; conversion, repeat visits, and marketing-cost disclosure are the missing data needed to upgrade conviction.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- Anthropic in talks to lease 1 gigawatt from Stream Data Centers- The Information
- Meta’s Muse AI is exploding in popularity—and already drawing heated backlash from another tech giant
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework