
TCL remporte six EISA Awards, illustrant ainsi sa suprématie dans le domaine des téléviseurs haut de gamme et des systèmes audio pour home cinéma
Source: PR Newswire
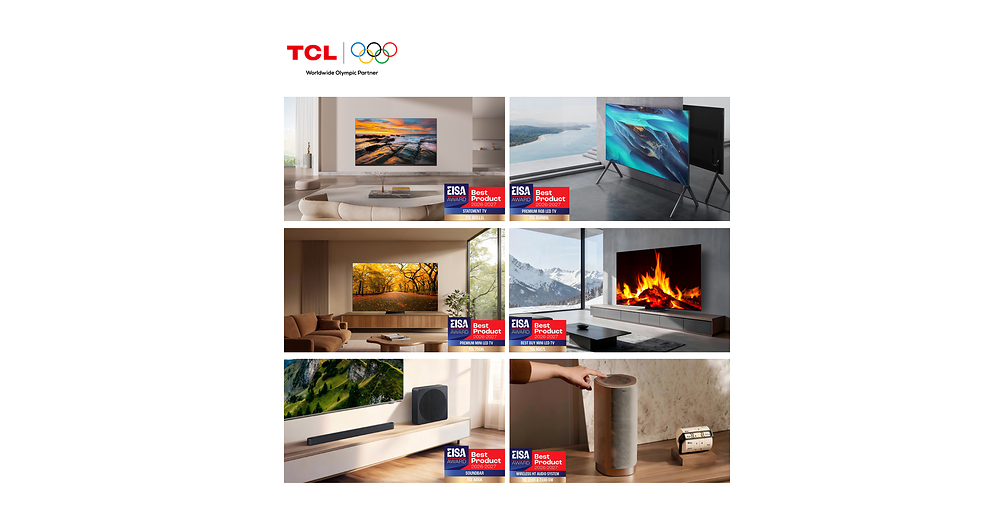
TCL annonce avoir remporté six EISA Awards, récompensant ses téléviseurs haut de gamme Mini LED et ses systèmes audio home cinéma. Les produits cités incluent le TCL 98X11L (jusqu’à 20 736 zones, 10 000 nits), le 85RM9L RGB-Mini LED (jusqu’à 4 000 nits) et le 75C8L (jusqu’à 5 500 nits), ainsi que des solutions audio signées Bang & Olufsen. L’annonce est globalement positive mais sans indication chiffrée d’impact financier immédiat.
Analysis
This is mostly a branding-and-channel-share signal, not a near-term earnings inflection. Awards can help TCL defend premium shelf placement and justify slightly better ASPs in Europe, but the financial transmission is slow: first via retailer assortment, then via mix, and only later via gross margin. The meaningful mechanism is that TCL’s vertically integrated panel/control stack can let it underprice Samsung/LG on premium large-screen mini-LED while still protecting unit economics better than brands that buy more of the bill of materials externally.
The second-order loser is the mid-tier value-TV cluster, especially brands competing on feature-per-dollar rather than on ecosystem or software. If TCL keeps winning “premium value” mindshare, the pressure is most acute in large-format sets where replacement cycles are long and consumers are willing to stretch for a showpiece product; that can squeeze competitors’ promotional intensity into the holiday season. BBY is a marginal beneficiary only if premium mix lifts basket size, but the retailer’s true exposure is to promotional cadence, not brand awards.
Contrarian view: the market should be careful not to extrapolate awards into demand. Consumer durables still need distribution, installation ease, and software experience to convert prestige into sell-through; if TCL’s after-sales/service or OS ecosystem lags, this becomes a margin story for the OEM rather than a durable share gain. The thesis would be falsified if TCL’s next two quarters show no mix improvement in Europe or if competitors respond with sharper promo funding, erasing any pricing benefit.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Watch-only alert on TCLHF: confirm with the next quarterly print whether premium TV mix and gross margin in Europe improve; without evidence of ASP lift, treat the award as marketing noise.
- Relative-value idea: long TCLHF / short a premium-TV incumbent with weaker cost structure on any channel-check evidence of shelf-share gains; target a 3-6 month window and exit if competitors cut promo prices by >5%.
- If you need a cleaner expression, avoid BBY as a direct long: any benefit from higher ticket size is likely too small to matter unless premium TV category growth accelerates into holiday sell-through.
- For contrarian positioning, consider fading any spike in TCLHF after the announcement; the risk/reward favors waiting for independent channel data rather than paying for reputation alone.
More News
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit
- AI Research Systems for Hedge Funds: A Pilot Design