
Cypress Creek Energy's Ostrea Solar Reaches Commercial Operation, Helping Power Nation's Fastest-Growing State Economy
Source: PR Newswire
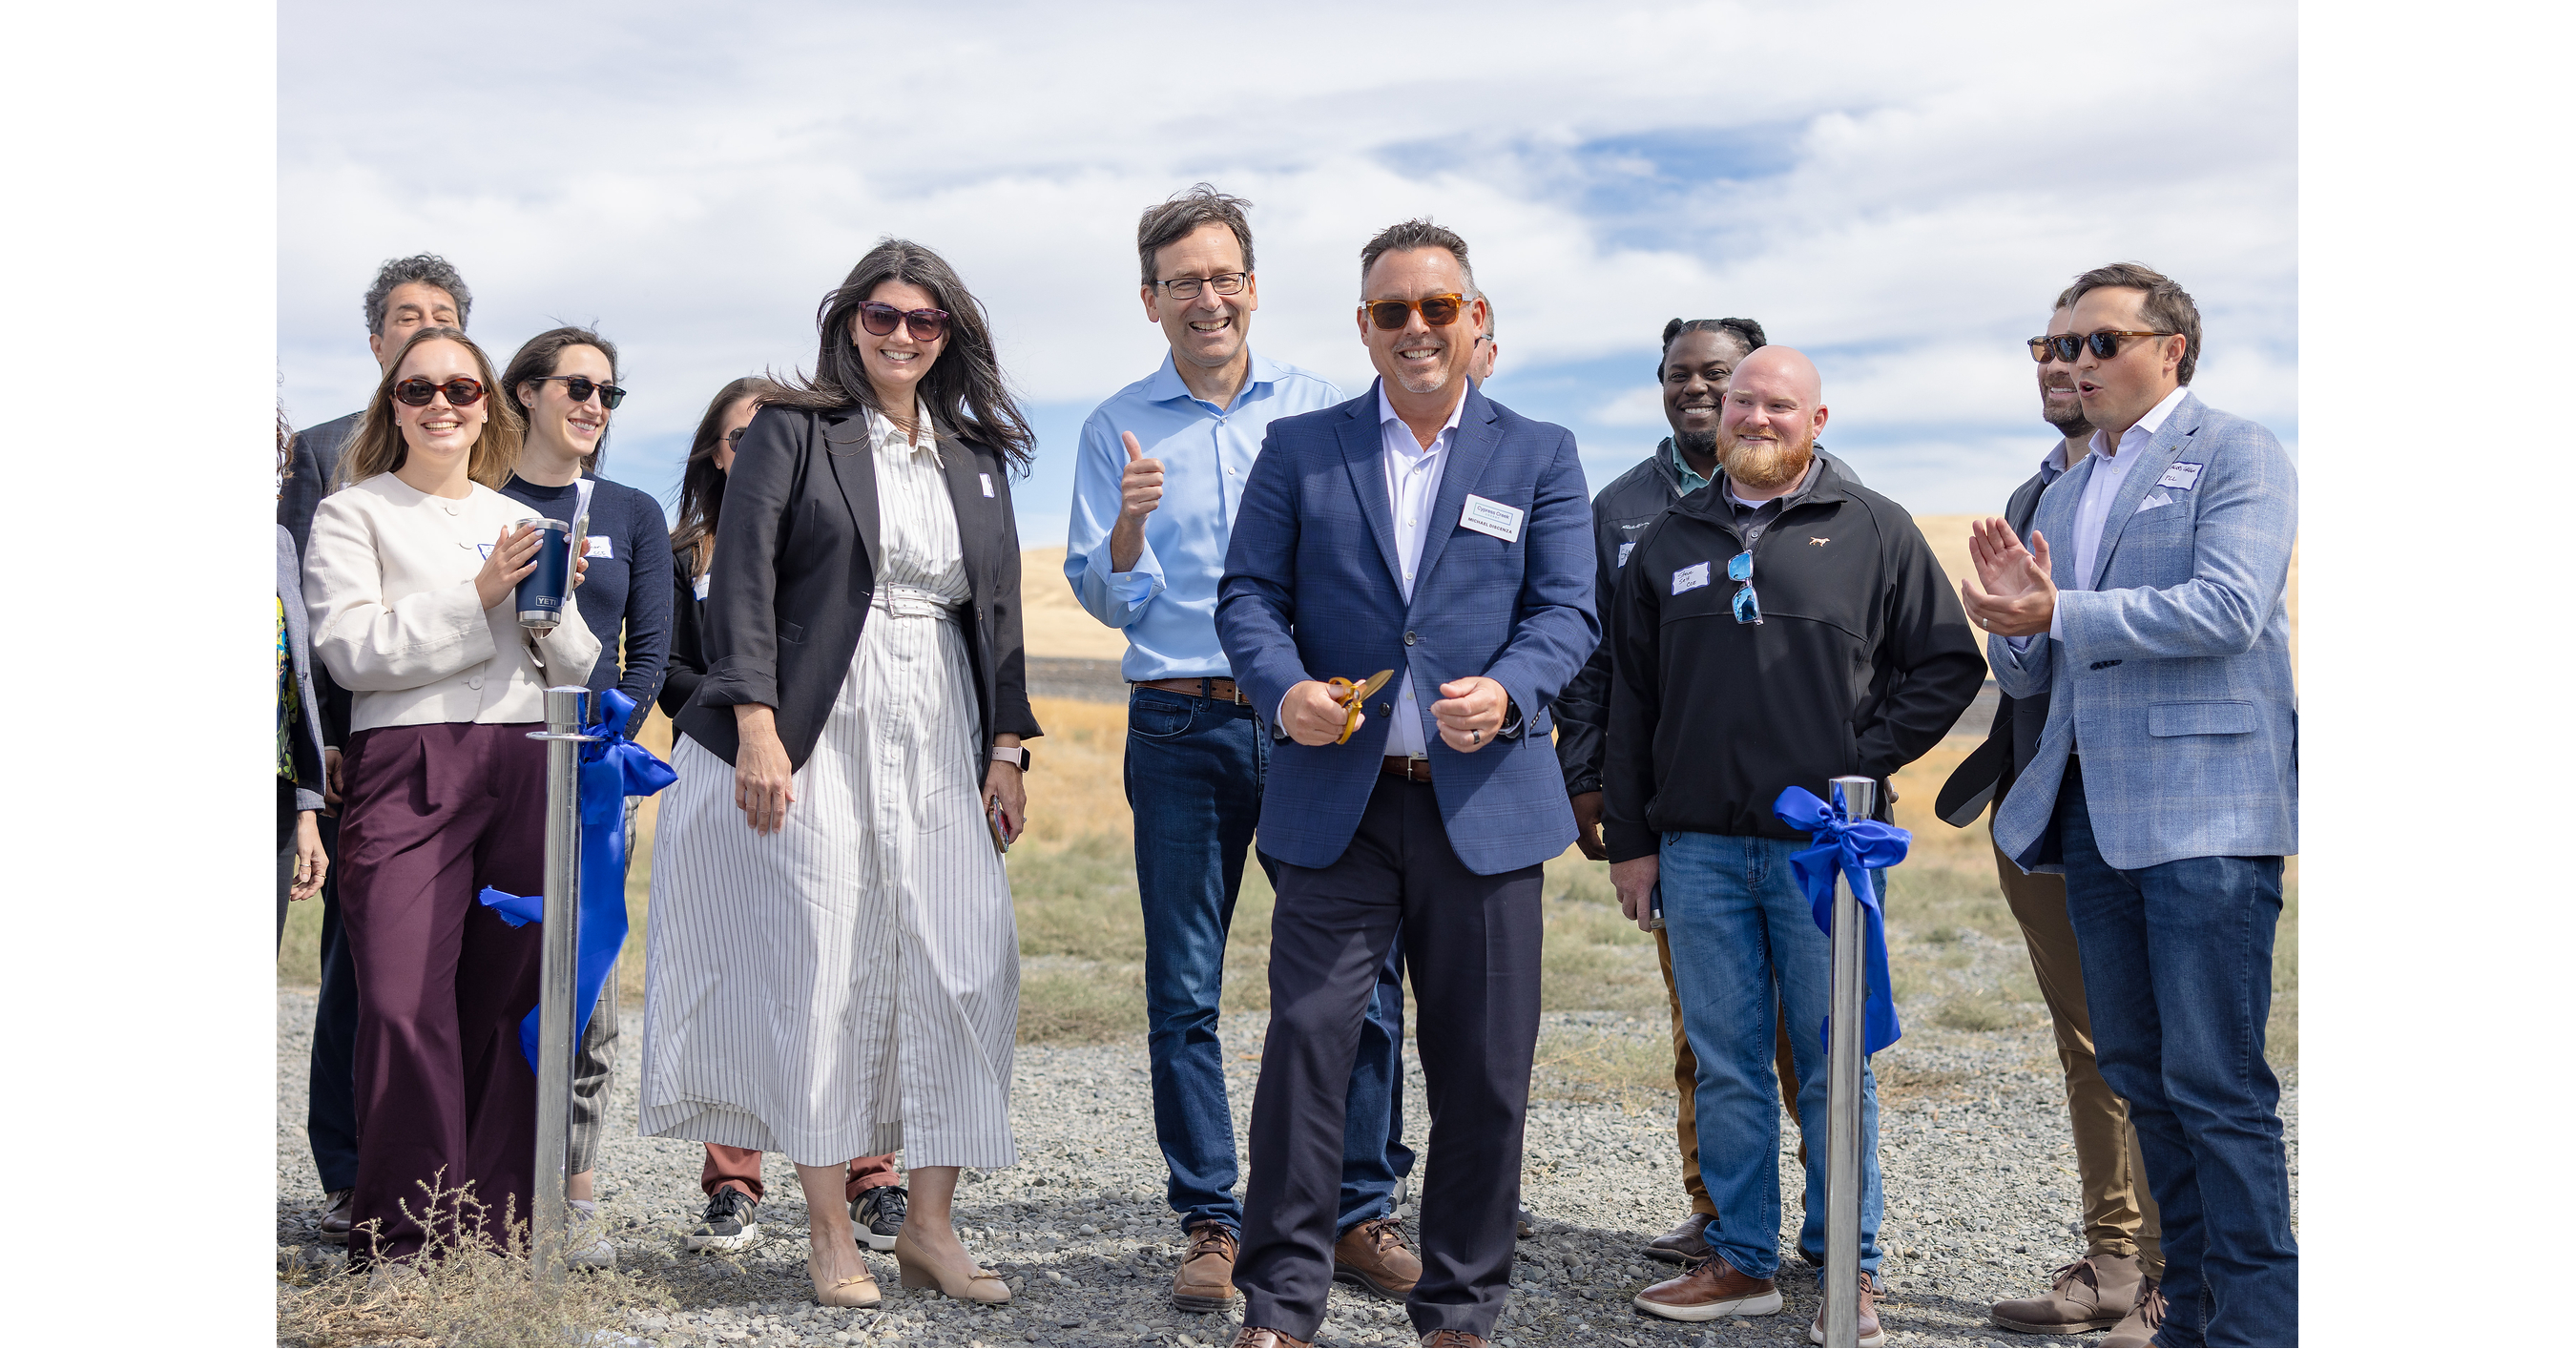
Cypress Creek Energy’s Ostrea Solar reached commercial operation, adding 104 MWdc / 80 MWac of generation to Washington’s grid and completing ~$180 million of privately funded infrastructure. Microsoft has signed a long-term power purchase agreement for electricity and environmental products from the project. Over its operating life, the project is expected to generate ~$13.3 million in state and local tax revenue, alongside major construction job creation (~300 jobs) and conservation stewardship for ~275 acres of critical habitat.
Analysis
The investable signal is not the solar project itself; it is Microsoft continuing to pre-negotiate electrons before they become a bottleneck to AI and cloud expansion. That reduces a small but real execution risk: if power availability or local permitting slows data-center expansion in Washington, the market would eventually haircut near-term cloud capacity growth assumptions. The marginal benefit is more about optionality and local license-to-operate than immediate P&L impact.
The second-order winners are developers and grid-adjacent firms with the ability to deliver contracted generation into constrained load pockets. Over 6-18 months, repeated hyperscaler PPAs should support a premium for projects with interconnection rights and transmission access, while merchant power sellers in the Pacific Northwest lose some pricing leverage at the margin. The real constraint is not module supply; it is queue position, transmission, and community acceptance.
Near term, this is probably a low-beta positive for MSFT rather than a rerating event. The thesis is falsified if Microsoft trims AI capex, shifts incremental data-center builds out of the region, or if BPA/interconnection delays turn contracted capacity into paper capacity. In that case, the market will correctly reclassify these PPAs as ESG optics rather than operational de-risking. The contrarian read is that consensus may be overestimating the earnings impact and underestimating the strategic value of securing local power before scarcity becomes visible in service levels and build timelines.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Add MSFT on 1-2% post-news weakness only, 1-3 month horizon; thesis is incremental de-risking of Washington compute expansion, not an immediate revenue driver. Falsify on any reduction in AI/data-center capex commentary or a shift in build geography.
- No trade in the solar-specific small caps from this headline set; the project-level PPA is too small to justify chasing names like CETY/EESE/WSOUF absent a disclosed economics update or backlog conversion.
- Set a watch item on TAN / ICLN for confirmation of follow-on hyperscaler PPAs and new CODs over the next 1-2 quarters; buy only if the market starts pricing a broader utility-scale solar reacceleration rather than a one-off PR event.
- Use MSFT strength as a relative-value short-term hedge against power-scarcity narratives: if the stock rallies on ESG optics but cloud guidance is unchanged, fade the move rather than chase it; upside is modest unless management explicitly ties PPAs to faster capacity additions.
More News
- Five things to watch in markets in the week ahead
- IREN's AI Pricing Is Exploding — Why the Neocloud's $2.6 Billion Contract Base Could Scale Dramatically
- Amgen Shares Fall as Novartis' Pelacarsen Misses Phase III Study Goal
- AstraZeneca Secures FDA Nod for New Breast Cancer Therapy Etcamah
- Is UBER Stock a Buy as It Closes in on Delivery Hero Buyout?
- AMD Is Behind The AI Chip Shift Nobody Is Talking About