
The 3rd GTI Forum on Digital Intelligence, Hong Kong Advances Global Inclusive AI Development
Source: PR Newswire
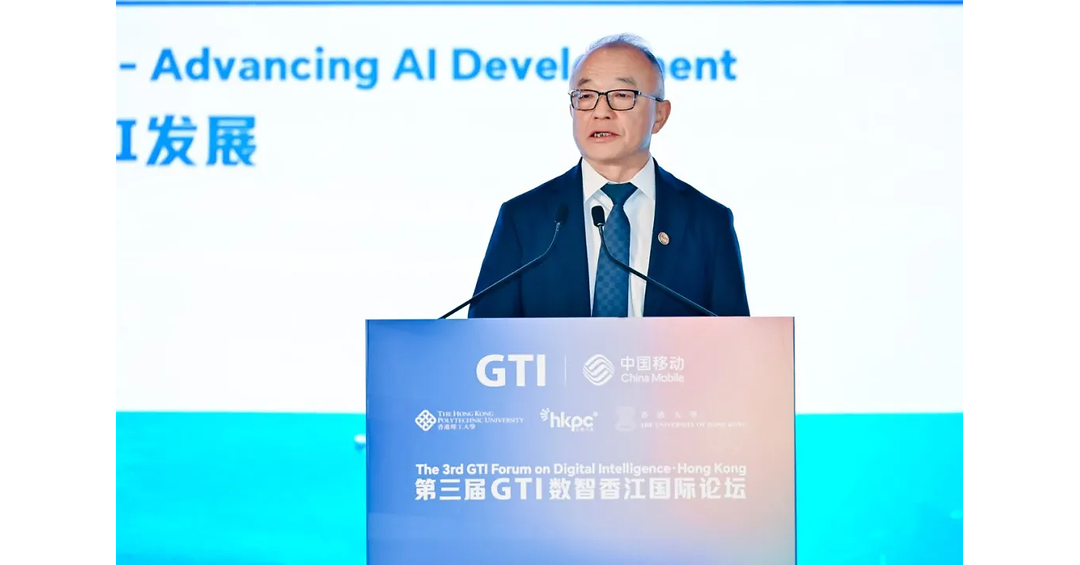
GTI and China Mobile outlined expanded global AI collaboration at the Sept. 8 Hong Kong GTI Forum, emphasizing AI infrastructure, governance, cross-border cooperation and sector applications. GTI cited eight open laboratories across Asia, Europe and North America, a 6G open testbed, more than 50 white papers and research reports, and a global innovation challenge with GSMA. China Mobile and partners released an AI security-governance white paper and security capability system, launched the AI4S Scientific Workstation international edition, and presented a 6G base-station and terminal prototype achievement.
Analysis
This is strategically supportive for China Mobile (0941 HK) but not a near-term earnings catalyst: consortium launches, white papers and testbed prototypes do not establish incremental contracts, deployment commitments or return-on-capital economics. The investable implication is that China Mobile is attempting to defend its role in the AI value chain as traffic monetization matures, shifting toward enterprise cloud, compute scheduling and agent-related services. That could improve revenue mix over 6-18 months, but only if enterprise AI adoption converts into paid workloads rather than subsidized ecosystem investment.
The more relevant competitive issue is capex discipline. A telco-led push for integrated network/compute infrastructure can support domestic equipment demand for ZTE (0763 HK) and China Mobile’s cloud ecosystem, while raising the risk that China Telecom (0728 HK) and China Unicom (0762 HK) respond with parallel AI-network spending that depresses sector FCF and dividends. Governance and cross-border-data ambitions should not be capitalized into valuations: tighter security standards could instead lengthen procurement cycles and favor incumbents with compliant domestic stacks. Near-term market impact is likely negligible; the 1-3 month catalyst would be disclosed AI-cloud orders, capex guidance, or a commercial 6G/AI-network pilot rather than further forum announcements.
Contrarian view: investors may overread ‘AI infrastructure’ language as an immediate hardware cycle. China’s operators have historically absorbed strategic buildouts at regulated or low returns, so the first-order beneficiary may be enterprise customers receiving lower-cost AI connectivity, not shareholders. The thesis turns more constructive only if 0941 demonstrates rising cloud/DICT revenue growth without an upward revision to capex intensity or pressure on shareholder distributions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No directional trade on the announcement; treat it as a watch item rather than a catalyst because no contract value, customer commitment, deployment timetable or financial target is disclosed.
- Maintain a quality bias within Chinese telecoms: prefer long 0941 HK versus short 0762 HK over the next 6-12 months only if China Mobile’s next results show AI/cloud revenue acceleration while capex-to-revenue remains stable. Exit if capex guidance rises materially without corresponding enterprise-service guidance; the principal risk is industry-wide state-directed spending.
- Monitor ZTE (0763 HK) for a selective equipment read-through, not an immediate purchase. Upgrade the view only on verified orders for AI-network, compute-cluster or 6G-testbed equipment; falsify on operator procurement data showing vendor-share loss or a broad telecom capex cut.
- For existing China telecom exposure, set an alert around upcoming quarterly results for cloud/DICT growth, total capex and dividend policy. A widening gap between AI rhetoric and monetization, evidenced by higher capex with flat service revenue, would favor reducing sector exposure over the following 1-3 months.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- Biotech stocks are surging. How investors can play the new drug innovation boom
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
- Sudan’s soaring fuel prices make getting by harder for workers