
Cousins Properties Still A Buy, Q2 Results Show Durability In Premium Office Markets
Source: seekingalpha.com
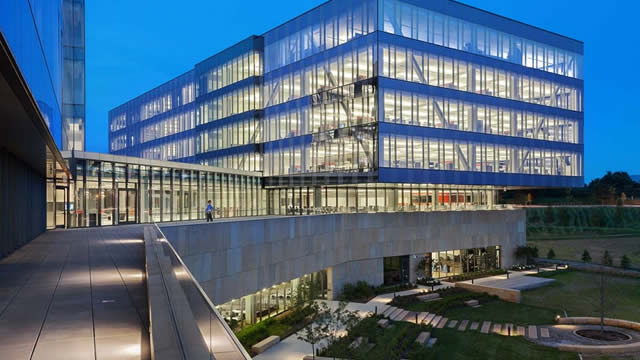
Cousins Properties (CUZ) was reaffirmed as a Buy on the back of Sunbelt-focused Class A office assets, with Q2 showing 920,000 sq. ft. leased and portfolio occupancy of 92.8%. Year-over-year FFO grew, alongside an apparent low leverage risk, and the stock trades at a meaningful discount to sector medians on price/book and forward earnings—supporting an undervaluation/long-term upside thesis.
Analysis
CUZ looks less like a macro office bet and more like a quality-spread trade inside an unloved sector. The market tends to price all office REITs off the weakest names, so the real edge is that a modern, Sunbelt-heavy portfolio can still compound cash flow while the broader asset class is being repriced for structural obsolescence. That creates upside not just from leasing, but from multiple re-rating if public markets start distinguishing between scarce institutional product and stranded legacy stock.
The second-order winner is the lender/CMBS ecosystem tied to better collateral: low leverage gives CUZ optionality to refinance, buy back stock, or selectively acquire assets from stressed competitors at cycle trough valuations. The losers are highly levered office owners with older urban footprints and heavier near-term debt walls, where any incremental cap-rate expansion can wipe out equity faster than leasing can repair occupancy. The more important competitive dynamic is that CUZ can use tenant flight-to-quality to steal share, but only if tenants remain committed to hybrid normalization; if corporate space demand rolls over, even best-in-class assets become a timing trade rather than a secular winner.
Catalysts are mostly 1-3 quarters: next earnings prints should show whether leasing momentum converts into durable FFO per share after tenant improvement and free-rent costs. Over 6-18 months, the key variables are Sunbelt supply additions, refinancing spreads, and whether the office market keeps bifurcating or broadens into a healthier recovery. The thesis is falsified if occupancy stalls, leasing spreads compress, or management is forced to prioritize retention over economics; a sharp backup in Treasury yields would also delay any NAV re-rating.
The contrarian view is that the discount may be smaller than it looks once you haircut for ongoing capex and the probability that "good" office still earns a structurally lower multiple than before. In other words, CUZ can be the best house in a bad neighborhood and still remain cheap for longer than the market expects.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Long CUZ on pullbacks as a 3-6 month quality-spread trade; target a re-rating toward higher-quality office comps, with a stop if the next two quarters fail to show continued FFO/share improvement.
- Pair trade: long CUZ / short SLG or VNO over the next 1-2 quarters to express balance-sheet and asset-quality dispersion within office; thesis breaks if office leasing broadens unexpectedly or rates fall sharply.
- Use CUZ as a relative-value hedge against broader REIT exposure: reduce generic office beta in XLRE/IYR and rotate into CUZ only if leasing metrics keep improving while debt costs stay contained.
- Alert item: if the 10Y Treasury backs up materially and office cap rates widen another 50-75 bps, de-risk CUZ despite the cheap multiple; the valuation case is leverage-sensitive.
- Watch for management commentary on tenant improvement spend and renewal economics; if growth is being bought with excessive concessions, the apparent undervaluation is a value trap rather than a re-rating candidate.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand
- Schott Pharma drops after Deutsche Bank downgrades on demanding valuation
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Research Agent?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction