
AITO jette les bases d'une croissance mondiale grâce à l'excellence de ses produits et à sa reconnaissance sur le marché.
Source: PR Newswire
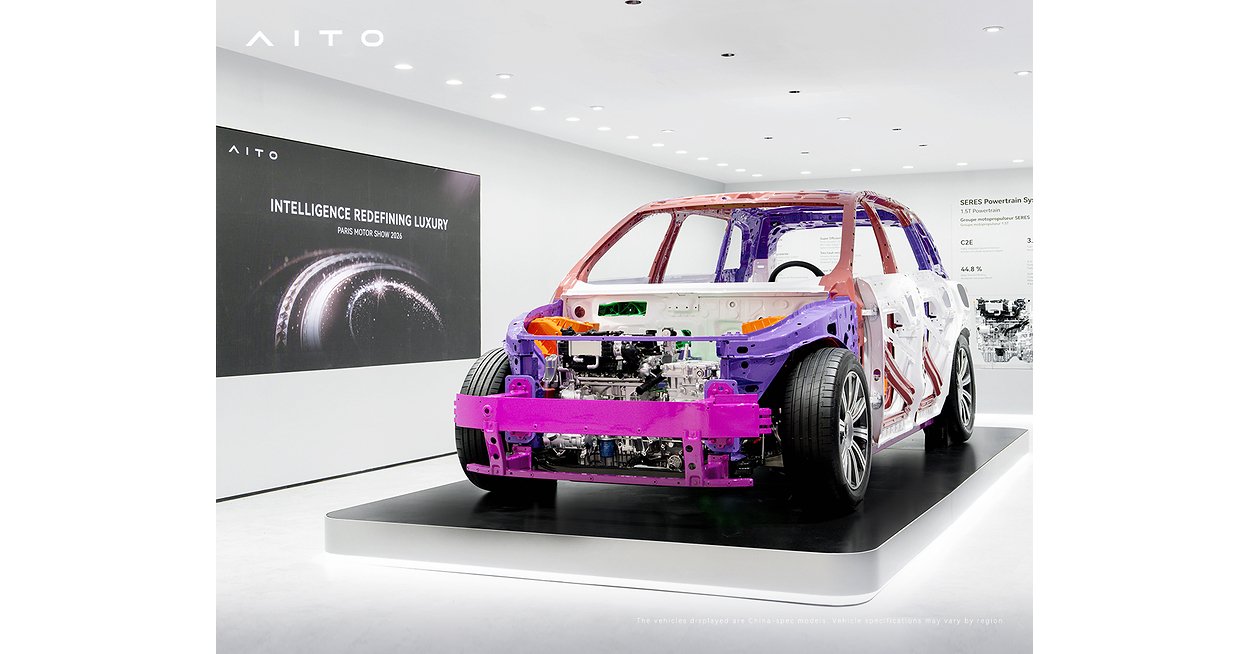
AITO said it plans to enter the European market in autumn 2027, citing its vehicle platform, manufacturing capabilities and service ecosystem. The company reported more than 1.2 million customers and over 1 million cumulative deliveries in 46 months; its SERES superfactory uses more than 3,000 robots and connects over 300 supply-chain partners. The article also cites AITO’s luxury-brand rankings and awards in China, but provides no financial results or near-term sales targets.
Analysis
This is a brand-positioning announcement, not evidence of incremental orders, European revenue, or improved unit economics. Treat the stated autumn 2027 entry as a long-dated option: near-term earnings sensitivity is negligible, while the commercial proof points—homologation, pricing after tariffs, distribution and service coverage, and repeatable customer acquisition—remain unreported. The promotional quality and brand rankings should not be capitalized into valuation without independently verified methodology and comparable data.
If AITO establishes competitive European pricing and credible aftersales support, pressure would fall first on premium plug-in and electric SUVs from established European manufacturers; a second-order response could be more discounting, weakening residual values, and lower returns on their own EV investment. Conversely, local parts inventory, service staffing, and regulatory compliance could make expansion materially more capital- and working-capital-intensive than the factory narrative suggests. Global supplier relationships do not establish European sourcing, purchase commitments, or supplier economics.
The key horizon is 6–18 months, when market access and operating commitments should become observable; there is no clear near-term catalyst in this release. The contrarian point is that engineering scale and customer counts in China do not automatically transfer to Europe, where brand recognition, privacy and driver-assistance rules, tariffs, and service trust may constrain conversion. Thesis improves with disclosed European homologation, pricing, delivery targets and funded service coverage; it weakens if entry slips or requires uneconomic discounting. Company identities and tradable instruments were not supplied, so avoid assigning a ticker or making a security-specific valuation claim.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No trade on the announcement alone; classify as a long-dated competitive watch item rather than a near-term earnings catalyst.
- Over the next 1–3 months, monitor for verifiable European homologation progress, distributor/service commitments, pricing and import/localization plans. Treat promotional brand or factory claims as unconfirmed until corroborated.
- For European premium-auto exposure, watch discounting and residual-value data as falsifiers: absent evidence of AITO deliveries or price-led share gains, do not infer material impairment to incumbents.
- Reassess in 6–18 months if AITO provides delivery targets and funding details; a delay, tariff-driven price disadvantage, or weak aftersales coverage would undermine the expansion case.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- SK Hynix plunges 8% amid Asia tech rout as Fed rate hike fears, AI funding worries mount
- Why is Samsung Electronics stock plunging today?
- Why is Advantest stock plummeting today?
- Japan, U.S. reach first chip deal under $550 bln investment plan
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems