
Parex Resources: The Widening Discount Is Temporary
Source: seekingalpha.com
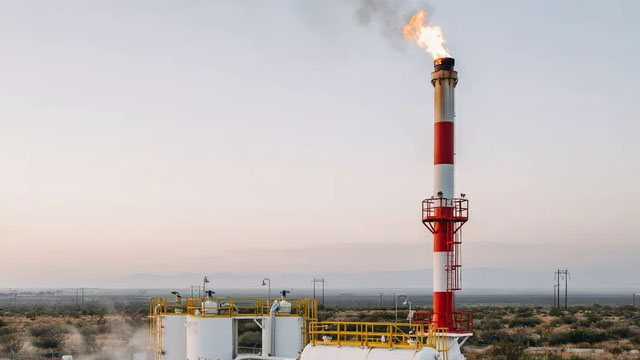
Parex Resources reported Q3 results with widening discounts, increased costs, revised guidance and lower free cash flow forecasts. The company remains materially larger following acquisitions and has higher production; it attributed most cost increases to one-time acquisition and optimization expenses that are expected to fade over time.
Analysis
The key valuation question is whether the lower cash-flow outlook reflects a temporary integration bill or a weaker recurring netback. If wider realized-price discounts persist, each added barrel contributes less cash than production growth alone implies; if they normalize while acquisition and optimization costs roll off, the enlarged production base could support a recovery. The market may be underweighting the first risk and over-crediting the second: “one-time” costs are a management characterization until subsequent quarters show lower unit costs and cash conversion.
Near term (days), revised expectations can cap rallies as investors reset cash-flow assumptions. Over 1–3 months, watch realized price differentials, unit operating costs, production delivery, and cash flow after capital spending—not headline production alone. Over 6–18 months, sustained improvement in those measures would validate integration benefits; persistent discounts or repeated “temporary” expenses would turn the acquisition story into a lower-quality cash-flow profile. No reliable valuation or balance-sheet conclusion is possible from the supplied information; verify net debt, hedging, and the revised production and spending assumptions.
Contrarian angle: higher scale may improve fixed-cost absorption, but that benefit only matters if incremental production converts to cash. The appropriate stance is cautious rather than automatically bearish: the cost normalization thesis is plausible, but not yet demonstrated.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Ticker Sentiment
Key Decisions for Investors
- Do not chase PXT on production growth alone. Before adding, verify quarterly realized differentials, operating cost per barrel, free cash flow after capital spending, and whether acquisition-related costs actually decline.
- For a 1–3 month event-driven expression, consider a small, defined-risk bearish position in PXT only if the next update shows persistent discount pressure, another reduction to cash-flow expectations, or costs failing to moderate. The thesis is invalidated by improving realized pricing and unit costs alongside cash-flow delivery.
- Avoid an undifferentiated oil-sector short: crude-price strength could mask company-specific execution. If relative-value liquidity and exposures permit, assess PXT against a broad energy proxy, but confirm correlation, currency, and commodity mix before sizing.
- Set alerts for guidance changes, realized-price differentials, production versus plan, unit costs, and net debt. Without those figures and current valuation, there is not enough evidence for a high-conviction outright trade.
More News
- Here are the 2 big things we're watching in the stock market in the week ahead
- China AI bust threatens Xi’s ’Wall Street East’ ambitions
- As tech swoon roils market, US inflation data on tap
- Berkshire Hathaway speeds up stock buybacks, though profit falls
- Cabaletta Bio reports phase 1/2 data for autoimmune therapy
- Nvidia CEO Jensen Huang faces bipartisan congressional scrutiny over reported China spy link