
Accuray and Samsung NeuroLogica Advance Volumetric Imaging Collaboration for the Accuray CyberKnife® Platform
Source: PR Newswire
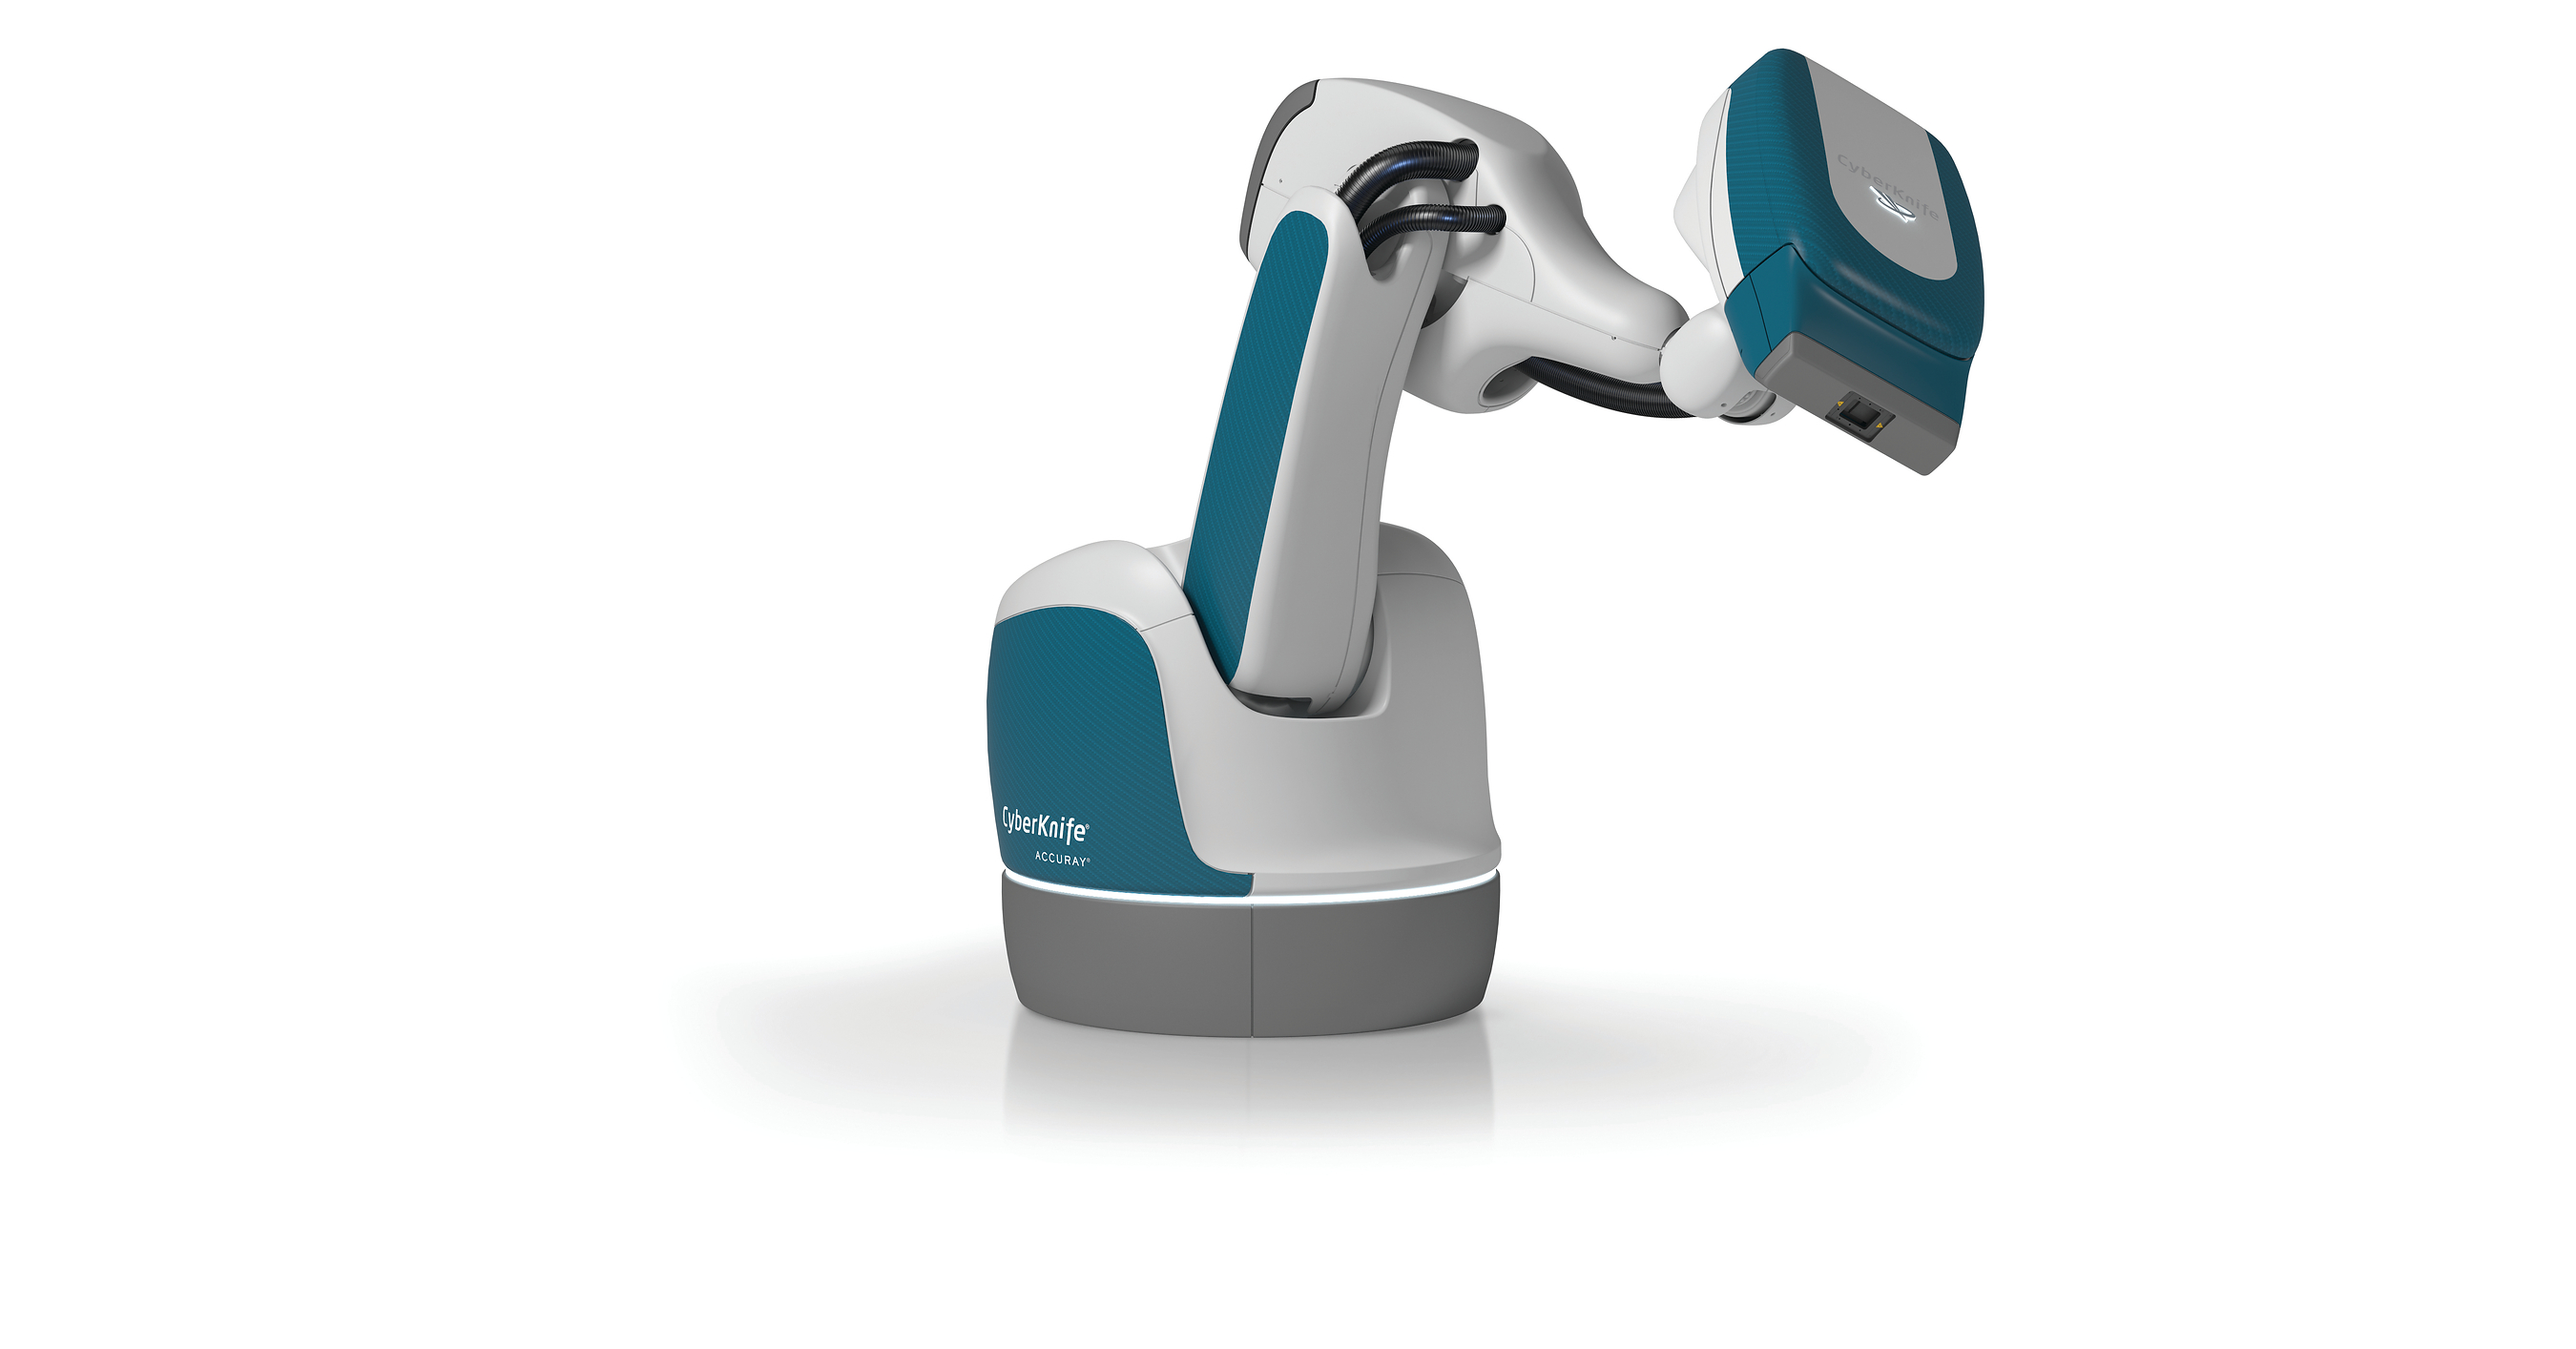
Accuray entered a collaboration with Samsung NeuroLogica to evaluate advanced mobile CT-based volumetric imaging capabilities for its CyberKnife robotic radiosurgery system. The phased initiative combines Samsung's mobile CT expertise with Accuray's precision treatment delivery and motion-management technology, with The Royal Marsden as the first participating center. No commercial product, financial terms, or launch timeline was announced, and development remains subject to technical, clinical, commercial, and regulatory evaluation.
Analysis
This is strategically sensible but financially immaterial until Accuray discloses a product roadmap, regulatory pathway, installed-base upgrade economics, and reimbursement/throughput benefit. The key valuation mechanism is not imaging differentiation alone: it is whether an integrated workflow raises CyberKnife utilization, supports premium pricing, or lowers customer capital-budget friction. Without those data, the partnership is more likely to sustain the innovation narrative than alter FY27 revenue or EBITDA expectations.
The near-term market response may be positive because the collaboration addresses a visible feature gap versus adaptive-radiotherapy ecosystems from Elekta (EKTA-B.ST) and Varian/Siemens Healthineers (SHL.DE). However, Samsung supplies a component rather than conferring exclusivity, and independently developed integration, clinical validation, and regulatory clearance can extend commercialization well beyond 12 months. The greater risk is that imaging integration increases system cost and workflow complexity before it produces enough throughput gains to justify hospital ROI.
Over 6-18 months, a successful launch could improve ARAY's competitive position in prostate, lung and abdominal indications where treatment adaptation can reduce uncertainty around anatomy. The more investable second-order signal would be reference-site conversion into orders, particularly if upgrades attach to the installed base; upgrades generally carry better gross-margin and working-capital characteristics than new-system placements. Conversely, failure to identify a reimbursable or productivity-linked use case would make this another clinical-concept announcement with no backlog impact.
Contrarian view: the announcement is not yet a reason to chase ARAY. Small-cap medtech investors often capitalize strategic collaborations before commercial terms exist, while ARAY's balance-sheet and execution sensitivity makes multiple expansion contingent on demonstrable order conversion. Treat any ASTRO-driven strength as an opportunity to demand evidence, not as confirmation of a new earnings cycle.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.24
Ticker Sentiment
Key Decisions for Investors
- No new directional ARAY position on this announcement alone. Reassess after the next earnings release for disclosed development milestones, incremental R&D, backlog/order commentary, and a quantified installed-base upgrade opportunity; absent these, expected fundamental impact remains de minimis over 1-3 months.
- For an existing ARAY long, retain only a small tactical position through ASTRO-related attention and use a 10-12% downside stop from entry. Add only if management identifies a regulated commercial product and indicates first customer orders within 12 months; that would create a credible path to higher-margin service/upgrade revenue.
- Monitor ARAY versus Elekta (EKTA-B.ST) and Siemens Healthineers (SHL.DE) over the next two quarters. A sustained ARAY relative outperformance without backlog growth or gross-margin improvement is a fade signal; the larger platforms retain superior bundling, service coverage, and hospital purchasing leverage.
- Set an alert for covenant/liquidity disclosures, guidance reductions, or product gross-margin deterioration at the next 10-Q/earnings update. Any of these would falsify the thesis that partnership-led innovation can offset execution and capital-structure risk, favoring an ARAY short or avoidance rather than a long.
More News
- Anthropic CEO Amodei to have dinner with Trump at White House
- Here are the 4 big things we're watching in the stock market in the week ahead
- Paramount Warner Deal Tests Hollywood’s Future
- ‘China has arrived’: From $1,000 Gucci sneakers to German cars, China is coming for the industries that made Europe rich
- OpenAI, Anthropic CEOs called to appear at Australian AI probe
- Apple, Microsoft, and Meta prove stock picking for individuals is not a fool's errand