
Financial Markets Turn Quiet Before Key Xi-Trump Summit
Source: Bloomberg
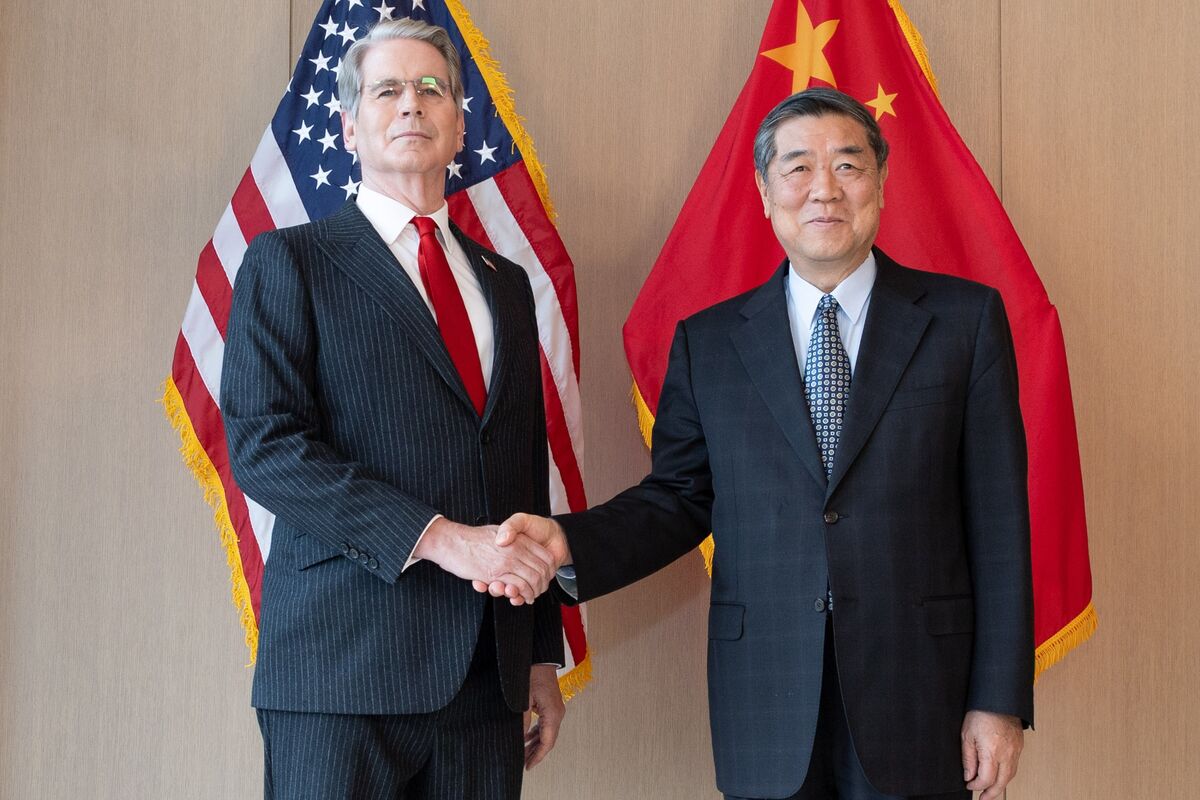
Markets entered a holding pattern ahead of this week's Xi-Trump summit, with MSCI's Asia-Pacific benchmark up 0.5%, S&P 500 futures little changed and the dollar broadly flat. Unresolved inflation, rising government debt and the war in Iran remain key risks, while the 10-year Treasury yield held near 4.97%. The summit could affect risk sentiment and trade-policy expectations, but markets showed limited directional conviction before the meeting.
Analysis
The market is assigning meaningful value to a near-term de-escalation outcome while leaving the rates complex largely unhedged. A constructive summit headline would most directly compress the China-risk discount in FXI/KWEB and relieve tariff-related margin uncertainty for US import-heavy retailers and industrials; however, a rally is likely to be capped if long-end yields remain near 5%, since the discount-rate headwind offsets much of the multiple-expansion case for long-duration Chinese internet and US semiconductors.
The more asymmetric outcome is disappointment: renewed tariff threats or an absence of concrete implementation mechanisms would hit Chinese equities and global cyclicals quickly, while offering only limited upside to defensive US assets if inflation and sovereign-supply concerns keep Treasury term premium elevated. Over the next 1-3 months, the key transmission channel is corporate guidance: management teams can defer capex and inventory commitments under policy uncertainty, pressuring XLI and semiconductor equipment demand before reported earnings show it. Over 6-18 months, durable trade restrictions would favor North American and Southeast Asian manufacturing substitutes, but the first-order beneficiary is not necessarily US manufacturers; it is firms with established non-China capacity and pricing power.
Consensus appears too focused on the bilateral headline and not enough on whether any agreement changes the inflationary arithmetic. A trade thaw that lowers tariff pass-through could modestly help inflation expectations and duration, but Iranian-war-related energy risk and Treasury issuance can dominate that effect. The thesis is falsified by a sustained 10-year yield break below 4.60% alongside credible trade implementation details, which would support a broader risk-on rerating rather than a narrow tactical bounce.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
-0.05
Ticker Sentiment
Key Decisions for Investors
- Do not add outright beta before the summit; use a 48-72 hour post-event confirmation window. A concrete tariff rollback or enforcement framework plus a 10-year yield below 4.85% would justify a tactical long FXI or KWEB for a 1-3 month rebound; exit if policy language remains aspirational or yields retake 5.10%.
- Express the asymmetric negative outcome with a 1-2 month pair: long SPLV / short XLI. Industrial order books and capex expectations are more exposed to renewed trade uncertainty, while low-volatility domestic defensives have less direct supply-chain sensitivity. Cover the short if a verified agreement triggers upward revisions to industrial guidance.
- Maintain an inflation-duration hedge rather than buying broad equities on diplomatic headlines: short TLT or use put spreads if the 10-year yield remains above 4.95%. The hedge should be removed on a sustained move below 4.60%, which would indicate that disinflation and trade détente are overcoming fiscal term-premium pressure.
- Watch semiconductor supply-chain dispersion rather than taking blanket SMH exposure. A trade agreement without restrictions on advanced-chip exports is required before favoring SMH; otherwise, prefer quality US domestic-exposure defensives over China-sensitive equipment and memory names.
More News
- Trading Day: AI euphoria back with a bang
- Iran ready to reopen Strait of Hormuz if US eases military pressure and lifts blockade
- U.S. Treasury yields ease as investors await fresh jobs data, Fed comments
- Iran’s Pezeshkian meets Pakistan’s Naqvi in Tehran as tensions with US rise
- Nvidia’s Stock Is Flashing a Warning Sign as Valuation Falls
- Trump to speak at UN; Alibaba’s new AI chip - what’s moving markets