
Sonos Beam Ultra Soundbar Ace Ultra Headphones Review: a Fresh Era for the Brand
Source: Bloomberg
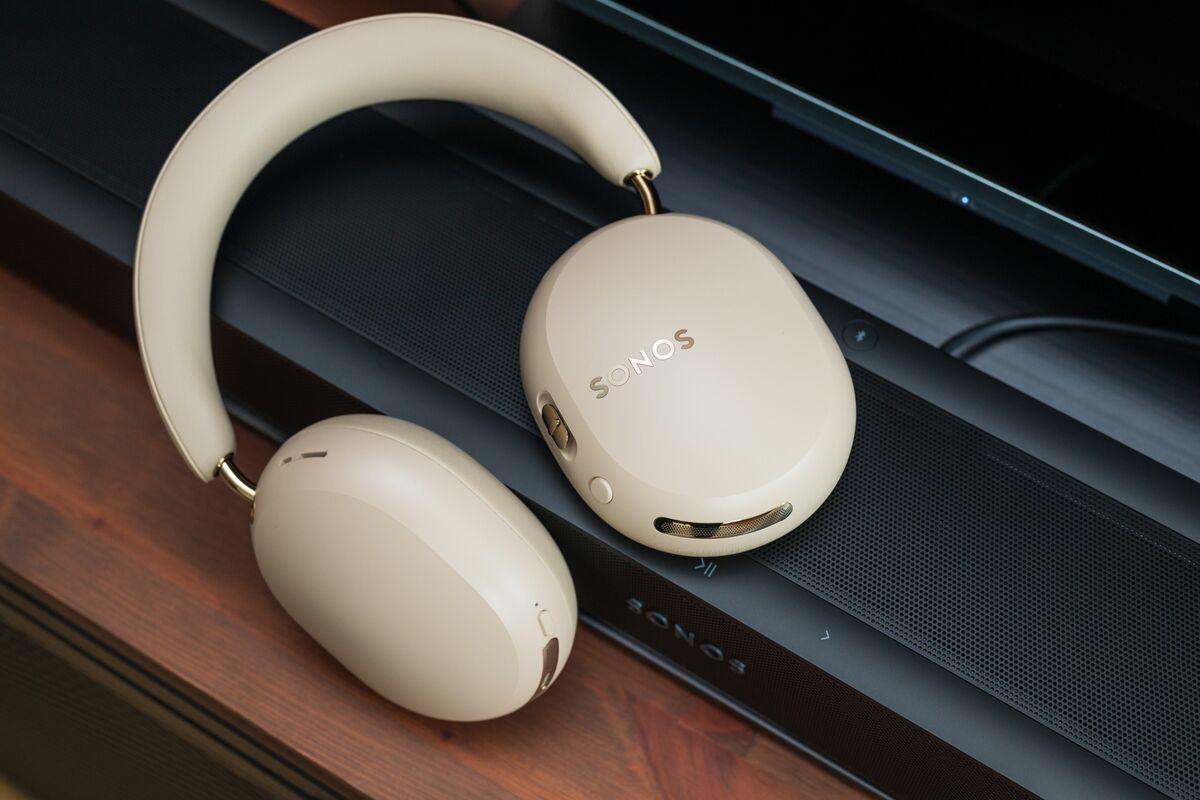
Sonos launched the $699 Beam Ultra soundbar and $449 Ace Ultra headphones, signaling a product-led recovery from its 2024 app disruption. The devices emphasize Sonos' whole-home audio ecosystem strategy under CEO Tom Conrad, while Sonos 27 introduces AI capabilities including a smarter voice assistant scheduled to roll out later this fall. The launches are a constructive brand and product update, though the article provides no sales, margin, or guidance figures.
Analysis
The key question is not whether the new hardware reviews well, but whether Sonos can convert a premium-device refresh into higher attach rates and lower support costs after the app failure damaged replacement-cycle demand. At these price points, modest unit volume is unlikely to move FY earnings materially; the more important 1-3 month catalyst is evidence that product registration, direct-to-consumer conversion and return rates normalize without incremental promotional spending. A successful software rollout could also lift gross margin through ecosystem attachment, but AI features are primarily retention tools unless they create subscription or service revenue.
SONO remains exposed to a difficult competitive set: Apple, Bose and Sony can subsidize audio hardware through broader device ecosystems, while Samsung and LG bundle audio into TV-led promotions. The potentially favorable second-order effect is that a stable platform reduces customer hesitation to add rooms or categories, improving lifetime value and reducing dependence on the seasonal soundbar cycle. Conversely, a new software defect would carry disproportionate reputational damage because management has explicitly centered the recovery narrative on platform reliability.
Consensus may overread enthusiast coverage as proof of a broad demand recovery. Premium headphones and soundbars are discretionary purchases, and the price architecture likely limits unit elasticity unless holiday discounting broadens the addressable market—at the expense of margin. The stock needs independently verifiable signs of reduced churn and restored operating leverage, not merely a favorable launch-week reception.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- Maintain SONO as a watchlist long rather than initiating on launch coverage. Reassess after the next earnings release if management shows sequential improvement in gross margin, direct-channel mix and FY holiday demand commentary; absent these metrics, the product cycle is not enough to underwrite a rerating.
- For a tactical 1-3 month expression, consider a small SONO long only on post-launch evidence of limited discounting and stable software-support trends, with a stop on a renewed app-related outage or a guidance cut. Upside is multiple recovery if execution credibility returns; downside remains asymmetric because another reliability issue would revive the prior trust discount.
- Avoid treating AI functionality as an earnings catalyst until Sonos discloses adoption, engagement or monetization metrics. A fall rollout that is delayed, gated behind hardware upgrades, or increases cloud/support expense would undermine the implied platform-margin thesis.
- Monitor holiday promotions from Apple, Bose, Sony, Samsung and LG. Broad premium-audio discounting would signal that Sonos must trade price for volume, reducing the probability that new products translate into near-term gross-margin expansion.
More News
- Asian stocks dip, bonds in focus after torrid September
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- California Gov. Gavin Newsom bans AI 'robo bosses' in landmark state law, reversing his earlier veto
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Why is Nidec stock plunging today?
- Why is Kioxia stock rallying today?