
METLEN and PETRONAS enter into LNG Supply Agreement to strengthen energy security and diversification in Southeast Europe
Source: PR Newswire
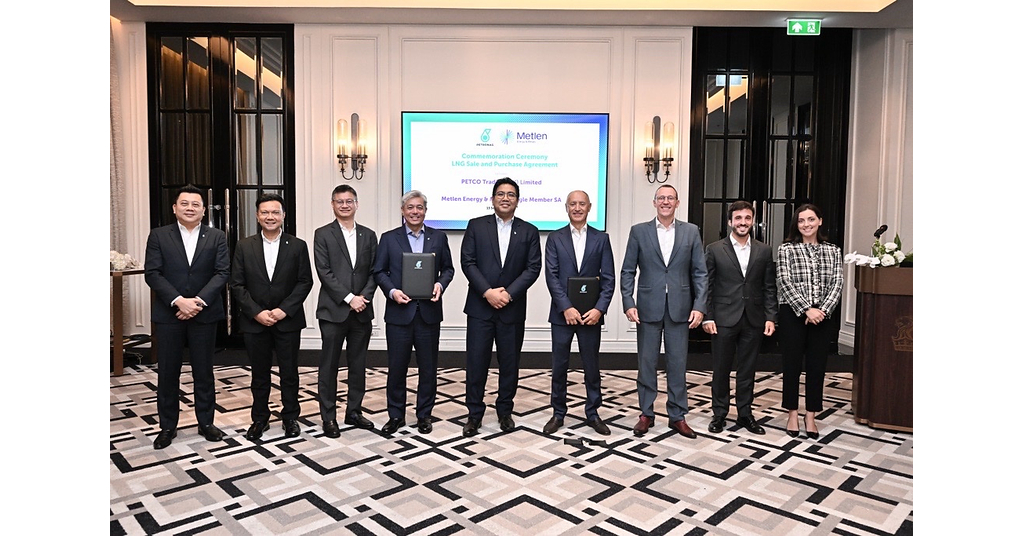
METLEN and PETRONAS signed a five-year LNG supply agreement under which PETRONAS will deliver six cargoes annually, totaling approximately 0.6 bcm per year, to Greece beginning in 2027. The deal diversifies METLEN's LNG sourcing and is intended to improve supply resilience and liquidity across Greece and Southeast Europe, while expanding PETRONAS' LNG presence in European and Mediterranean markets. The agreement is strategically positive for the companies' regional gas-trading positions, though its volume is unlikely to materially move the broader European LNG market.
Analysis
The financial significance is likely modest relative to METLEN’s existing energy platform; the investable value is not incremental gas volume but reduced procurement concentration and greater ability to arbitrage delivered LNG against TTF and regional power prices. If the contracted pricing is indexed favorably versus spot—an undisclosed and decisive variable—the agreement can lower working-capital volatility and protect generation/trading margins during winter dislocations, supporting a modest rerating of the utility segment rather than a near-term EBITDA step-change.
The second-order benefit is strategic: dependable Atlantic-basin supply improves METLEN’s ability to serve Balkan counterparties when pipeline flows or Black Sea logistics are disrupted, potentially increasing utilization and liquidity at Greek import infrastructure. Conversely, this adds limited value in an oversupplied global LNG market, where spot cargoes remain readily available and fixed contractual commitments can become a margin drag. With leverage already meaningful for a diversified industrial group, investors should watch whether incremental supply contracts are matched by customer offtake rather than becoming another source of commodity working-capital needs.
Near term, MTLN may receive a sentiment lift but the release alone does not justify a major estimate revision. Over the next 1-3 months, the key catalyst is disclosure of indexation, destination flexibility, and whether METLEN secures downstream sales into Southeast Europe; over 6-18 months, sustained regional TTF premiums and winter price volatility would demonstrate the value of portfolio optionality. The thesis is falsified if energy-segment margins fail to improve despite higher gas trading volumes, net-debt/EBITDA rises above management’s comfort range, or European LNG oversupply compresses regional basis spreads.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- Maintain MTLN as a watch-list long rather than chase a press-release move; initiate only if management quantifies margin/working-capital economics or if shares underperform European utility peers by 5-10% without an earnings-guide reduction. Target a 6-12 month rerating tied to energy-trading resilience; exit if net leverage trends materially above 3.5x or energy EBITDA guidance is cut.
- Monitor winter 2026/27 Greek and Southeast European gas-to-TTF basis and regional power spreads as the operational validation signal. A sustained premium during supply stress would support adding MTLN; narrow or negative basis alongside ample LNG inventories argues that the contract is strategically useful but financially immaterial.
- Avoid treating MSCI, LSEG, and NGS as read-through beneficiaries: none has a direct earnings linkage to this procurement arrangement. PETRONAS is not a readily accessible listed-equity expression, so there is no clean counterparty trade from this announcement.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns