
DJI lancia Osmo 360 II a IFA 2026, offrendo un imaging di punta a 360° in 8K per riprese epiche, di giorno o di notte
Source: PR Newswire
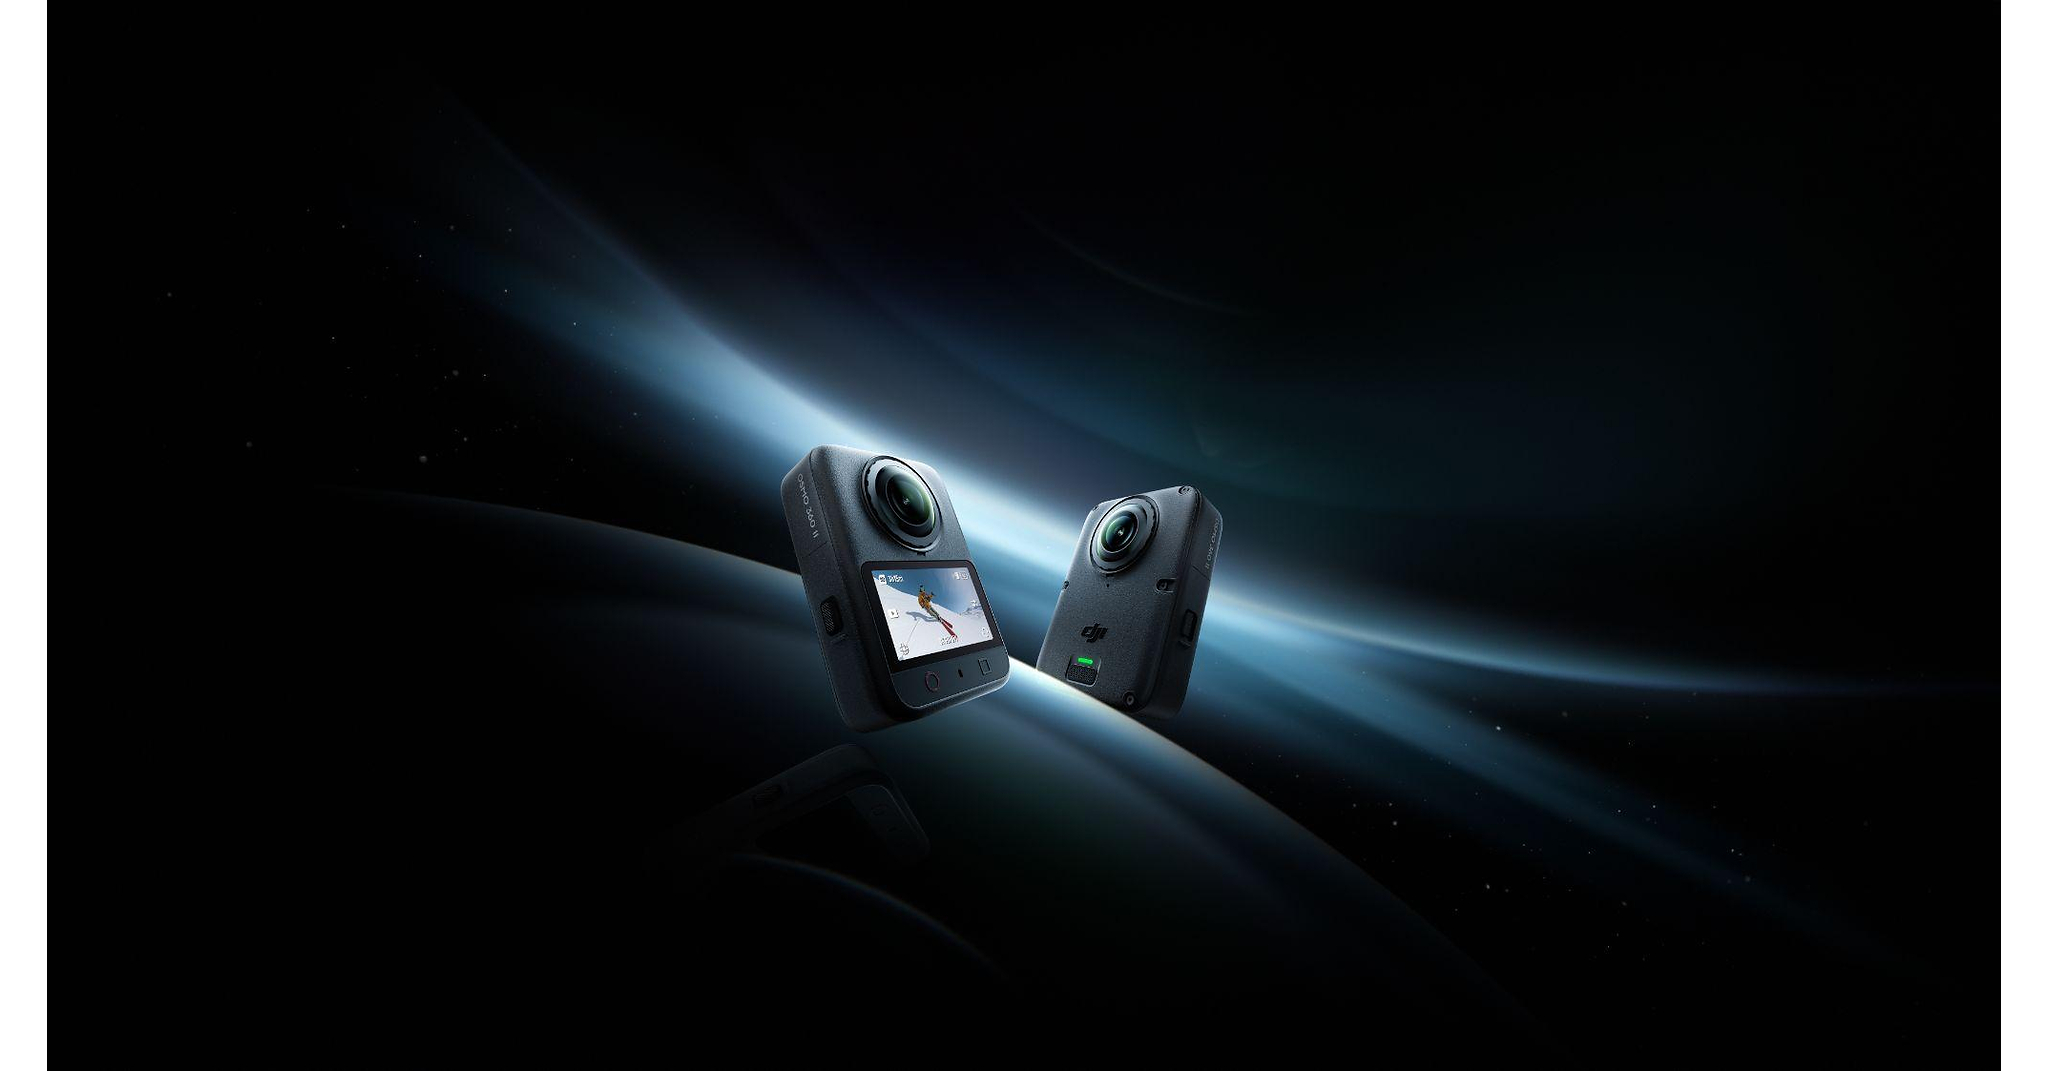
DJI lancia Osmo 360 II a IFA 2026 con sensore HDR da 1 pollice e riprese panoramiche 360° fino a 8K/60fps, con gamma dinamica fino a 14,5 stop e riduzione del rumore AI SuperNight 2.0 per scarsa illuminazione. La camera integra 105 GB di memoria, pesa 183 g e registra fino a 100 minuti (8K/30fps), con ricarica rapida all’80% in 22 minuti, oltre a obiettivi ultra-resistenti sostituibili. In Italia i prezzi partono da 589€ (Combo Standard) e 749€ (Combo Adventure).
Analysis
This is a product-cycle event, not a fundamental re-rating catalyst for DELL. The economic value sits in ecosystem lock-in, accessories, and workflow software, while the camera body itself is likely to face fast commoditization and discounting once competitors match spec headlines. For public equities, the cleaner read-through is pressure on premium action/360 incumbents rather than a broad consumer-electronics upswing.
The most exposed loser is GPRO: when the category leader is pushing higher-spec 360 capture, it raises the bar on image quality and post-production simplicity, which is where legacy action-cam brands are weakest. That said, the real share shift will show up in channel inventory and holiday sell-through over the next 1-2 quarters, not immediately on launch day. A secondary beneficiary could be high-end creator computing/storage, but for DELL that upside is diffuse and likely immaterial unless workstation demand or attach rates inflect in upcoming prints.
Contrarian view: the market may overestimate how much launch specs translate into durable margin expansion. If consumers care more about durability, software, and service than sensor claims, the winner is whoever monetizes accessories and protection plans, not the box price. Falsifier for the bearish read on GPRO is a stable ASP/cash conversion trend into year-end; for DELL, the thesis is invalidated only if next 1-2 quarters show a measurable uptick in creator/workstation orders, which currently looks unlikely.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Stay neutral DELL; do not buy the stock on this release alone. Revisit only if the next 1-2 quarters show a clear lift in workstation/creator PC orders or storage attach; otherwise the read-through is too small to matter.
- Set a 4-8 week watch on GPRO channel checks and holiday promo pricing. If sell-through weakens or discounting appears, consider a short GPRO / long cash trade with a 1-3 month horizon.
- Do not express the thesis via DELL options; implied move from this news is likely overstated versus the negligible fundamental impact. Use it as a monitoring item, not a catalyst trade.
More News
- Nike's S&P Exit Is a Warning for Every Consumer Brand
- Bessent says US needs more open-source AI models to compete with China
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Two camps have emerged in the debate over AI safety and regulation
- Push for AI regulation mounts as talk of AI’s ‘existential’ risks go mainstream. But Trump resists calls for a slowdown
- Urgent calls from OpenAI, Anthropic for an AI slowdown fall on deaf ears with Trump, Xi ahead of next week’s meeting