
China’s Energy Buffer Faces Winter Test as Coal Production Falters
Source: Bloomberg
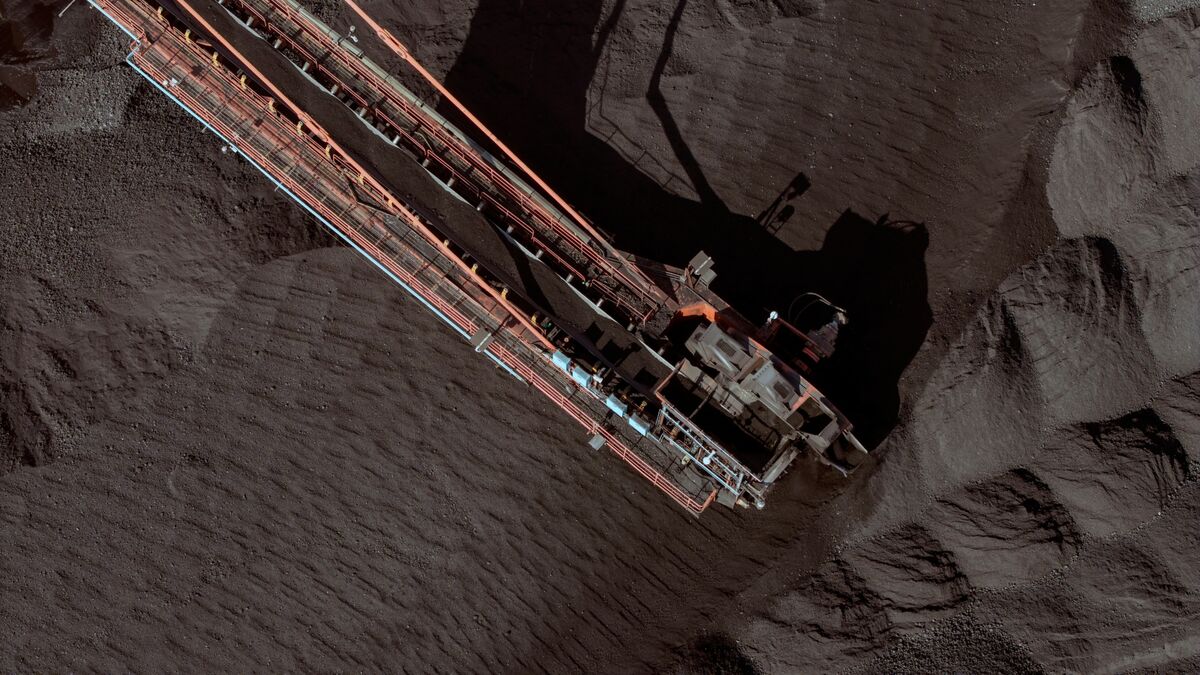
China’s coal and gas production is faltering as winter heating demand begins, raising the risk that the country’s energy reserves will erode. Stockpiles are currently ample, but the article provides no figures on production declines or reserve levels.
Analysis
The key market mechanism is not a confirmed shortage but a possible shift from domestic supply to seaborne imports. If production remains weak as heating demand rises, China may need to draw inventories faster or bid for imported thermal coal and LNG, tightening Asian prompt balances and supporting benchmark prices and freight. That would favor seaborne suppliers, while raising input-cost risk for utilities and energy-intensive industry where fuel costs cannot be passed through quickly.
The buffer matters: ample stocks can absorb a temporary production dip, so the article alone does not establish an import surge or justify chasing energy prices. In the next few weeks, watch inventory draw rates, mine output and import bookings; over 1–3 months, the catalyst is whether those indicators confirm persistent winter tightness. Over 6–18 months, sustained import dependence could make Asian prices more sensitive to Chinese procurement, but policy-directed output increases or demand restraint could reverse that effect.
Contrarian risk: markets may overread a production slowdown while underweighting inventories and the state’s ability to intervene. No company-level earnings conclusion is supportable from the supplied information. Verify the pace and scope of the production decline, stockpile coverage, import data, and whether utility fuel costs are being passed through before taking equity exposure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Key Decisions for Investors
- No immediate directional trade on this evidence alone. Treat it as a watch item rather than a confirmed supply shock; ample inventories are a meaningful near-term cushion.
- Conditional trade: consider a risk-defined long in seaborne thermal coal exposure, such as Newcastle coal futures, only if Chinese inventory draws accelerate and import bookings or benchmark prices confirm tightening. Exit or avoid adding if inventories stabilize, domestic output recovers, or import demand fails to rise.
- Monitor Asian spot LNG and shipping rates as secondary beneficiaries if gas production weakness translates into incremental winter buying; avoid assuming coal and gas imports will both rise without procurement data.
- For equity risk, favor exporters only after confirming realized-price sensitivity and shipment exposure; be cautious on utilities and energy-intensive producers if fuel costs rise faster than regulated tariffs or product prices. Reassess on inventory releases, import data, and any policy-driven mine-output response.
More News
- Copper Holds Drop as Traders Gauge Risks From US Tariff Policy
- Saudi Arabia cancels 2026 ‘Davos in the Desert’ amid Houthi attacks
- French unrest compounds debt crisis fears. Paris-listed stocks, bonds and the euro fall
- BlackRock, Allianz Join Jio’s $854 Million IPO Anchor Order Book
- ’Panic’ selling hits Indonesian markets on MSCI expulsion threat
- Qatar warns global energy shockwaves from Iran war have yet to peak