
Buy this stock that offers discounted exposure to SpaceX, Morgan Stanley says
Source: CNBC
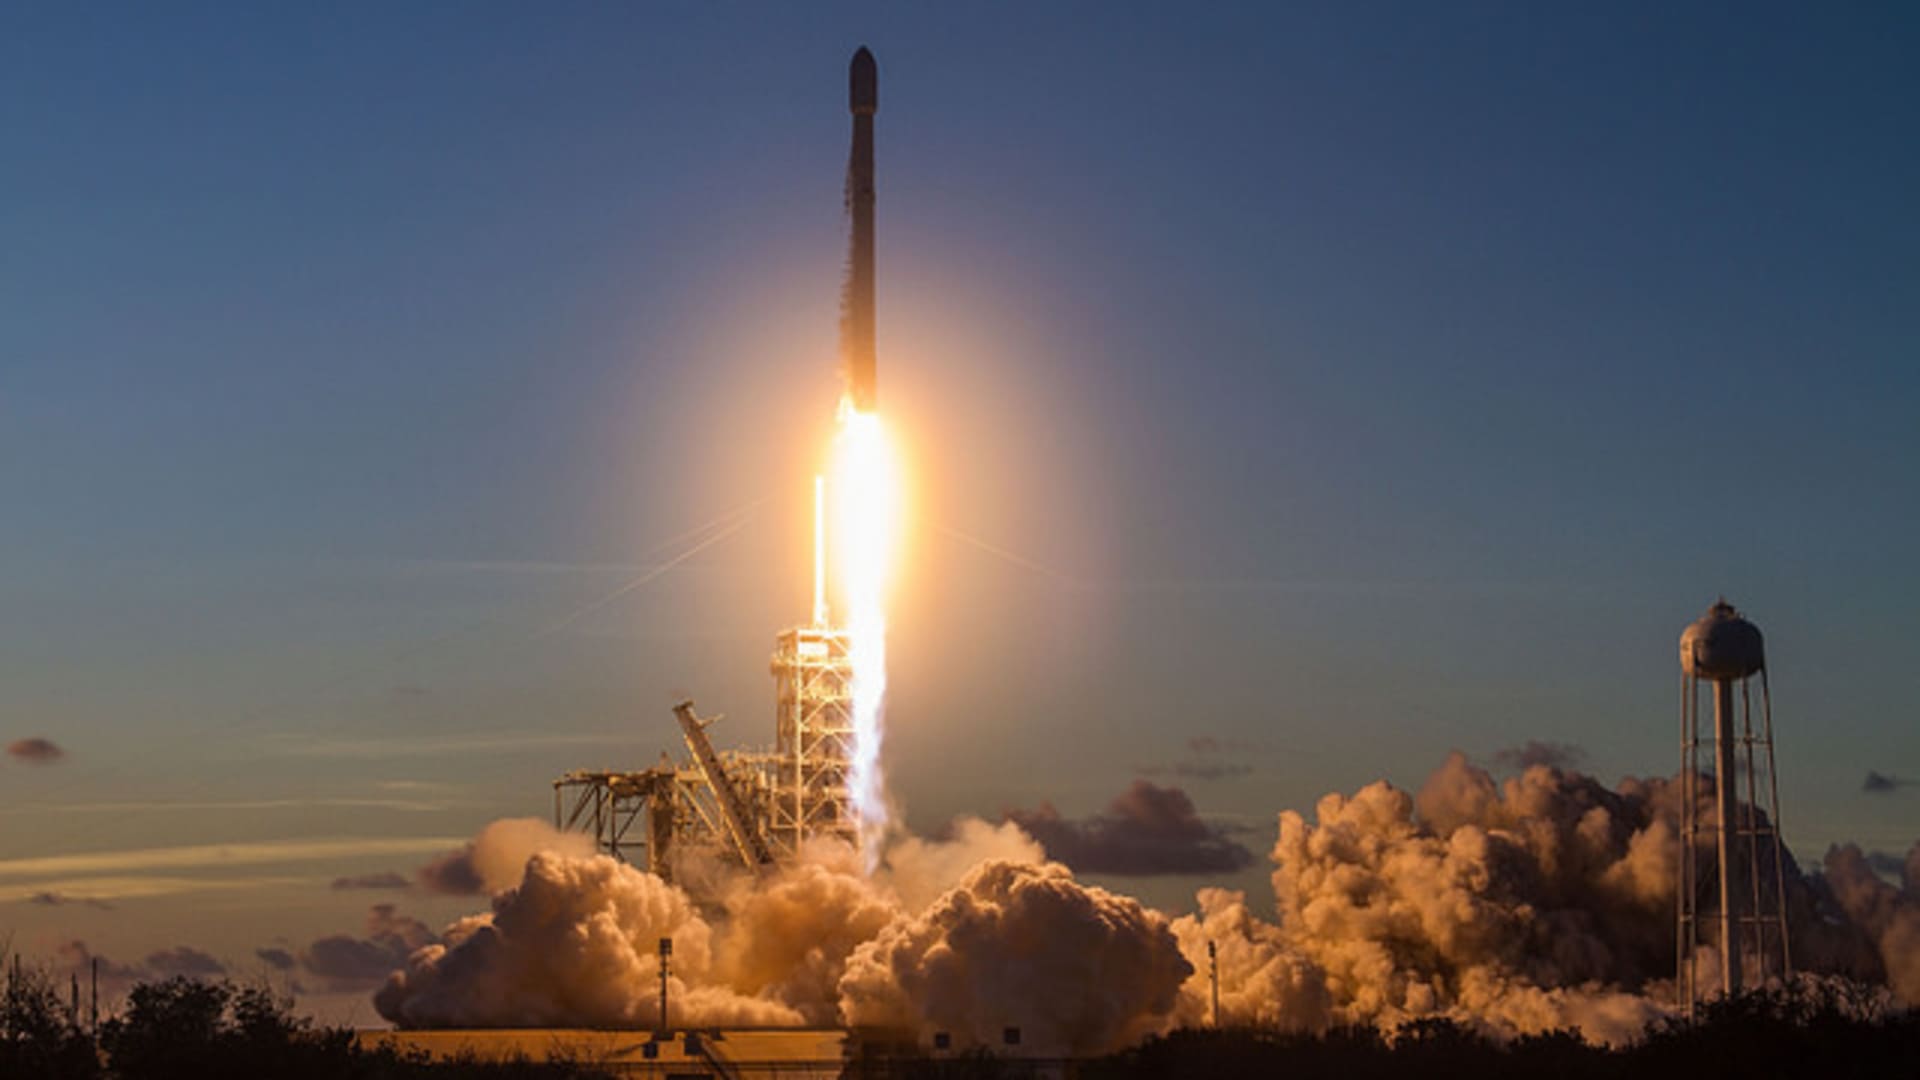
Morgan Stanley initiated EchoStar at overweight with a $134 price target, implying nearly 44% upside from Friday's close, arguing that the market discount to its SpaceX-linked spectrum value is excessively wide. EchoStar's roughly $17B spectrum-license agreement with SpaceX provides exposure to Starlink and Boost Mobile, while the stock has traded with a 0.66 daily-return correlation to SpaceX since its June IPO. The firm also cites optionality from a potential Dish/Sling TV combination with DirecTV, though it flags bankruptcy-related asset complexity and EchoStar's credit-like equity profile as risks.
Analysis
ECHO is best viewed as a leveraged asset-value and credit re-rating rather than a clean SpaceX proxy. The equity can outperform if investors begin capitalizing contracted spectrum economics and simplifying the holding-company discount, but its sensitivity to SPCX is likely unstable: a rising SPCX valuation helps NAV, while a risk-off move can widen ECHO's discount because of leverage, structural complexity and residual operating liabilities. The key diligence item is the timing, security and indexation of spectrum-related cash flows versus ECHO's debt maturities; without that, headline NAV discounts are not investable.
Near term, the upgraded coverage may pull ECHO toward the roughly $100 psychological level, but broad bullish sell-side positioning limits incremental-rating catalyst value. Over 1-3 months, disclosures around spectrum monetization, liability reduction, or a transaction involving the video assets could force a sum-of-the-parts re-rating. Over 6-18 months, scarcity value depends on whether satellite-to-device service proves commercially scalable without meaningful capacity constraints or regulatory concessions; if it does, terrestrial wireless incumbents face a more credible low-end and rural coverage competitor.
The contrarian opportunity is that ECHO's discount may be compensation for duration and credit subordination, not merely analytical complexity. A structurally bullish SPCX investor should therefore hedge market-beta exposure rather than assume ECHO will track it one-for-one; the trade only works if ECHO's NAV discount narrows. Thesis failure would be a weaker-than-expected contractual cash-flow disclosure, debt-spread widening, adverse spectrum/regulatory developments, or ECHO breaking materially below the pre-upgrade area despite a stable SPCX valuation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Initiate a starter long ECHO below $100, sized as a special-situations credit-equity exposure rather than a core technology position. Target $125-$134 over 3-6 months on discount compression; reassess if shares fall 15% from entry while SPCX is flat-to-up, which would signal idiosyncratic balance-sheet concern.
- For investors seeking SpaceX exposure, use a paired position: long ECHO and short a calibrated SPCX exposure or broad high-beta technology proxy, rebalanced to ECHO's realized beta. This isolates the NAV-discount catalyst; avoid the pair until updated debt-maturity and spectrum-payment details confirm that ECHO's equity is not absorbing refinancing risk.
- Monitor ECHO credit spreads and any maturity-extension or asset-sale disclosures as the highest-value catalyst indicators over the next two quarters. A sustained tightening in spreads should precede equity re-rating; widening spreads would favor standing aside even if analyst price targets rise.
- Do not underwrite a DirecTV/video-asset transaction into base case. Treat a definitive transaction with clearly quantified cash proceeds and liability transfer as upside optionality, because an equity-funded or highly contingent structure could preserve the conglomerate discount rather than eliminate it.
More News
- ‘Crazy days’ and ‘silly season’ in the stock market raise the prospect of a ‘late-stage’ AI bubble finally popping
- AI doomsday fears are arriving at the worst possible time for the stock market
- ‘Silent Cold War’: Why calls to slow AI have sparked new US–China frontier
- Space startups raise big money in funding blitz as Europe aims to challenge U.S. dominance
- Trump blasts Anthropic CEO Dario Amodei over AI warning: ‘SICK conspiracy'
- Why CrowdStrike Stock Rocketed Higher Today