
Reins launches Valuation to help contractors know and grow their business value
Source: PR Newswire
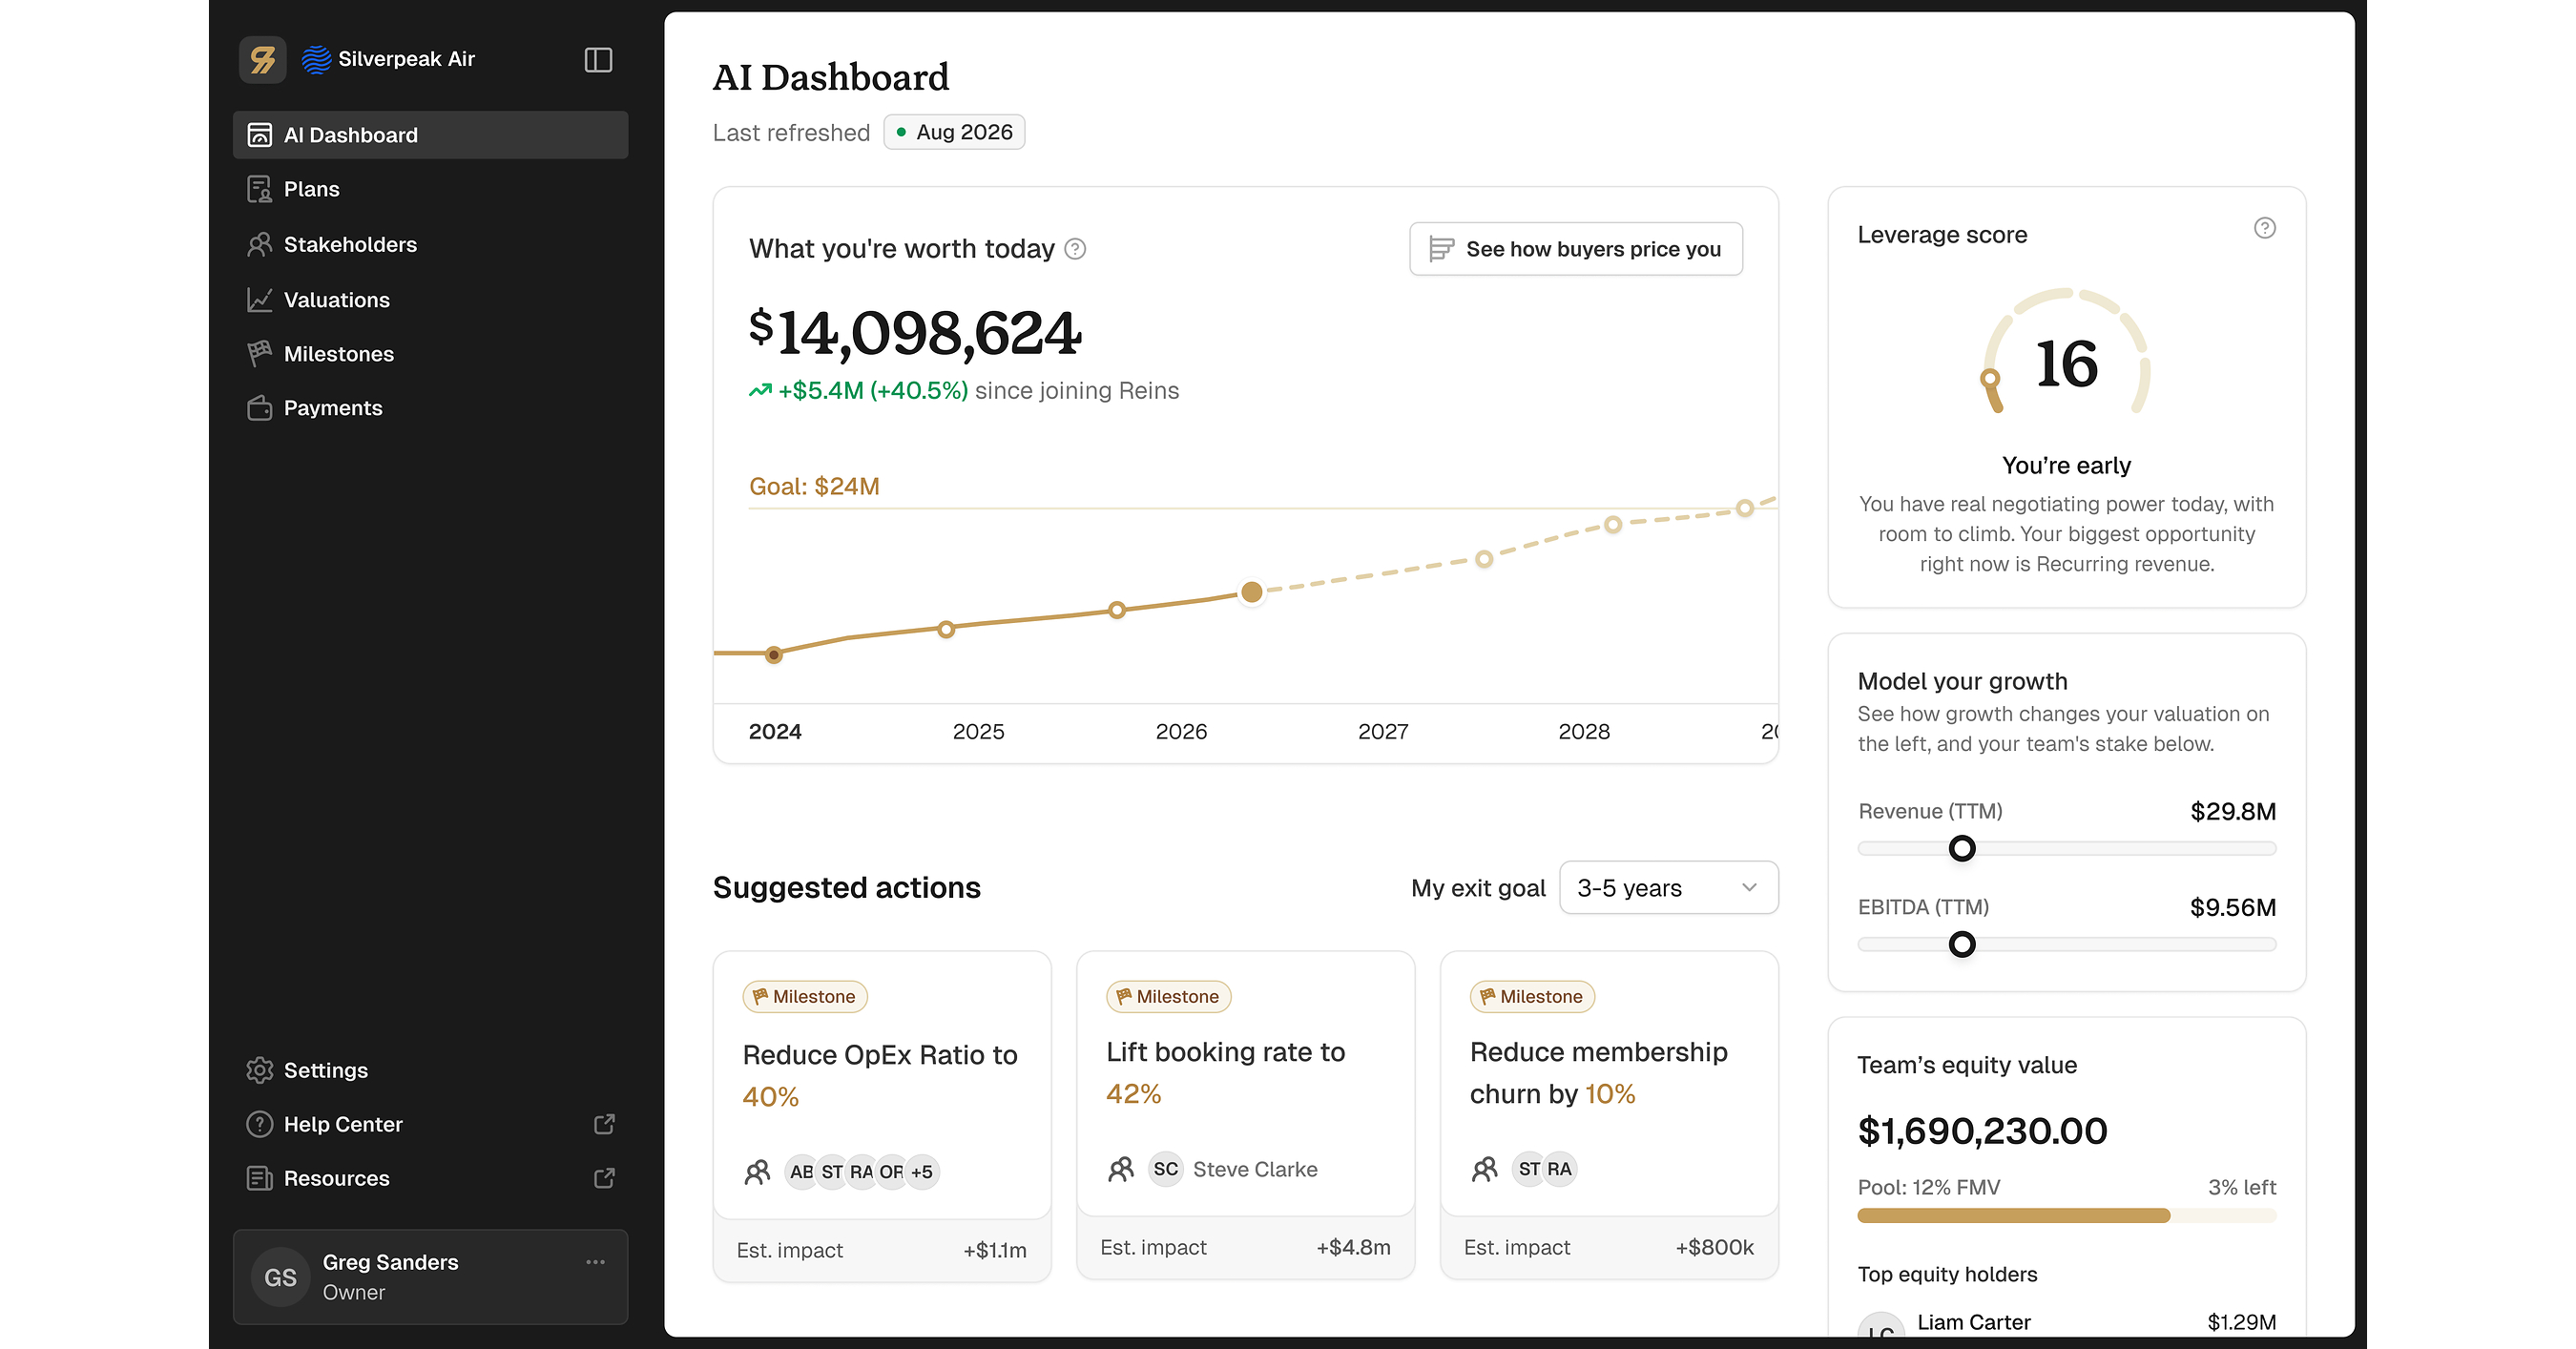
Reins launched Valuation, an AI-powered standalone product that uses contractors' financial and operating data, including QuickBooks and ServiceTitan inputs, to estimate business value, benchmark performance and identify improvement levers. The product integrates with Reins' Incentives platform for phantom stock, stock-appreciation rights and profit-sharing plans; Reins says hundreds of trade-business owners have granted more than $50 million in employee incentives through its platform. The privately backed company has raised $5.5 million to date from Album, Better Tomorrow Ventures, Torch Capital and Animo Ventures.
Analysis
This is not a public-equity catalyst for TTAN absent evidence that it owns, distributes, or materially partners with Reins; the neutral ticker signal is appropriate. The relevant investable read-through is that AI valuation and incentive tooling lowers the cost of professionalizing fragmented trade businesses, potentially increasing the addressable customer base for vertical SaaS systems such as ServiceTitan (private), Intuit (INTU), and Procore (PCOR), rather than creating near-term revenue for a small, privately funded vendor.
The second-order effect is likely stronger M&A readiness among subscale HVAC, plumbing, electrical, and restoration operators. Cleaner financial data, peer benchmarking, and retention plans can reduce key-person risk and improve transaction-quality metrics, supporting continued private-equity roll-up activity; over 6-18 months, that favors workflow and payments platforms embedded in contractors' systems of record. It could marginally pressure traditional valuation consultants and broker intermediaries, but only if Reins can demonstrate lender, buyer, or auditor acceptance of its outputs rather than merely generate owner-facing estimates.
Consensus should not extrapolate the "AI agent" framing into immediate software-disruption economics. Valuation accuracy depends on normalized EBITDA, customer concentration, backlog quality, fleet/capex needs, and local-market multiples—inputs that are often incomplete in small-business accounting records. A weak macro environment or higher financing costs could improve adoption interest while simultaneously compressing exit multiples, making the product's claimed value-creation ROI harder to prove.
Near term, monitor whether Reins discloses paid-seat growth, ServiceTitan/QuickBooks integration depth, retention, and conversion from valuation users into incentive-plan customers. The thesis becomes investable only if adoption creates measurable incremental payments, payroll, financing, or core-workflow spend at a public platform; without those data, this is a private-market watch item, not a directional trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No position in TTAN based on this release. Reassess only upon verification of a commercial relationship, ownership linkage, or a disclosed revenue exposure; absent that, the announcement has no identifiable earnings pathway.
- Place INTU and PCOR on a 6-18 month watchlist as public proxies for contractor digitization and financial-data normalization. Consider longs only after evidence of accelerating small-business subscription, payments, or construction/trades customer metrics; invalidate if SMB churn rises or contractor end-market demand weakens.
- Monitor ServiceTitan's eventual public-market filings or financing disclosures for attach rates in analytics, benchmarking, compensation, and payments. A demonstrated cross-sell from operational data into valuation/retention tools would support a higher recurring-revenue multiple, but there is insufficient information for a trade today.
- For private-market diligence, track trade-services acquisition multiples and debt spreads over the next 1-3 months. If financing spreads widen or sponsor deal volume contracts, software-enabled "exit readiness" may see engagement growth but weaker customer willingness to pay for premium advisory modules.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- The UK cuts energy bills, taxes banks and boosts defense in high-stakes budget
- Microsoft's Big Bets on AI Start to Pay Off
- Asian shares fall as Alphabet earnings miss drags Wall St futures lower