
Streamside RV Resorts & Campgrounds Acquires Bay Point Landing, Marking First Pacific Northwest Property
Source: PR Newswire
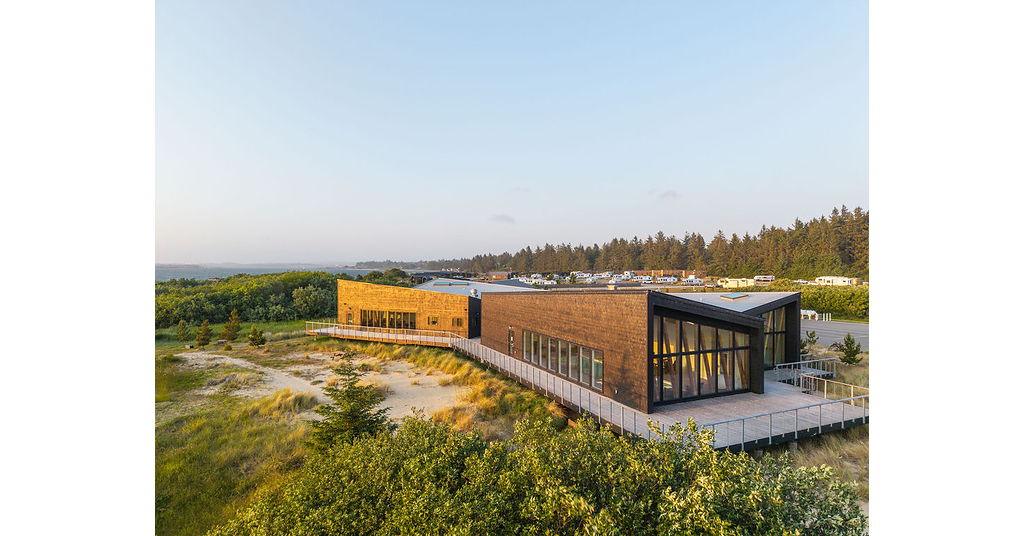
Streamside RV Resorts & Campgrounds acquired Bay Point Landing in Coos Bay, Oregon, marking its 41st property and first Pacific Northwest/coastal acquisition. The 103-acre waterfront resort includes 125 RV sites, 32 cabins and 14 rentable Airstreams, expanding Streamside's portfolio to more than 4,774 RV and lodging sites across 18 states. Financial terms were not disclosed; Streamside plans targeted infrastructure investments while maintaining operations, employee support and existing reservations.
Analysis
This is a private-market transaction with no direct listed-equity read-through and insufficient disclosed consideration, financing, historical occupancy, or property-level NOI to assess whether the buyer is creating value or merely adding unit count. The relevant mechanism is consolidation: a scaled operator can centralize marketing, revenue management, procurement, and seasonal staffing, but a single destination property is unlikely to move industry economics absent evidence that acquisition multiples are falling or that financing remains readily available.
For public markets, the closest read-through is modestly constructive for premium, experience-led lodging demand rather than broad RV demand. PEJ and PK could benefit only if upscale leisure pricing and destination occupancy prove resilient into the next booking season; conversely, lower-income discretionary travel remains more exposed to fuel prices and consumer-credit deterioration. The Oregon coastal location also carries weather, wildfire, insurance, and permitting risk, making incremental capex potentially dilutive if rate growth does not offset higher maintenance and insurance costs.
Over the next 1-3 months, treat this as a data point to monitor private-market cap rates and transaction financing rather than a catalyst. Over 6-18 months, repeated acquisitions by scaled operators would tighten the supply of institutionally investable outdoor-hospitality assets, potentially supporting private valuations but not necessarily public REIT multiples, which remain more rate-sensitive. A contrary interpretation is that highly designed, small-footprint assets can command premium ADR but have limited operating leverage; any reported growth in portfolio size should not be extrapolated into proportional EBITDA growth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- No standalone trade: there is no public acquirer, disclosed price, financing structure, or NOI, so the announcement does not establish an investable valuation signal.
- Add a watch item on private outdoor-hospitality transaction cap rates, debt coupons, and same-property ADR/occupancy through the 2027 booking season; a sustained decline in cap rates alongside stable occupancy would be constructive for institutional lodging real estate.
- For listed leisure exposure, maintain preference for asset-light operators over highly leveraged real-estate owners until long-end yields and commercial-property financing spreads decline; reassess if 10-year Treasury yields fall materially while leisure RevPAR guidance is raised.
- Monitor CWH and THO as higher-beta RV-demand proxies, but do not infer demand acceleration from premium destination lodging. A weakening used-RV pricing trend, rising delinquencies, or reduced dealer orders would falsify any broader RV-sector read-through.
More News
- Australia’s central bank chief warns inflation risks materialising
- California AG Says Paramount-WBD Merger Would Hurt the State
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- California AG Bonta on Paramount-Warner Bros., Meta and AI
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”