
Ben E. Keith Company Awards Hormel Foods Supplier of the Year
Source: PR Newswire
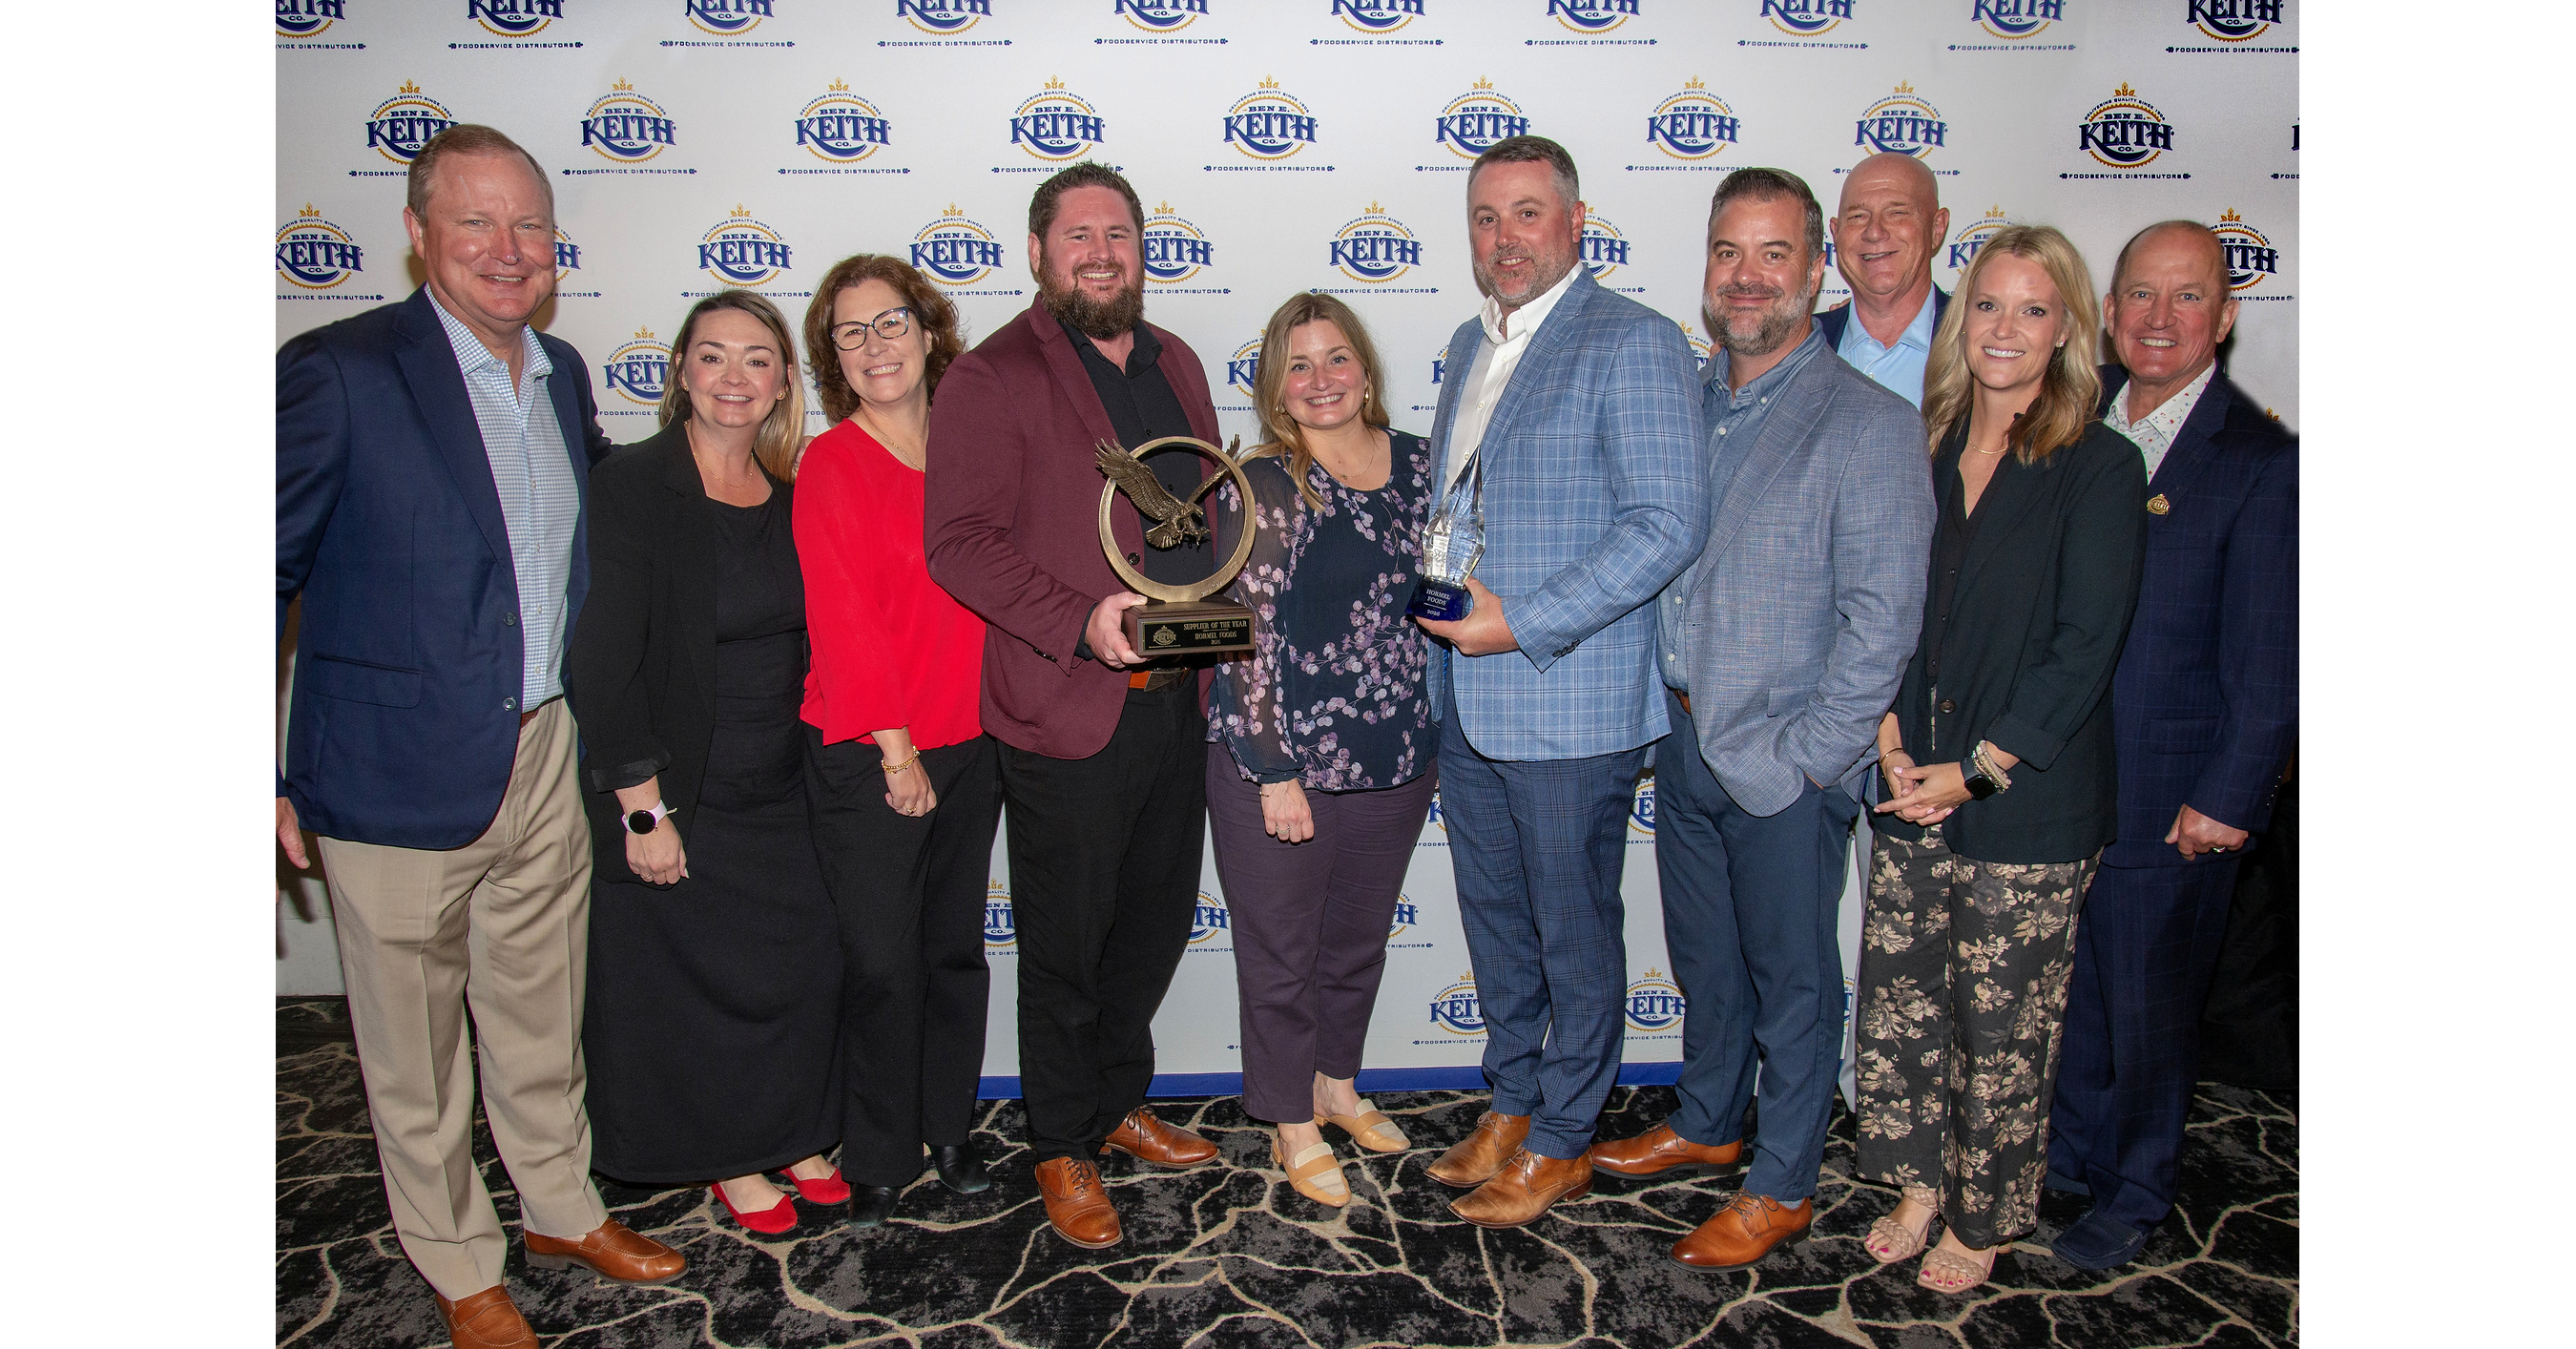
Hormel Foods was named Ben E. Keith Foods' 2026 Supplier of the Year at the distributor's 43rd annual Supplier Appreciation Day on October 5 in Fort Worth. Ben E. Keith cited Hormel's long-standing partnership, collaboration, trusted brands and consistent value across its 10 divisions; the announcement provided no financial figures or market reaction.
Analysis
This is a relationship-quality signal, not evidence of incremental revenue, share gains, or improved economics for HRL. The potential upside is modest: closer coordination with a large foodservice distributor could support placement, menu adoption, and retention across its divisions, especially in center-of-the-plate products. Those benefits accrue only if they translate into measurable volume or mix; distributor recognition alone does not establish exclusivity or pricing power. Near term, the announcement is unlikely to change earnings expectations. Over 1–3 months, watch HRL’s foodservice volume, category mix, and management commentary for evidence of account-level momentum. Over 6–18 months, sustained distribution wins could matter, but a broadline partner’s scale can also increase buyer leverage and pressure supplier pricing. The contrarian read is that the award may reflect service and relationship strength while masking ordinary, or even price-competitive, economics. No trade is warranted on this announcement alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Do not trade HRL on the award; treat it as a low-signal qualitative datapoint rather than an earnings catalyst.
- Monitor HRL foodservice volume and mix, plus any disclosure of distribution breadth, new placements, or contract terms. Without those data, do not attribute incremental sales to this relationship.
- Reassess the thesis if upcoming results show sustained foodservice volume or mix improvement; falsification would be continued weakness or guidance that indicates no meaningful channel contribution.
- If HRL rallies materially on this announcement without supporting operating evidence, view the move as vulnerable to reversal rather than as confirmation of durable pricing power.
More News
- A 32% beat, a +6% jump: the IT solutions name our models picked in July
- GIC Private Ltd, Medline 10% owner, sells over $721m in shares
- Nvidia Is on the Verge of a $6 Trillion Market Value
- Controversial $110 billion mega-merger of Paramount and Warner Bros. finally closes
- What Marvell's rosy long-term guidance means for our AI chip stocks
- Meta may ditch the idea of a cloud business for Muse. We think that’s a good trade