
Can Boot Barn's Supply Chain Efficiencies Expand Merchandise Margins?
Source: zacks.com
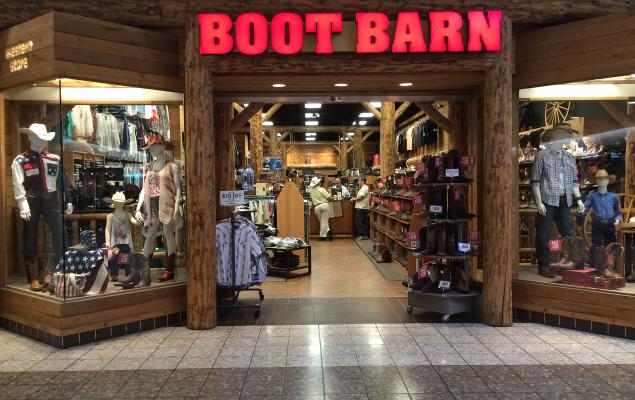
Boot Barn expects fiscal 2027 merchandise margin of approximately 52.2% of sales, up 130bps year over year, including a 70bps benefit from tariff refunds. First-quarter fiscal 2027 merchandise margin rose 220bps, supported by tariff refunds, product-margin gains, vendor volume discounts, lower logistics rates and store-based e-commerce fulfillment. Consensus forecasts earnings growth of 23.5% in the current fiscal year and 10.3% next year, though BOOT shares remain down 23.7% over the past six months.
Analysis
The investable issue is earnings quality, not the reported margin target. A meaningful portion of the near-term expansion is non-recurring tariff-refund income; excluding it, the implied underlying gain is modest and vulnerable to promotional intensity, mix, and freight-rate normalization. Because BOOT’s earnings expectations already embed strong growth, a miss on comp sales or inventory turns could overwhelm a small gross-margin beat and keep the multiple discounted.
Scale-based purchasing and store-fulfilled digital orders create a real structural advantage versus smaller western-workwear independents: better vendor terms can reinforce price/assortment advantages while distributed inventory reduces markdown and parcel-cost leakage. The second-order constraint is that full-container purchasing raises fashion and regional-demand forecasting risk; if demand softens, the same strategy can elevate aged inventory and markdowns. This matters most over the next 6-18 months as the store base expands and inventory becomes less flexible.
Consensus may be treating the recent share weakness as a straightforward margin-recovery entry point. The contrarian view is that tariff refunds mask the recurring run-rate, while a more favorable setup emerges only if management demonstrates that full-price sell-through and inventory turnover improve simultaneously. URBN is a cleaner relative long within specialty retail if its category momentum persists, while FIGS has a different demand driver and should not be used as a direct read-through for BOOT.
Near-term catalyst: the next earnings release must validate underlying product margin, inventory growth versus sales, and comp-store demand. Falsify a cautious view if BOOT sustains ex-refund merchandise-margin expansion above 75 bps while inventory growth remains below sales growth and guidance is raised; conversely, a comp miss paired with higher markdown reserves would challenge the margin narrative within one to two quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Maintain BOOT as watch-list/market-weight rather than add on margin guidance alone; reassess after the next earnings release using ex-refund gross margin, comparable sales, and inventory growth as gating data.
- If BOOT reports ex-refund margin expansion above 75 bps, inventory growth below revenue growth, and raises full-year EPS guidance, initiate a 3-6 month long with a 10-15% upside target; exit on a comp-sales miss or evidence of rising markdowns.
- For specialty-retail exposure over the next 1-3 months, prefer a relative long URBN / short BOOT pair in equal dollar amounts: URBN has less dependence on a one-time margin bridge, while BOOT is more exposed to discretionary western-footwear demand and inventory execution. Cover if BOOT’s underlying margin exceeds 75 bps for two consecutive quarters.
- Do not treat FIGS or FOSL as direct sympathy trades. FIGS’s earnings path is driven by healthcare-apparel penetration and DTC efficiency, while FOSL’s balance-sheet and brand-relevance risks dominate any logistics-cost benefit.
More News
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- South Korean corporate reforms hit rough patch as Samsung digs in
- AI boom turns chip packaging into the next battleground for semiconductors
- Nvidia H200 chips pile up in Hong Kong as Beijing holds back, Reuters says
- Why is SPDR S&P 500 ETF Trust sliding today?
- IonQ climbs 3% on earnings beat and raised guidance