
Brazil Confronts the End of the Lula Era as President Vote Goes to Second Round
Source: Bloomberg
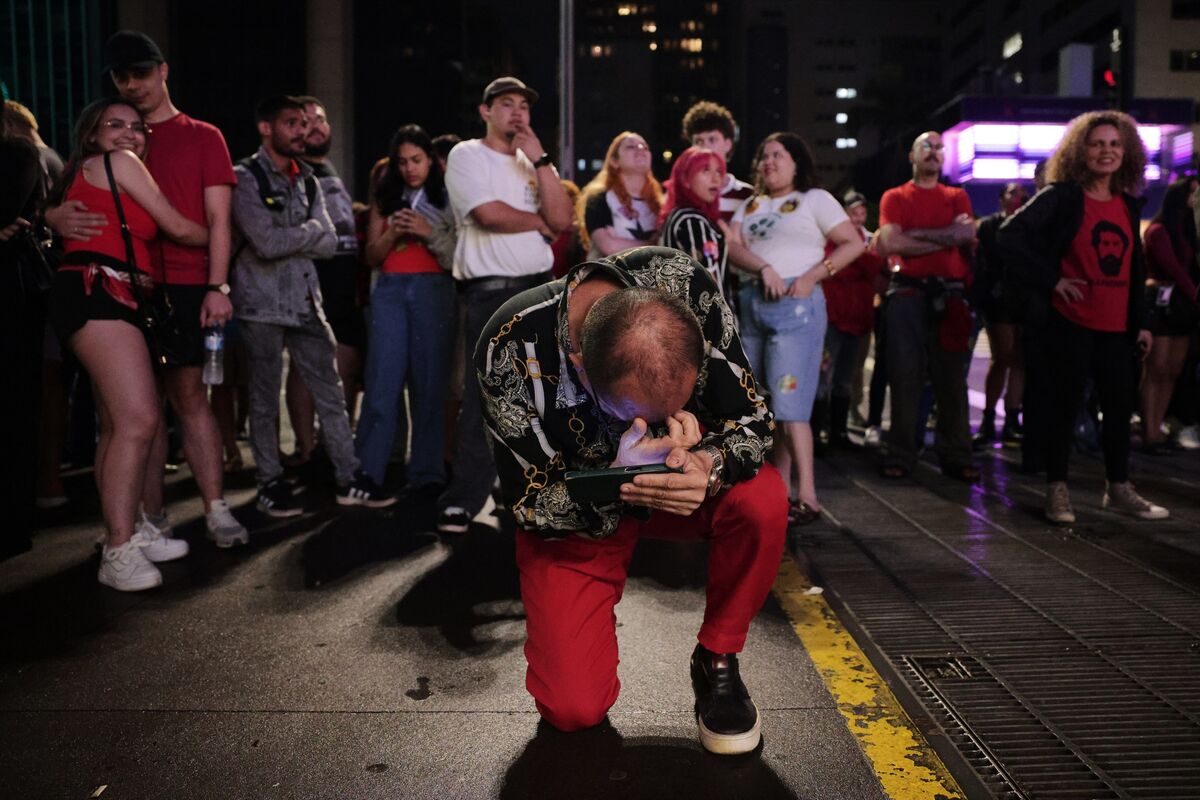
The article frames Brazil’s election as a challenge for President Luiz Inácio Lula da Silva, saying voter rejection was high for both candidates but that the numbers were stacked against Lula. The excerpt provides no polling figures, election result, or market reaction.
Analysis
The investable signal is a wider Brazilian political-risk distribution, not evidence of a settled policy regime. High rejection on both sides can weaken a winner’s mandate and raise the odds of coalition bargaining, policy dilution, or abrupt attempts to shore up support. That uncertainty can be priced before any measurable change in fiscal outcomes: first through BRL and local rates, then through the equity risk premium if fiscal credibility or central-bank independence becomes contested.
Near term, headline-driven FX and rates volatility is more defensible than a broad equity direction. Over 1–3 months, the key catalysts are credible polling, candidate platforms, coalition signals, and any change in fiscal commitments; over 6–18 months, execution and institutional checks matter more than campaign rhetoric. Dollar earners and commodity exporters may be relatively insulated from domestic-demand weakness, while rate-sensitive and domestically exposed assets could lag if the risk premium rises. That is a conditional exposure map, not a company-level earnings call.
Contrarian point: voter rejection can constrain either candidate and make a sharp policy break harder, so treating the headline as an automatic bearish Brazil signal risks overpricing political risk. The article supplies no polling series, opponent identity, policy proposals, or market pricing; there is not enough evidence for an outright directional position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Key Decisions for Investors
- Do not add broad Brazil risk on this article alone. For existing Brazil equity exposure, consider a limited, defined-risk hedge using EWZ puts or put spreads only if implied volatility and hedge cost are acceptable; avoid paying up for event protection without a dated catalyst.
- Treat a short-BRL / long-USD expression as a conditional alert, not an immediate recommendation: reconsider if polling or campaign commitments point to weaker fiscal credibility and BRL underperforms comparable emerging-market currencies. Invalidate on improving fiscal signals or broad USD weakness that explains the move better.
- Monitor local long-end yields, BRL performance versus EM peers, and candidate fiscal proposals. A persistent rise in local term premium alongside currency weakness would strengthen the risk-premium thesis; stable rates and a resilient currency would argue against it.
- Before sizing any election trade, verify election timing, reliable polling and rejection trends, candidate platforms, coalition support, and current market-implied volatility. These missing inputs determine whether the risk is already priced.
More News
- World Bank warns of AI concentration risks as it lifts East Asia and Pacific growth outlook to 4.5%
- OKX debuts a platform that turns 50 currencies into digital dollars, betting emerging market investors want stablecoins
- Contagion Fears in European Markets over France Fiscal Woes
- Brazil Election: Bolsonaro Pushes Lula to Brink as Markets Set to Rally
- Stocks Get Tech Lift Despite Renewed Bond Losses
- Trump blames Democrats and Ukraine for soaring US fuel prices, not Iran war
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Research Systems for Hedge Funds: A Pilot Design
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations