
Spustenie systému spolupráce „Huawei + partneri" zameraného na zákazníka s cieľom rozšíriť umelú inteligenciu naprieč odvetviami
Source: PR Newswire
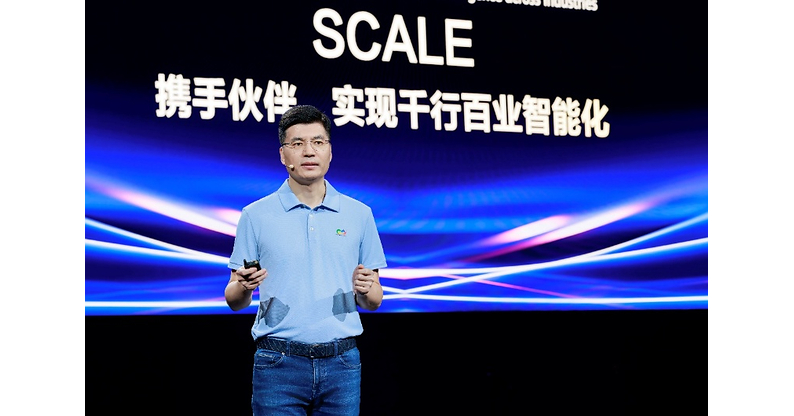
Huawei launched its SCALE partner-support framework at HUAWEI CONNECT 2026 to help customers and channel partners scale AI deployments from pilots to broad industry adoption. The company said partners have developed more than 100 scenario-based AI solutions across eight industries, supported by reference architectures for 48 high-value scenarios and over 130 global model-project demonstrations. Huawei also reported training more than 50,000 AI professionals over the past three years, reinforcing its ecosystem-building strategy, though the announcement provides no direct financial outlook or revenue impact.
Analysis
This is not an immediate earnings catalyst for public equities, but it reinforces Huawei’s strategy of converting a hardware-led installed base into a higher-stickiness enterprise AI distribution channel. The relevant competitive pressure falls on China-exposed infrastructure vendors: standardized integration tools and certified local service capacity can reduce switching costs for customers choosing domestic stacks over NVIDIA-led, VMware/Broadcom-adjacent, or Western network/storage architectures. The second-order beneficiary is the domestic compute supply chain—SMIC (0981 HK), Cambricon (688256 CH), Hygon (688041 CH), and Inspur (000977 CH)—if enterprise deployments move from experimental clusters to repeatable, multi-site procurement.
The key distinction is between partner enablement and monetization. Channel programs often produce headline solution counts well before they generate material hardware pull-through; the thesis requires evidence of backlog conversion, rising accelerator utilization, and receivables discipline rather than additional ecosystem announcements. Over the next 1-3 months, export-control developments and China enterprise IT budgets matter more than this announcement; over 6-18 months, a credible localized AI stack could compress the China addressable market and pricing power of foreign incumbents. A renewed ability for NVIDIA (NVDA) to ship materially capable China-compliant accelerators, or weak domestic-foundry yields and software interoperability, would materially weaken the localization thesis.
Contrarian view: investors may over-credit Huawei’s ecosystem narrative while underweighting implementation economics. Enterprise AI projects require measurable workflow ROI, data readiness, and ongoing inference costs; partners can expand sales coverage without solving those constraints. The better signal is not partner certifications but whether domestic server and accelerator vendors report improving gross margin alongside faster inventory turns—otherwise scale may be subsidy- or credit-driven and value accrues poorly to listed suppliers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No directional trade on the announcement alone; treat it as a 6-18 month localization watch item rather than a near-term catalyst.
- Build a monitored basket of 0981 HK, 688256 CH, 688041 CH, and 000977 CH; initiate only after at least two quarters of accelerating AI-related revenue/backlog conversion with stable or improving gross margin and receivable days. Falsify if utilization, margins, or cash conversion deteriorate despite revenue growth.
- For China-technology exposure, prefer a selective long domestic AI-infrastructure basket versus underweight China-revenue-sensitive foreign infrastructure suppliers rather than an outright short NVDA; NVDA’s China exposure is too policy-dependent and the company has broader demand offsets. Reassess the pair immediately on any meaningful relaxation of U.S. accelerator export restrictions.
- Set an alert around Chinese enterprise IT capex and local-accelerator pricing: a sustained decline in domestic accelerator ASPs without corresponding unit-volume growth would indicate commoditization and argue against supplier longs.
More News
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Factbox-Key issues for this week’s Trump-Xi summit in Washington
- Here's who we know is going to the Trump-Xi dinner so far
- +17% in a single session: This AI-picked stock catches a data-center breakout