
STATION CASINOS AWARDS TEAM MEMBERS MORE THAN $70 MILLION IN RED ROCK RESORTS STOCK AS PART OF 50TH ANNIVERSARY CELEBRATION
Source: PR Newswire
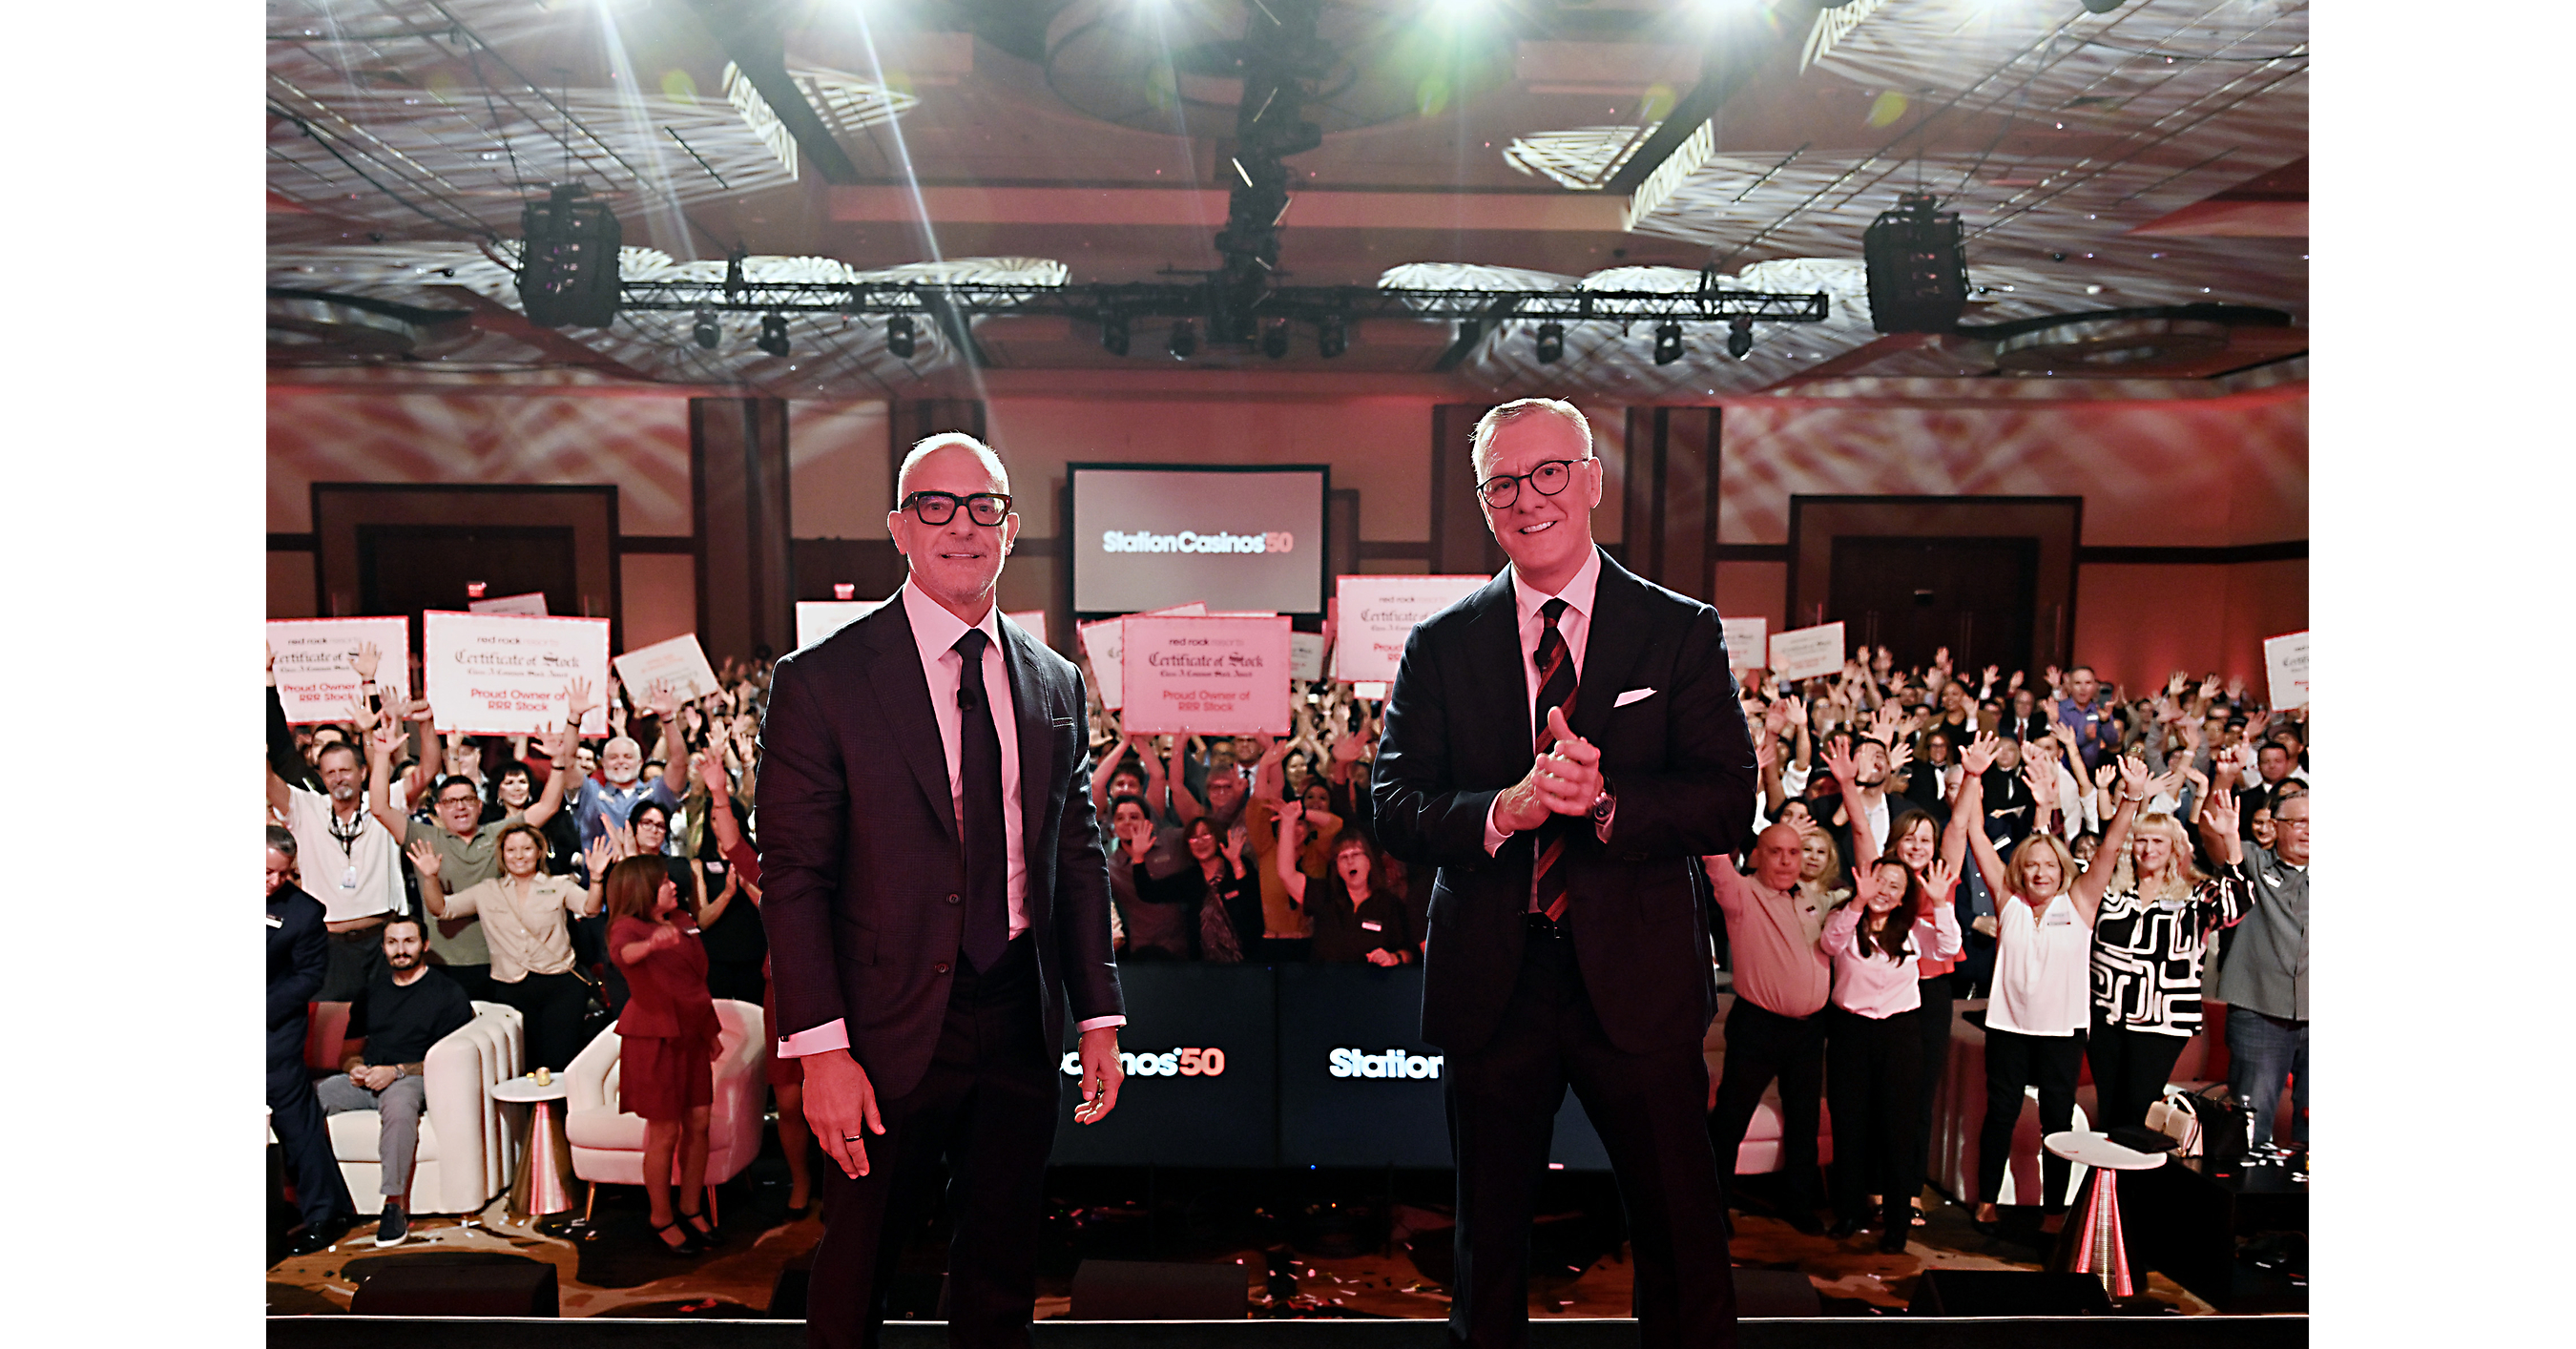
Red Rock Resorts' Station Casinos will award more than $70 million of Class A stock to nearly 10,000 eligible full- and part-time employees, equating to $1,000 in stock for every year of service. The one-time anniversary grant, with shares available beginning September 14, recognizes workforce tenure and may support retention, though it represents a modest equity-related cost rather than a material operating or strategic update. Long-tenured employees will receive substantial awards, including $49,000 for a team member employed since 1977.
Analysis
The market-relevant issue is not the employee-relations narrative but the accounting and capital-allocation treatment. If the grants have no meaningful service or vesting condition, RRR could recognize most of the approximately $70 million fair-value expense quickly, creating a non-cash GAAP earnings headwind and potentially reducing buyback capacity through associated payroll-tax withholding and share settlement. The next 10-Q should clarify whether shares are newly issued, sourced from treasury stock, or cash-settled; that distinction determines whether the cost is principally dilution, cash usage, or both.
A September 14 distribution date creates a modest but potentially visible technical overhang because many recipients will have concentrated exposure to their employer and may monetize immediately. This matters more for RRR than the headline size suggests given the Fertitta-controlled ownership structure and potentially constrained tradable float. Any initial weakness should not automatically be read as deteriorating Las Vegas-local demand, but a sustained decline with abnormal volume would signal that the issuance is larger relative to effective float than investors expect.
Operationally, the grant can improve retention among experienced casino-floor and hospitality employees, where local labor turnover directly affects service consistency, training expense, and wage pressure. That is incrementally unfavorable for Las Vegas locals competitors—most directly BYD—if it forces broader retention spending, although the benefit is unlikely to alter RRR's near-term gaming revenue trajectory. The contrarian view is that investors may over-credit a one-time award for durable labor advantages: retention gains will fade unless base compensation and scheduling remain competitive.
The key 1-3 month catalyst is the quarterly disclosure of stock-compensation expense, share count, withholding treatment, and any update to repurchase authorization. A favorable outcome would be limited incremental dilution and management maintaining capital-return cadence; thesis failure would be a material upward revision to compensation expense, a buyback slowdown, or management characterizing the program as a recurring workforce-investment template.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not initiate a directional RRR position solely on the announcement. Set an alert for September 14-30: consider buying a technically driven RRR pullback only if volume is elevated but management has not changed operating guidance or capital-return plans; reassess after the next 10-Q.
- For existing RRR longs, require confirmation that incremental diluted shares and cash payroll-tax withholding are modest relative to prior guidance. Reduce exposure if the filing shows a material share-count step-up, a buyback pause, or compensation expense that meaningfully weakens consensus EBITDA-to-free-cash-flow conversion.
- Monitor RRR versus BYD over the next two earnings cycles as a local-labor-cost spread trade rather than an immediate recommendation. A widening wage/benefit expense gap at BYD without offsetting same-store gaming growth would support long RRR / short BYD; avoid entry before payroll and retention effects become visible in margins.
- Treat any post-distribution RRR weakness as an event-driven watch item, not a structural short. The short thesis is falsified if selling volume normalizes quickly and quarterly disclosures show treasury-share sourcing with limited dilution and unchanged repurchase activity.
More News
- France Faces New Protests After Week of Violence
- Thousands of Israelis rally against Netanyahu gov’t days before election
- ‘There’s nothing temporary about a temporary store’: How Spirit Halloween’s CEO took it from 130 stores to 1,550—and swallowed your mall’s Hot Topic
- Jamie Dimon poached Warren Buffett’s protégé to run a $10 billion fund—he says Buffett’s response was ‘at least he’s going to you’
- Serbia votes in election pitting longtime leader against student movement
- Saudi Arabia Suggests Riyadh Airport May Reopen on Sunday