
SprintRay Introduces Midas Restore™, a New Definitive Restorative Material Engineered for Midas Digital Press
Source: PR Newswire
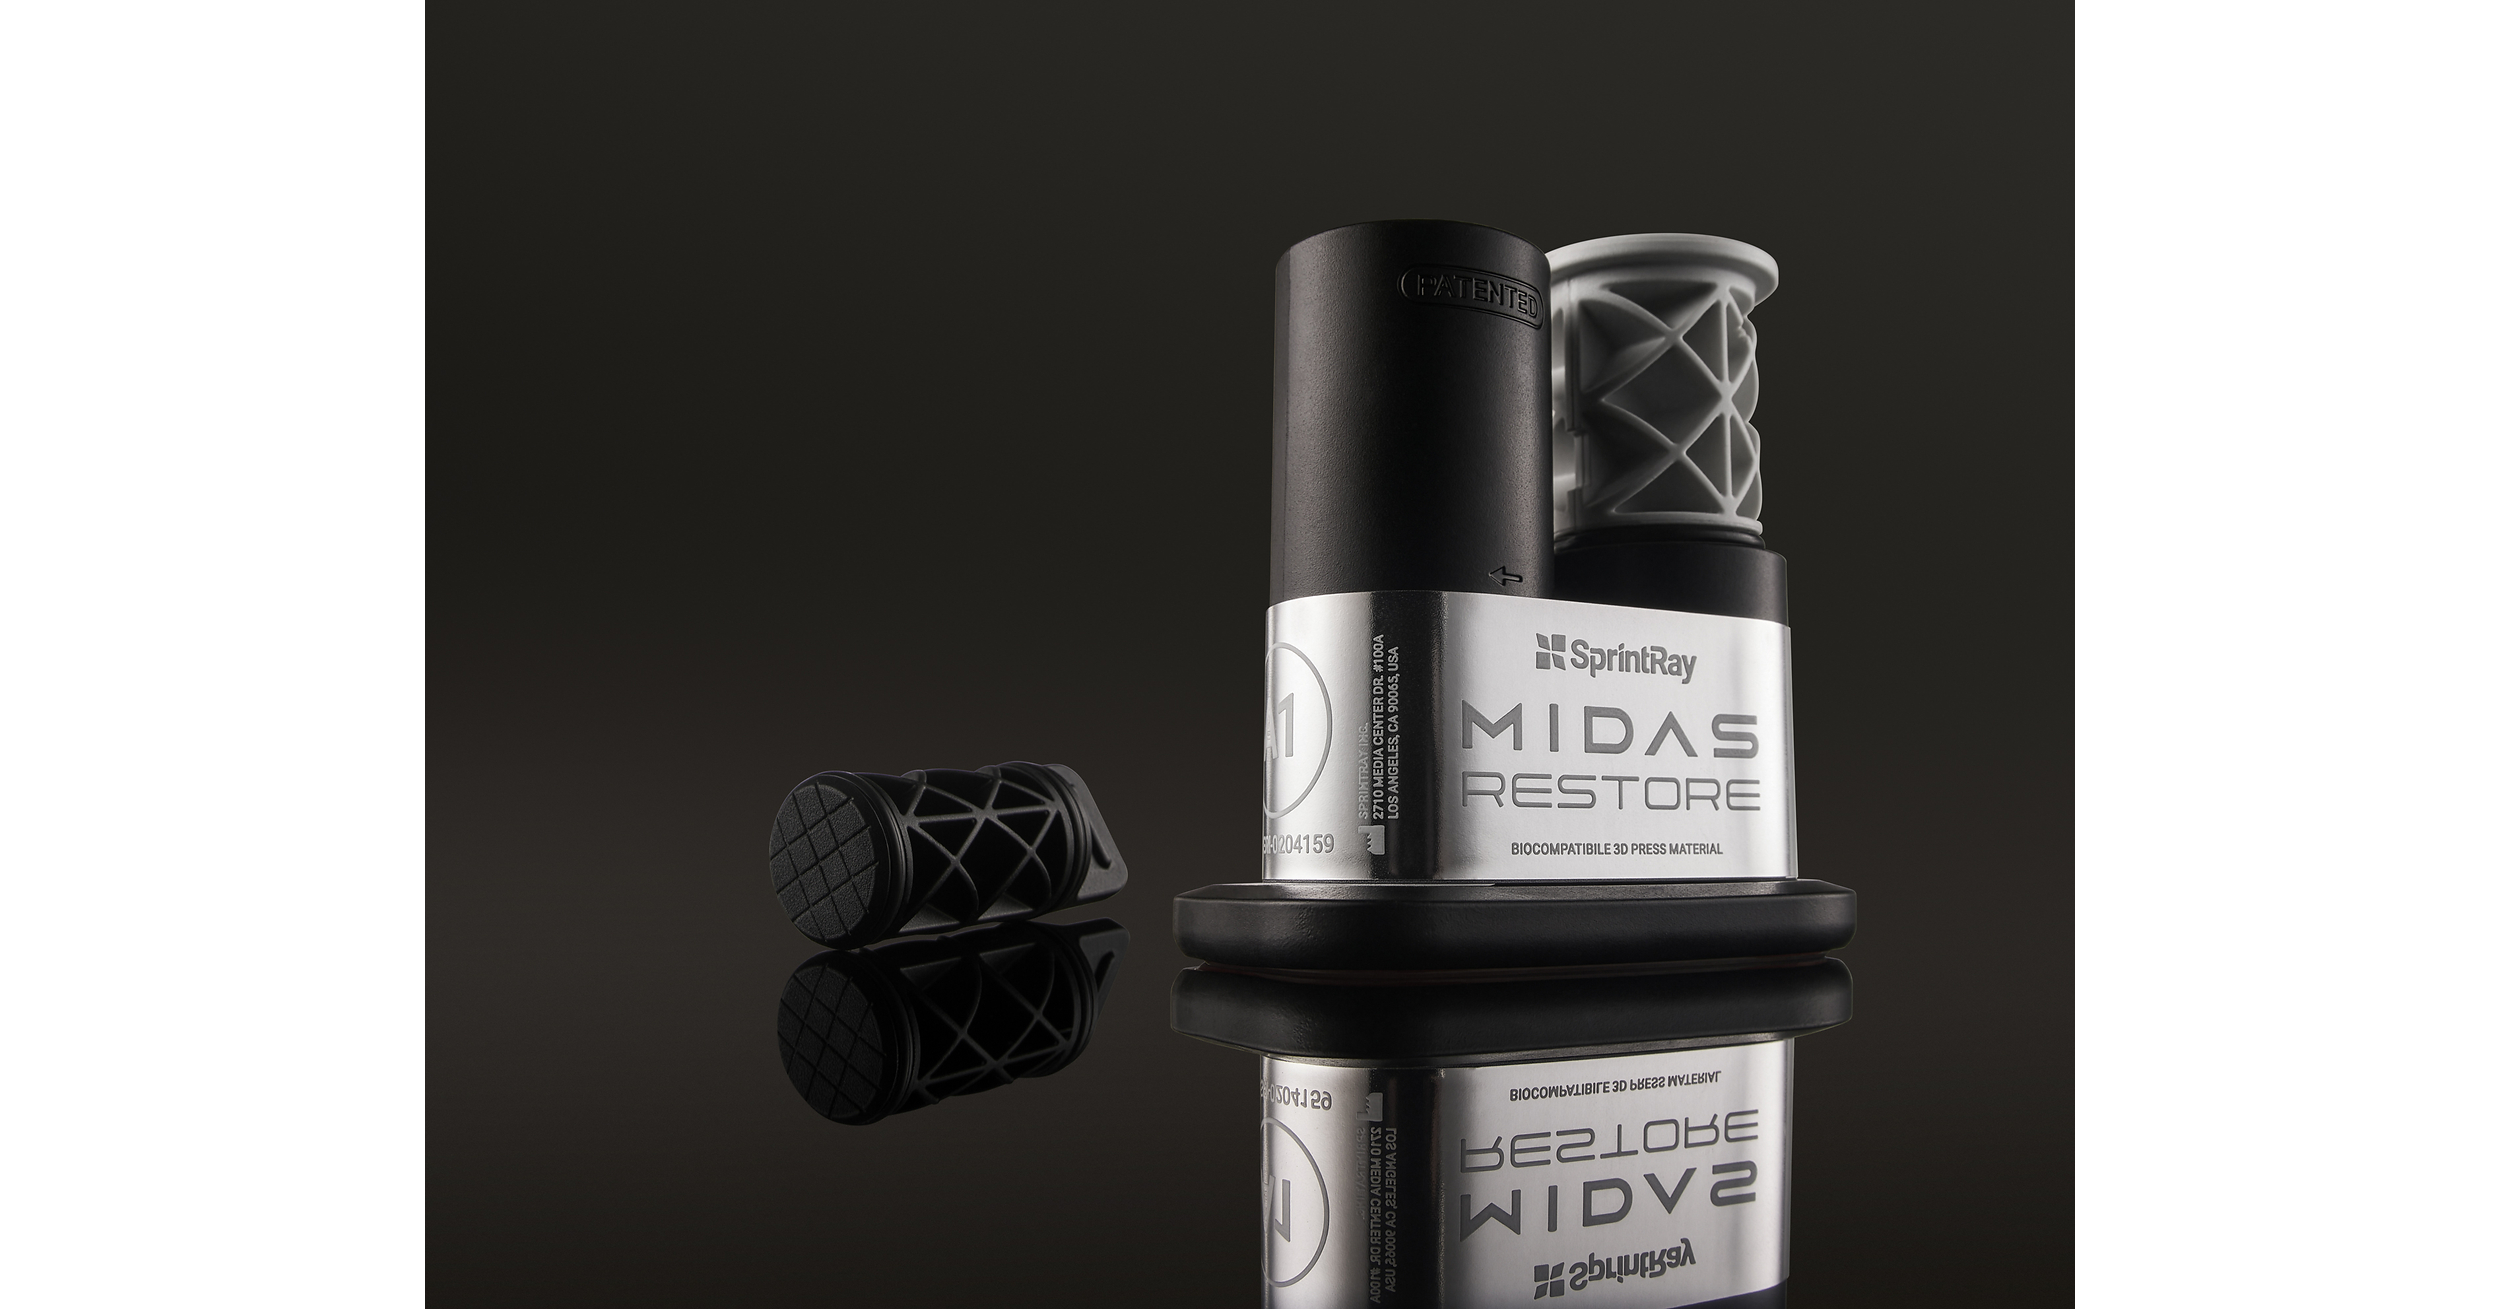
SprintRay is launching Midas Restore, a highly filled (75%+ by weight) glass ceramic/zirconia definitive restorative material built for its Midas Digital Press same-visit workflow starting Sep 1, 2026. In testing, it retained 98% of initial gloss after 5,000 simulated toothbrush cycles and showed 5x the wear resistance of SprintRay Ceramic Crown over 200,000 cycles, with maximum flexural strength of 215 MPa and surface hardness >80 HV. A 3-pack of single-unit capsules is priced at $135 and the product is FDA 510(k) cleared (Class II, Rx only).
Analysis
The investable takeaway is less about one material and more about where margin accrues in chairside dentistry. A highly filled, closed-system consumable shifts economics toward the platform owner and away from outsourced lab workflows, but that value capture is delayed until the installed base proves dentists will tolerate new bonding protocols, shade management, and training friction. In the near term, this is more likely to be a read-through for public dental CAD/CAM incumbents than a direct revenue event.
The second-order loser set is not just labs; it is any incumbent restorative workflow that depends on multi-visit friction and technician labor, because same-visit convenience compresses decision cycles and can raise practice throughput. That said, the launch timing implies no meaningful P&L impact for 12-18 months, and the market is likely to overreact to the technical claims before seeing repeat purchase rates, failure rates, or reimbursement support. If utilization data are weak, this stays a marketing story rather than a category reset.
Contrarian view: the consensus will focus on resin properties, but the real question is whether this becomes a consumables annuity with switching costs. If it does, the larger strategic threat is to older chairside ecosystems with weaker materials breadth and slower software-material integration. Falsifiers are simple: delayed U.S. availability, poor dentist repurchase, or any evidence that finishing/bonding complexity limits same-day adoption.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate fundamental position; treat this as a 6-18 month watch item until adopter data and repeat-capsule usage are visible. The thesis is falsified if launch slips or early clinic utilization is shallow.
- Conditional relative short: XRAY vs. a broad dental distribution basket on any rally driven by "digital dentistry" enthusiasm. Rationale: platform competition risk is higher than the market will price, while distribution captures only low-margin flow-through.
- Pair trade idea: long HSIC / short XRAY for 3-6 months if investors rotate toward practice-level consumables and service revenue. This works only if product adoption broadens category spend without a commensurate benefit to legacy chairside systems.
- Set a trigger on XRAY: if management commentary shows decelerating digital workflow bookings or weaker consumables attachment over the next two quarters, increase short exposure; if the opposite occurs, cover. Use earnings as the primary catalyst, not the press release.
- If you want optionality, use small-size bullish call spreads on any private/sector proxy only after independent evidence of dentist uptake emerges; otherwise, premium is likely to decay before the 2026 commercialization window.
More News
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More