
FOTON präsentiert in Hannover sein gesamtes Produktportfolio und treibt damit ein neues Modell für die globale Expansion der chinesischen Wertschöpfungskette im Nutzfahrzeugbereich voran
Source: PR Newswire
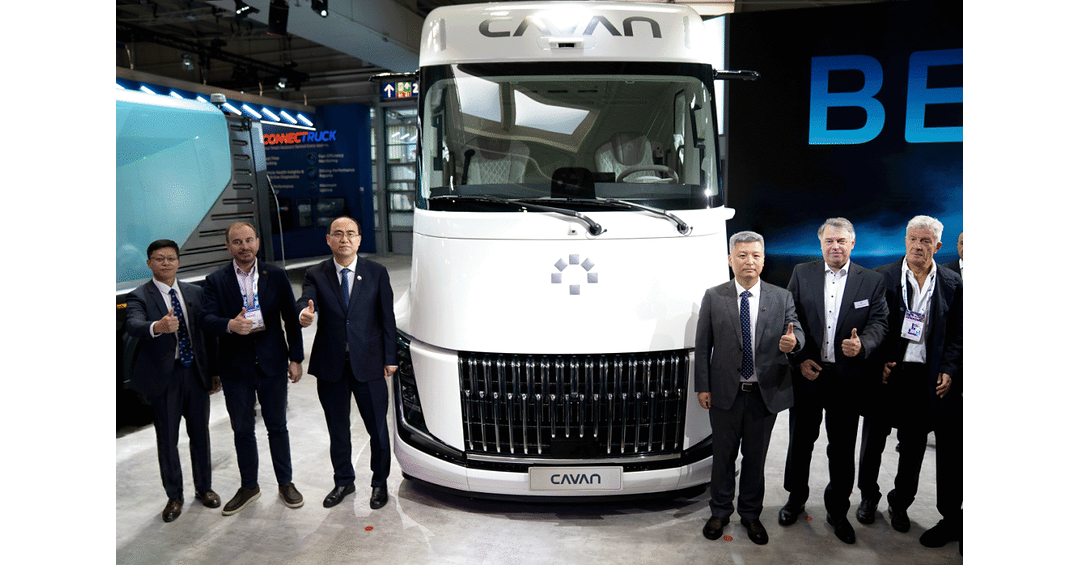
BAIC FOTON used IAA Transportation 2026 to unveil the CAVAN BEACON zero-emission heavy-duty truck platform, offering battery-electric, battery-swap and hydrogen variants with more than 600 km electric range and over 1,000 km hydrogen range. The company said megawatt charging can raise battery state of charge from 20% to 80% in 18 minutes and targets a 15% reduction in energy consumption. FOTON also marked delivery of its 13 millionth vehicle and outlined a European expansion plan targeting nearly 20 markets, more than 300 service locations and local assembly by 2028; it aims for new-energy vehicles to represent 50% of revenue and overseas sales 40% by 2030.
Analysis
The relevant read-through is not an immediate earnings event but a potential European pricing and utilization risk for incumbent truck OEMs. If a Chinese entrant can combine locally supported vehicles with financing, parts availability and fleet-data services, the competitive weapon shifts from upfront vehicle price to total cost of ownership and uptime guarantees. That would be most disruptive in light commercial vehicles and price-sensitive regional haulage before premium long-haul fleets, where Daimler Truck (DTG.DE), Traton (8TRA.DE) and Volvo (VOLV-B.ST) retain dealer density, residual-value credibility and service contracts as meaningful moats.
The technical specifications should be treated as vendor claims until independently validated in European duty cycles, payload configurations, winter conditions and residual-value data. The binding bottleneck for zero-emission heavy transport remains depot/grid interconnection and corridor charging economics, not announced vehicle capability; this creates a more credible near-term beneficiary set in charging and grid equipment than in the vehicle OEM complex. Over 6-18 months, aggressive Chinese localization could pressure European OEM gross margins if tender win rates weaken, but it could also expand component demand for power electronics, high-voltage cabling and charging infrastructure.
Consensus may overestimate the speed of displacement: European fleets purchase uptime, workshop coverage, financing and residual guarantees rather than headline range. The first investable confirmation would be disclosed fleet orders, independently reported operating cost per km, a functioning parts network, and meaningful EU registration data—not exhibition launches. There is no high-conviction directional trade solely from this release; monitor 2027 order books and European truck pricing for evidence that competition is moving from marketing to realized share loss.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.42
Key Decisions for Investors
- Maintain a watchlist rather than establish a standalone FOTON-driven OEM short: monitor quarterly European registrations, fleet-tender announcements and dealer/service expansion for DTG.DE, 8TRA.DE, VOLV-B.ST and IVG.MI over the next 3-12 months. Escalate only if Chinese brands show sustained share gains alongside incumbent order-price deterioration.
- Prefer a 6-18 month infrastructure basket over a direct truck-OEM response: selectively accumulate ABBN.SW and Schneider Electric (SU.PA) on weakness if European megawatt-charging deployments convert into contracted orders. Thesis fails if grid-connection delays and utilization rates prevent fleet charging projects from reaching commercial investment decisions.
- For relative-value exposure, use long VOLV-B.ST / short IVG.MI only after evidence of price-led competition in European medium-duty and regional fleets. Volvo's service-network and financing advantages should be more defensible; exit if Iveco demonstrates stable order pricing, improving backlog conversion, or wins disproportionate zero-emission fleet contracts.
- Set an alert around EU trade-policy developments affecting Chinese commercial vehicles. A tariff, local-content rule or subsidy restriction could sharply delay penetration and invalidate any incumbent-margin compression thesis; conversely, no policy response plus verified fleet orders would warrant reassessing a short basket of lower-scale European OEM exposure.
More News
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Karin Rådström is steering Daimler Truck in a new direction as the world’s biggest truckmaker faces a growing challenge from China
- MBS and Saudi Arabia Face Crisis With Key Oil Pipeline Shut for Weeks
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Oil’s next test: Saudi Arabia races to restore a key safety valve for prices