
Bitmine Immersion Technologies (BMNR) Announces ETH Holdings Reach 5.96 Million Tokens, and Total Crypto and Total Cash Holdings of $15.8 Billion
Source: PR Newswire
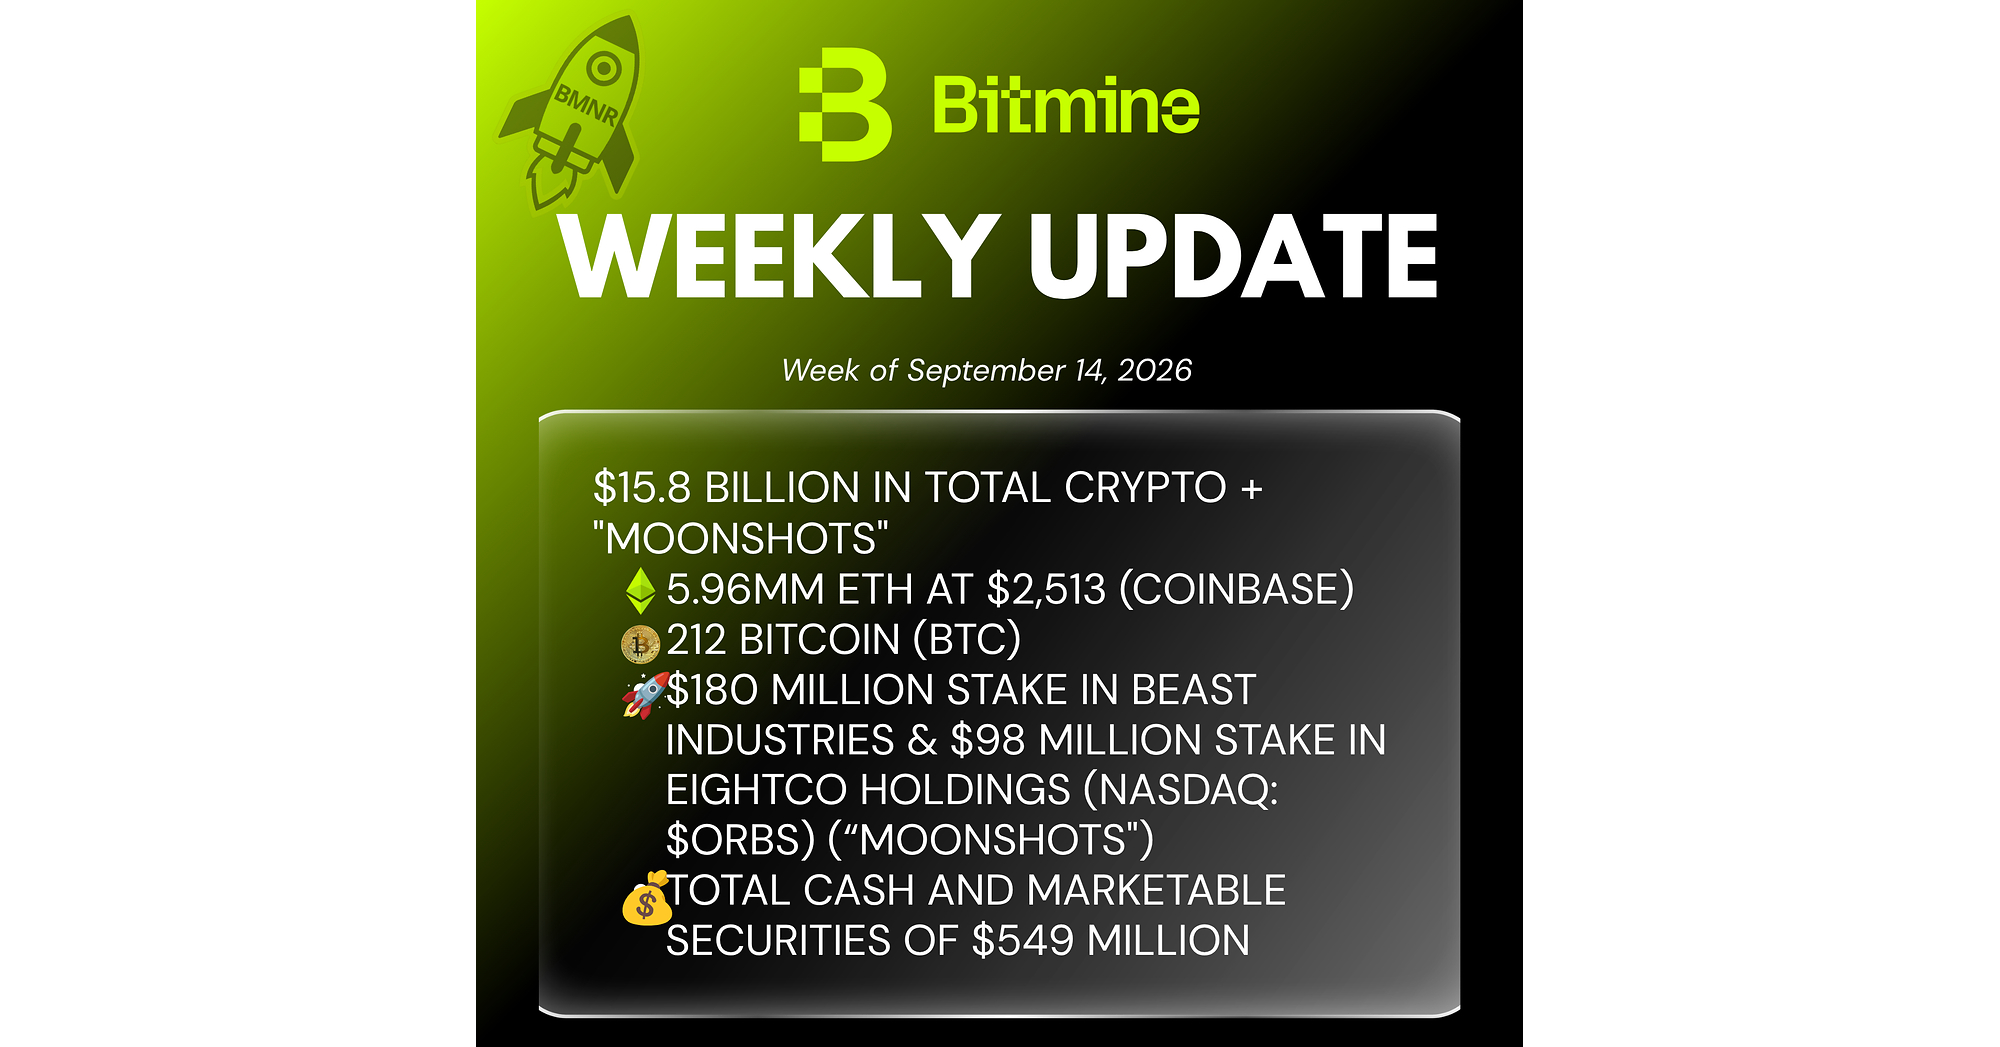
Bitmine reported holdings of 5.96 million ETH, valued at $15.0 billion at $2,513 per ETH and representing 4.9% of Ethereum supply, after acquiring 27,180 ETH during the past week. The company has staked 5.07 million ETH, or 85% of its ETH holdings, and projects annualized staking revenue of $334 million currently and $392 million once fully staked at a 2.62% annualized yield. Management highlighted ETH's 5,866bp Q3 outperformance versus the S&P 500 and expects institutional demand, tokenization, agentic-AI use cases, and prospective U.S. crypto legislation to support further upside.
Analysis
BMNR is economically a leveraged, externally financed ETH closed-end vehicle rather than a conventional infrastructure company. A 10% move in ETH changes indicated asset value by roughly $1.5 billion before any staking income, making the equity's near-term return dominated by ETH beta, the stock's premium/discount to NAV, and potential dilution—not by the operating narrative. The staking yield should not be capitalized as a software-like revenue stream until management discloses third-party assets, fee take-rate, custody economics, and validator operating costs; self-staking primarily monetizes an asset already owned.
The non-obvious risk is concentration: a treasury approaching 5% of ETH supply may reduce available float during risk-on periods, amplifying upside, but creates a uniquely large forced-seller and validator-concentration overhang in a drawdown. Liquidity in BMNR stock does not eliminate liquidity risk in converting a multibillion-dollar ETH position without affecting market price, particularly if equity holders demand NAV realization. The stated moonshot positions have negligible relevance to intrinsic value versus ETH exposure but can complicate NAV transparency and invite a conglomerate discount.
Over days, regulatory headlines and momentum flows can sustain a reflexive BMNR premium. Over 1-3 months, the key catalyst is whether institutional ETH demand broadens independently of treasury-company issuance; if it does not, recurring equity issuance to fund accumulation transfers upside from existing shareholders to sellers of capital. Over 6-18 months, competitive pressure from ETH ETFs and other treasury vehicles should compress any persistent BMNR premium unless MAVAN demonstrates material third-party fee revenue. Thesis is falsified by sustained ETH strength alongside a narrowing BMNR NAV premium, a staking-yield decline, disclosed dilution, or adverse staking regulatory treatment.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Do not chase BMNR on the release alone. Calculate fully diluted market cap versus marked NAV at the next filing; only consider a tactical long if BMNR trades at or below NAV and ETH holds above $2,500, with a 1-3 month target of a 15-25% NAV-premium normalization and a stop if ETH falls 10% or new share issuance is announced.
- If BMNR trades at a premium greater than 25% to independently calculated NAV, initiate a market-neutral relative-value position: short BMNR versus long ETHA (or ETH futures sized to ETH delta). Target premium compression to below 10% over 1-3 months; exit if the company demonstrates verifiable third-party staking AUM or the premium expands above 40%.
- Prefer direct ETH exposure through ETHA over BMNR for directional institutional-crypto upside through year-end: it removes financing, governance, moonshot-mark valuation, and holding-company-discount risk. Use a 10-12% ETH downside stop or reduce exposure if the regulatory catalyst is delayed or materially diluted.
- Monitor COIN as the cleaner listed beneficiary of higher ETH turnover and institutional participation, but require confirmation in exchange volumes and transaction revenue rather than treasury-company price action. A long COIN versus short BMNR is attractive only if BMNR's NAV premium exceeds 25% and COIN volume trends accelerate for at least two weeks.
More News
- Clarity Act faces make-or-break Senate vote on Tuesday as crypto industry pushes for bill
- The U.S. stock market is having a Napster moment—the Robinhood-AMC fight is just the beginning
- Wall Street’s new pair trade: Long software, short chips
- BTCS expands DeFi operations to Base Layer-2 network
- Bulls Say AST SpaceMobile Is a 10-Bagger. Bears Say It's Overhyped. Who's Right?
- Why is Intuit stock climbing today?