
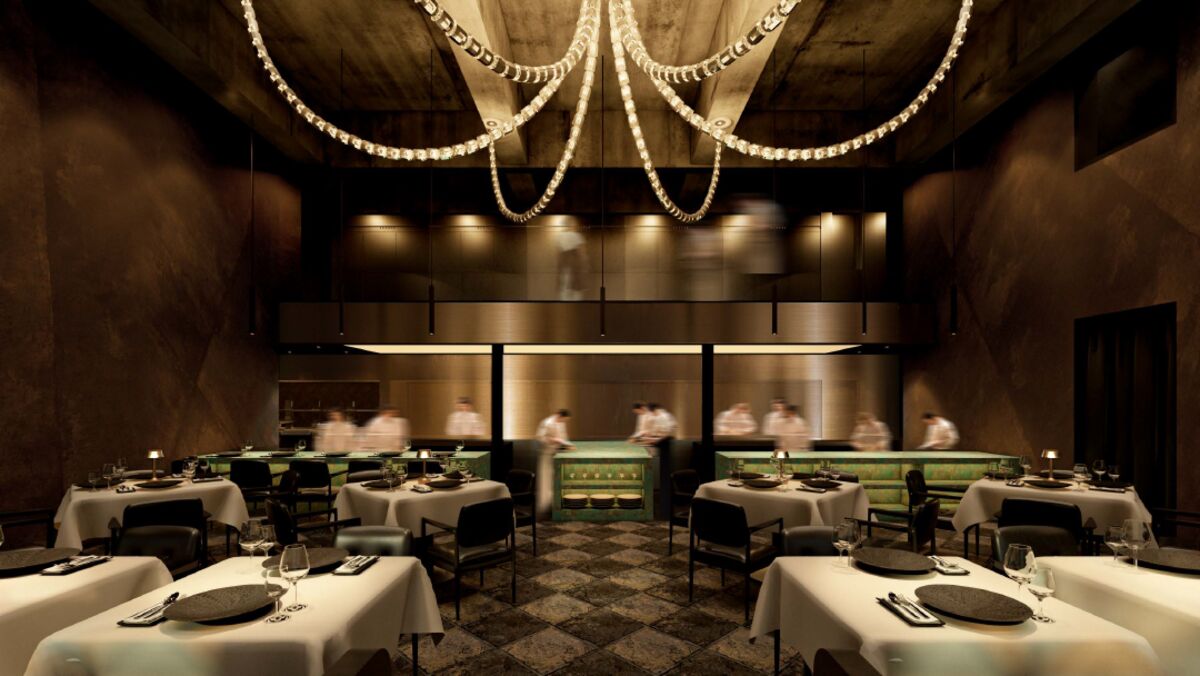
Chef Gaggan Anand’s Delhi Restaurant RAGA Tests India’s Appetite for Fine Dining
Source: Bloomberg
This appears to be a Bloomberg editorial/welcome note for an “India Edition” newsletter, with no reported economic data, company results, policy changes, or market-moving developments.
Analysis
This reads more like a soft read-through on Indian premium consumption than a directly monetizable catalyst. The relevant mechanism is not the chef himself, but the signaling effect: if high-end dining and experiential spending are becoming more socially acceptable, that can support a longer runway for premium hotels, destination restaurants, and luxury retail in India. The investable angle is second-order and slow-moving, with benefits accruing to operators that can monetize affluent urban demand rather than mass-market brands.
The market should be careful not to overread a cultural anecdote into earnings power. For listed proxies like IHCL or ITC’s premium hospitality/F&B exposure, the thesis only matters if it shows up in actual pricing power, higher average daily rates, or sustained occupancy gains over the next 1-3 quarters. Without that, this is narrative inflation, not a catalyst.
The contrarian risk is that premiumization in India is already a consensus theme, so any incremental optimism may already be embedded in multiples. If consumer spending softens, or if luxury demand remains concentrated in a narrow urban cohort, the optionality here stays limited. Falsifiers are simple: no improvement in RevPAR, outlet-level same-store sales, or management commentary on premium demand in upcoming earnings.
Net: this is a watch item, not a high-conviction trade. The only real edge would be to wait for hard operating data before paying up for the premium consumption story.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No immediate trade: treat this as a low-signal cultural anecdote and avoid initiating fresh risk in Indian consumer discretionary names solely on this basis.
- Watchlist only: monitor IHCL and ITC for next 1-2 quarters of RevPAR, ADR, and premium F&B commentary; consider a long only if those metrics inflect, otherwise stay neutral.
- If looking for a relative-value expression, prefer a small long IHCL vs. a broader India consumer basket only after evidence of premium demand strengthens; current risk/reward is not compelling.
- Do not chase premium dining/experience exposure via small-cap restaurant names absent hard same-store sales data; the story is vulnerable to narrative-driven multiple compression.
More News
- US forces disable ship ‘attempting to run’ Iran blockade in Gulf of Oman
- Middle East war, high debt levels to dominate IMF-World Bank meetings in Bangkok
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- India’s Rupee Defense Raises Question of How Far RBI Will Go
- CBO chief warns it’s ‘probably not plausible’ that a strong economy alone can steady U.S. debt as 5%-6% growth is needed—more than Bessent’s 3% view
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More