
Habanos, S.A. ha presentado el Montecristo Fragata, un nuevo humidor de viaje
Source: PR Newswire
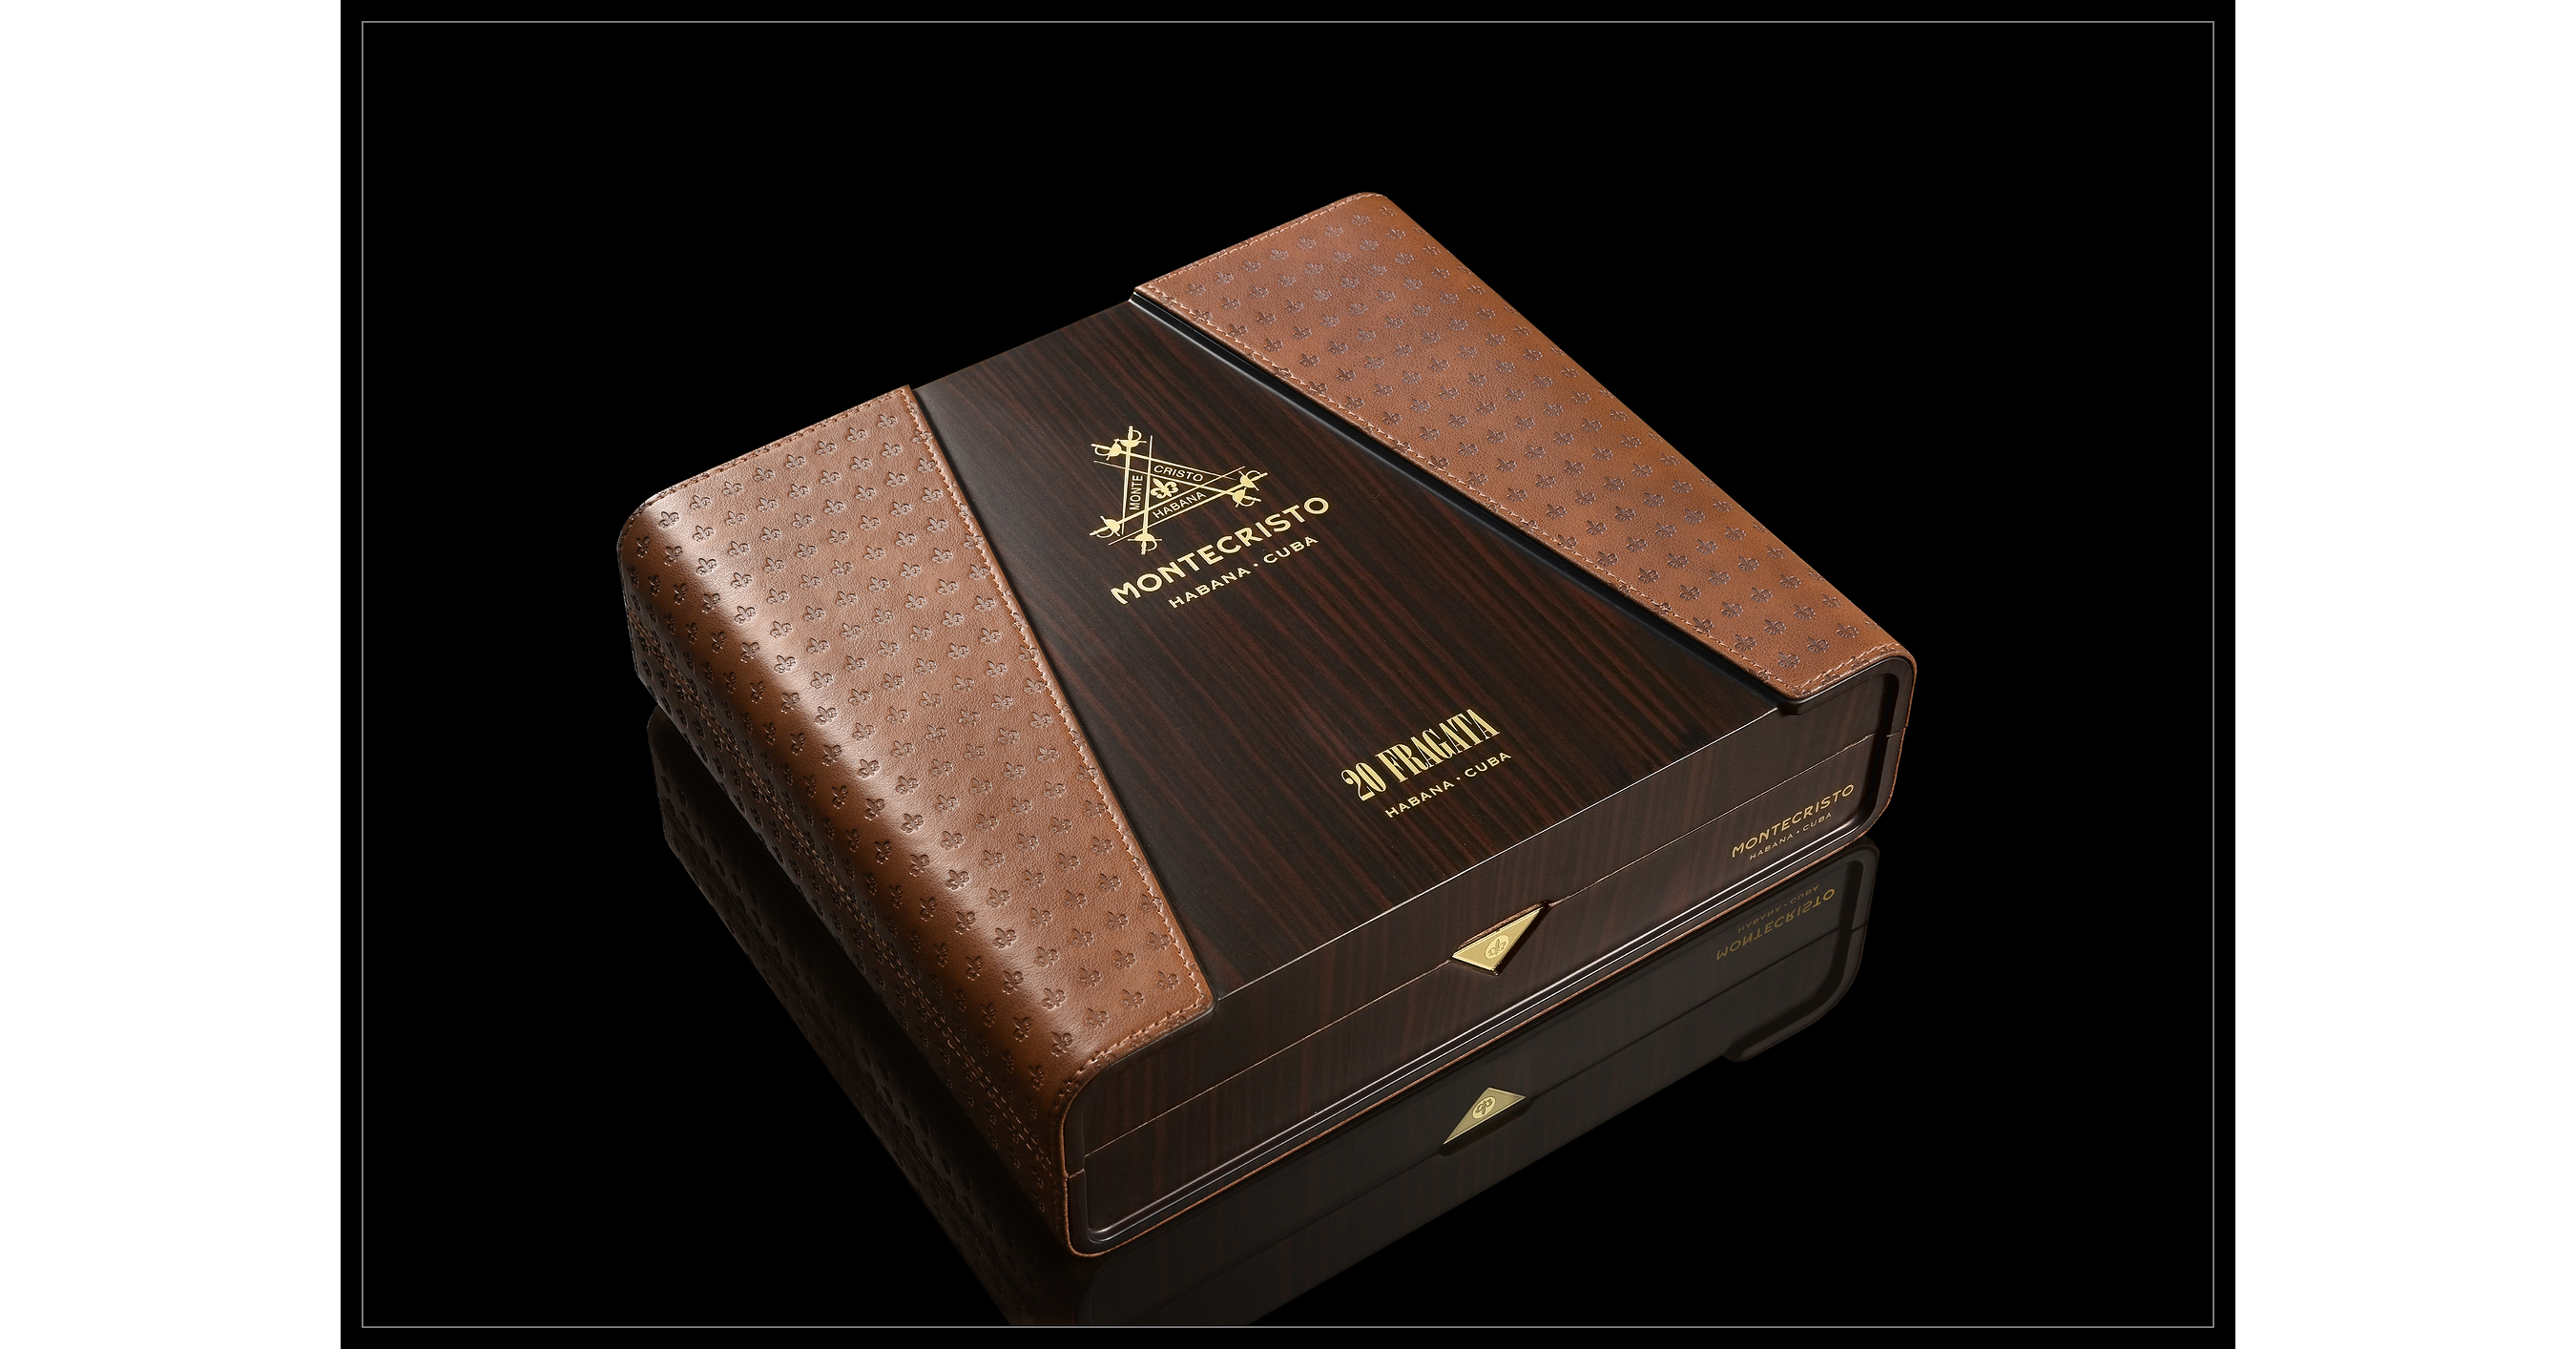
Habanos, S.A. launched Montecristo Fragata, a travel humidor containing 20 newly developed Duke-format cigars, exclusively for duty-free and travel-retail channels. The product is priced at $64/€55 per cigar, or $1,280/€1,100 per box, extending Montecristo's luxury travel-retail range following the brand's 90th anniversary. The launch supports premium-brand positioning but is unlikely to have material broader market impact.
Analysis
This is not investable as a standalone catalyst: Habanos is privately held, and a limited travel-retail SKU is unlikely to alter the earnings trajectory of listed airport, luxury, or tobacco companies. The useful read-through is directional rather than quantitative: premium discretionary spend at airports remains attractive enough for suppliers to reserve scarce, high-margin inventory for travel retail, where exclusivity can support price realization and reduce promotional intensity.
The closest public beneficiaries are travel-retail operators and airport concessionaires with meaningful premium category exposure, including Avolta (AVOL.SW) and Lagardere (MMB.PA), but any revenue contribution from this product will be immaterial. A more relevant 1-3 month watch item is whether comparable premium launches and airport retail sales point to accelerating international passenger spend per enplanement; that would support a broader rerating of AVOL and airport operators rather than a Habanos-specific trade.
Second-order risk is regulatory and supply constrained. Tobacco display restrictions, excise changes, and airport duty-free rule revisions can quickly erode category economics, while Cuban-origin product availability is inherently exposed to crop, logistics, and geopolitical disruption. A sustained weakening in long-haul premium travel or evidence that luxury travelers are trading down would invalidate the modestly constructive read-through; absent corroborating passenger-spend data, no new position is warranted.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No direct trade: treat this as a low-impact private-company product announcement rather than a catalyst for listed equities.
- Maintain AVOL.SW on a 1-3 month watchlist; consider a tactical long only if quarterly organic sales and spend-per-passenger data show premium-category growth exceeding passenger-volume growth by at least 2-3 percentage points. Exit on negative organic sales guidance or material duty-free regulatory restrictions.
- Monitor MMB.PA travel-retail disclosures for premium mix and margin progression; a confirmed improvement could support a long AVOL.SW / short broad European consumer discretionary pair, isolating travel-retail spend resilience from domestic retail exposure.
- Do not infer a bullish tobacco-sector signal for PM or BTI: Cuban premium cigars have limited economic linkage to their combustible-tobacco P&Ls, while regulatory risk remains asymmetric.
More News
- Anthropic warns government attitudes may hurt customer ties, IPO prospectus shows: Reuters
- Your health insurance premiums may take a big jump in 2027 — here's why
- Paramount and Warner Bros. Discovery to Merge Into Skydance (SKYD). Will Skydance Achieve David Ellison’s "Quality Storytelling" Vision?
- Big Pharma turns to China for new drugs as patent cliff drives multibillion-dollar deals
- Why Lilly and Novo are betting on amylin to power a new wave of obesity drugs after GLP-1s
- Tesla reports 486,532 vehicle deliveries for third quarter, topping expectation