
Xinhua Silk Road: Se inaugura en Hunan la 5ª Conferencia de Desarrollo Turístico de Changsha
Source: PR Newswire
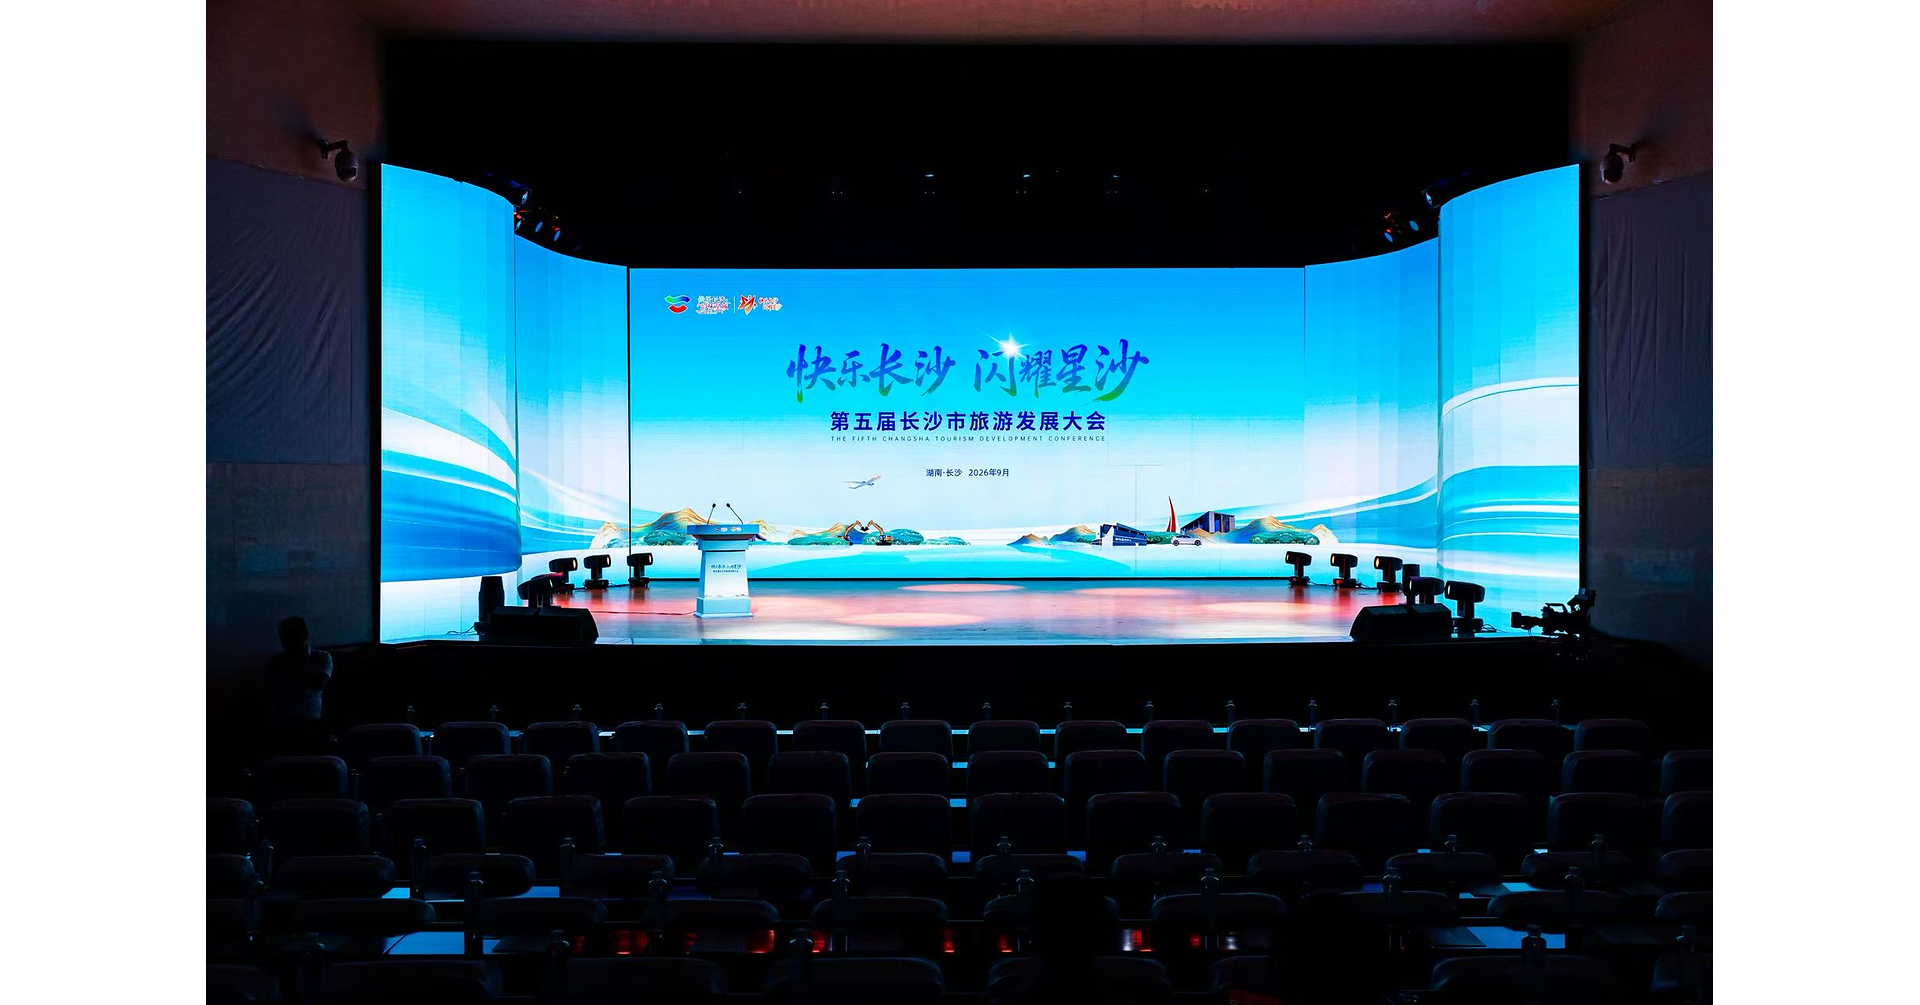
Changsha inaugurated its fifth Tourism Development Conference, promoting red-culture, ecological, rural, industrial and convention tourism to position the city as a micro-vacation destination. Tourist arrivals and total tourism spending in Changsha doubled in 2025 versus 2021, while spending by foreign tourists rose more than 40% year over year. The conference’s six related events are intended to sustain tourism consumption, though the announcement is unlikely to materially affect broader financial markets.
Analysis
This is not independently investable news for listed China travel equities: a county-level promotional event is unlikely to alter FY26 booking, take-rate, or marketing-cost assumptions for Trip.com (TCOM) or Tongcheng Travel (0780 HK). The more relevant read-through is whether local-government tourism subsidies and event programming broaden into a nationwide consumption-support template; that would favor asset-light online travel agencies over hotel owners and transport operators, which absorb more operating leverage and price competition.
Near term, the release is a weak positive for Golden Week demand sentiment but lacks audited room-night, average daily rate, rail/air volume, or subsidy-budget data. Over 1-3 months, TCOM’s valuation sensitivity will be driven far more by outbound booking recovery, airline capacity, and domestic hotel pricing than by incremental regional destinations. Over 6-18 months, industrial-tourism promotion could modestly support GAC Group (2238 HK) brand traffic, but conversion into vehicle sales is unproven and GAC Aion’s competitive position depends on EV pricing and channel economics, not visitor footfall.
The contrarian point is that strong visitor-count growth can be economically low quality: public events can raise traffic while depressing revenue per visitor through discounts, vouchers, and free attractions. A broad Chinese consumer-recovery trade should therefore require confirmation in discretionary spend per traveler and hotel RevPAR rather than headline arrivals; absent that, the likely beneficiaries are local service merchants rather than liquid listed equities.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No standalone position from this item; treat it as a low-impact sentiment datapoint rather than a catalyst for TCOM, 0780 HK, or 2238 HK.
- Monitor Golden Week data over the next 2-4 weeks: initiate a tactical long TCOM only if domestic travel spending per trip and hotel/air pricing exceed 2025 levels while management commentary indicates stable customer-acquisition costs. Falsifier: volume growth accompanied by declining take rate, ADR, or booking monetization.
- For China consumption exposure over the next 1-3 months, prefer an asset-light OTA expression via TCOM over hotel or transportation operators if high-frequency travel data confirm pricing power; avoid using GAC Group as a tourism proxy because EV price cuts and inventory risk dominate any tourism-related benefit.
- Set an alert for a provincially or nationally funded tourism-consumption voucher program with disclosed budget and participating platforms. That would be a more actionable catalyst for TCOM/0780 HK, though the trade should be reduced if subsidies are structured as platform-funded discounts that raise marketing expense.
More News
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Goldman pushes Fed rate hike to December after cooler inflation
- NIO reports 37,408 vehicle deliveries in September, up 7.7% YoY
- Huawei unveils Mate 90 phones, leans on homegrown chip design to offset US curbs
- US Core PCE Rises 0.2%, Consumer Spending Soars in August
- Contract vote looms for Boeing workers after improved offer
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)
- AI for M&A Target Screening: From Universe to Deal File