
Defense Giant Lockheed Martin Just Got a Little Bigger
Source: fool.com
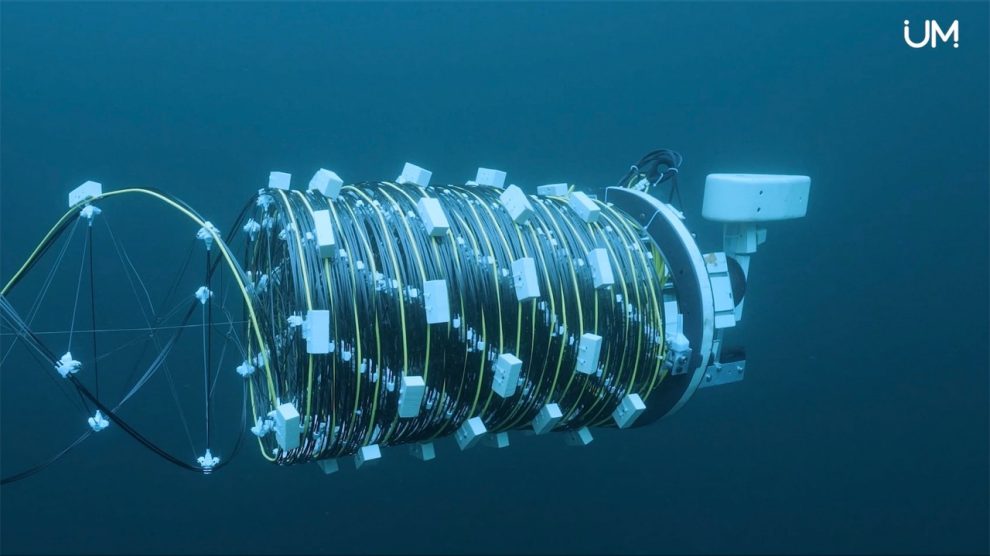
Lockheed Martin completed its $3.45 billion acquisition of Ultra Maritime, which may add as much as $1 billion in annual revenue to its Rotary and Mission Systems division. Ultra was reportedly generating roughly $535 million in revenue before being taken private in 2022, and grew revenue at a 17% annual rate under Advent; the article estimates current margins could be near 15%, but Lockheed and Advent have not disclosed the business’s precise financials. At the estimated revenue level, the purchase price is about 3.5 times sales, and the article’s author says the deal is probably worth the risk given Lockheed’s 18% forecast earnings growth, 22-times earnings valuation, and 2.3% dividend yield.
Analysis
The strategic value is less about adding scale than buying a niche capability that can be bundled with Lockheed Martin’s combat systems and sold into allied undersea-modernization programs. That may improve bid competitiveness and create follow-on service demand, but customer qualification and defense procurement cycles make conversion to revenue slow; the deal is unlikely to change LMT’s consolidated growth profile near term. The margin thesis is conditional: the article’s implied current revenue and legacy margin figures are estimates, not disclosed deal economics. If Ultra Maritime has retained strong margins, it could lift RMS mix; if growth required elevated investment or margins have compressed, the purchase price may look less attractive and RMS’s lower-margin profile may persist.
Near term, focus on integration and the first post-close financial disclosures, not strategic language. Over 1–3 months, management commentary on backlog, organic growth, and segment profitability is the key catalyst. Over 6–18 months, allied submarine and antisubmarine procurement can support a durable opportunity, but contract timing, export approvals, and program execution are material risks. Thales, RTX, and General Dynamics are plausible competitive reference points; a stronger Lockheed bid position could pressure competitors, though there is no evidence yet of displaced awards. The contrarian point: the deal may be strategically sound without being immediately material to LMT earnings. Do not capitalize the seller’s reported growth rate into a valuation premium before Lockheed discloses comparable economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone event-driven trade: the acquisition is closed and the available financial detail is too uncertain to underwrite near-term earnings accretion. Treat LMT as a watch/hold pending deal contribution disclosures rather than buying solely on the strategic rationale.
- Use the next earnings reports as the entry trigger for a modest LMT add on weakness only if management confirms Ultra’s organic growth, operating contribution, and integration costs; avoid adding if the thesis depends solely on estimated revenue or historical margins.
- Track RMS operating margin, acquired-business growth, backlog conversion, and any guidance revisions over the next 1–3 quarters. A failure to show improving RMS profitability despite integration progress would falsify the margin-mix thesis.
- Monitor allied undersea procurement awards and export approvals over 6–18 months. Delayed awards or evidence that Ultra’s growth is concentrated in a few programs would weaken the structural case; successful cross-selling would strengthen it.
More News
- Meghan Welch's Bull Case in Defense & Aerospace as U.S.-Iran War Lingers
- As Trump eyes new attack, Iran vows to retaliate beyond the Mideast and target financial assets, while oil markets brace for generational damage
- Why AI is boosting Meta's ad business while hurting Google search
- Binance sees outflows stabilising as exchange returns online after $6.3 billion heist
- China’s top three airlines head for full-year losses as fuel costs weigh
- Westpac Profit Misses Estimates, CEO Says Economy Uncertain