
E&R Engineering to Launch New Malaysia Plant: Expanding Global Packaging Materials Production and Localized Services
Source: PR Newswire
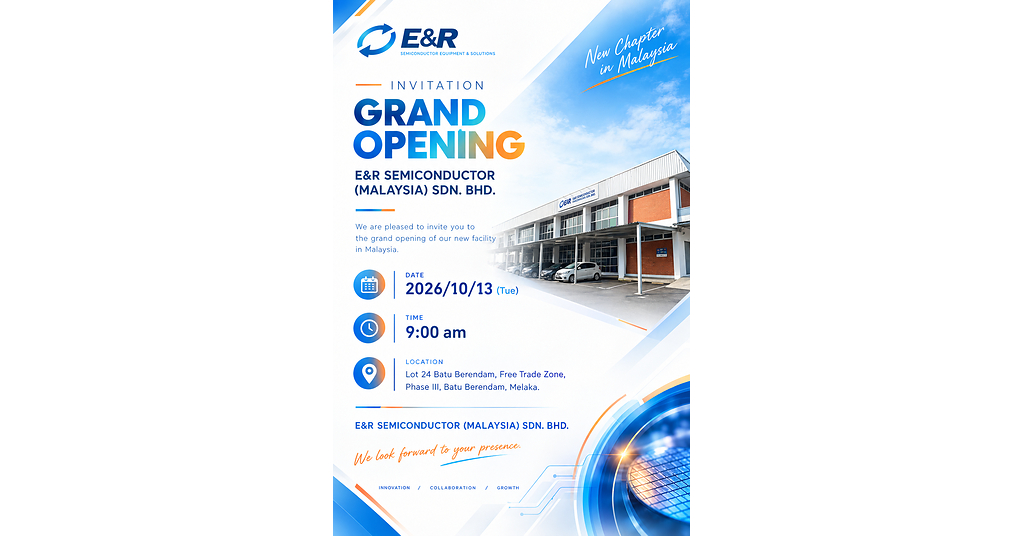
E&R Engineering will open a Malaysian packaging-materials plant in Melaka on October 13, shifting part of production from China while expanding overall capacity; mass production is scheduled to begin early next year after sample testing and qualification. The facility is expected to create 50 local jobs and provide localized production and technical support for semiconductor and OSAT customers in Southeast Asia.
Analysis
The investment case is operational execution, not the opening event: local production and service could improve response times for Southeast Asian OSAT customers, but that advantage only matters if qualification converts into recurring orders and acceptable utilization. The key distinction is whether Malaysia adds net capacity against incremental demand or mainly relocates production from China; the latter may improve customer access while adding start-up costs without increasing consolidated revenue. Local hiring, qualification, yield, and customer approvals are the near-term constraints.
Over the next few days, the announcement itself offers little evidence of earnings materiality. Over 1–3 months, track qualification milestones and any disclosed customer wins or production timing. Over 6–18 months, utilization and product mix determine whether the facility becomes a margin-accretive regional hub or a fixed-cost burden. A broader second-order benefit could accrue to OSATs seeking shorter supply chains, but the article does not establish that customers will switch suppliers or that E&R has exclusive business.
Contrarian point: Malaysia’s growing backend ecosystem is a demand backdrop, not proof of E&R’s share gains. The press release provides no capex, revenue contribution, customer commitments, utilization target, or margin data. Without those, neither the market opportunity nor the expected return on the plant can be underwritten. The thesis weakens if qualification slips beyond the stated ramp window, customer adoption is limited, or management indicates the move is chiefly a transfer of existing production.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No event-driven position on the opening announcement alone; treat it as a watch item until customer qualification and production progress are independently evidenced.
- For any existing exposure to E&R Engineering, seek disclosure on Malaysia capex, expected capacity, customer approvals, utilization ramp, and whether production is incremental or shifted from China before updating earnings assumptions.
- Set a 1–3 month catalyst watch for qualification and mass-production updates; reassess the positive thesis if the planned early-2027 ramp slips or management reports weak customer conversion.
- Do not infer a broad OSAT or Malaysian semiconductor trade from this single supplier expansion; revisit only if multiple customer or supplier disclosures confirm localized sourcing gains.
More News
- Yemeni government launches offensive to seize all areas from Iran-backed Houthis
- ‘Unwelcome and unsafe’: Why Japanese companies are retreating from China at a record pace
- SoftBank’s Masayoshi Son Has Rare Cautionary Note on AI Safety
- Sen. Mitch McConnell closed a loophole in a hemp law he championed. Now a $28 billion THC industry that gets people high is fighting for survival
- Persian Gulf oil flows return to prewar levels, but Iran could resort to a ‘scorched earth campaign’ as U.S. deploys more ships and Marines to Mideast
- Germany's Merz arrives in Kyiv to finalize drone deal, release aid