
Laars® expands LT Series Tankless Water Heater series with 150 MBH model
Source: PR Newswire
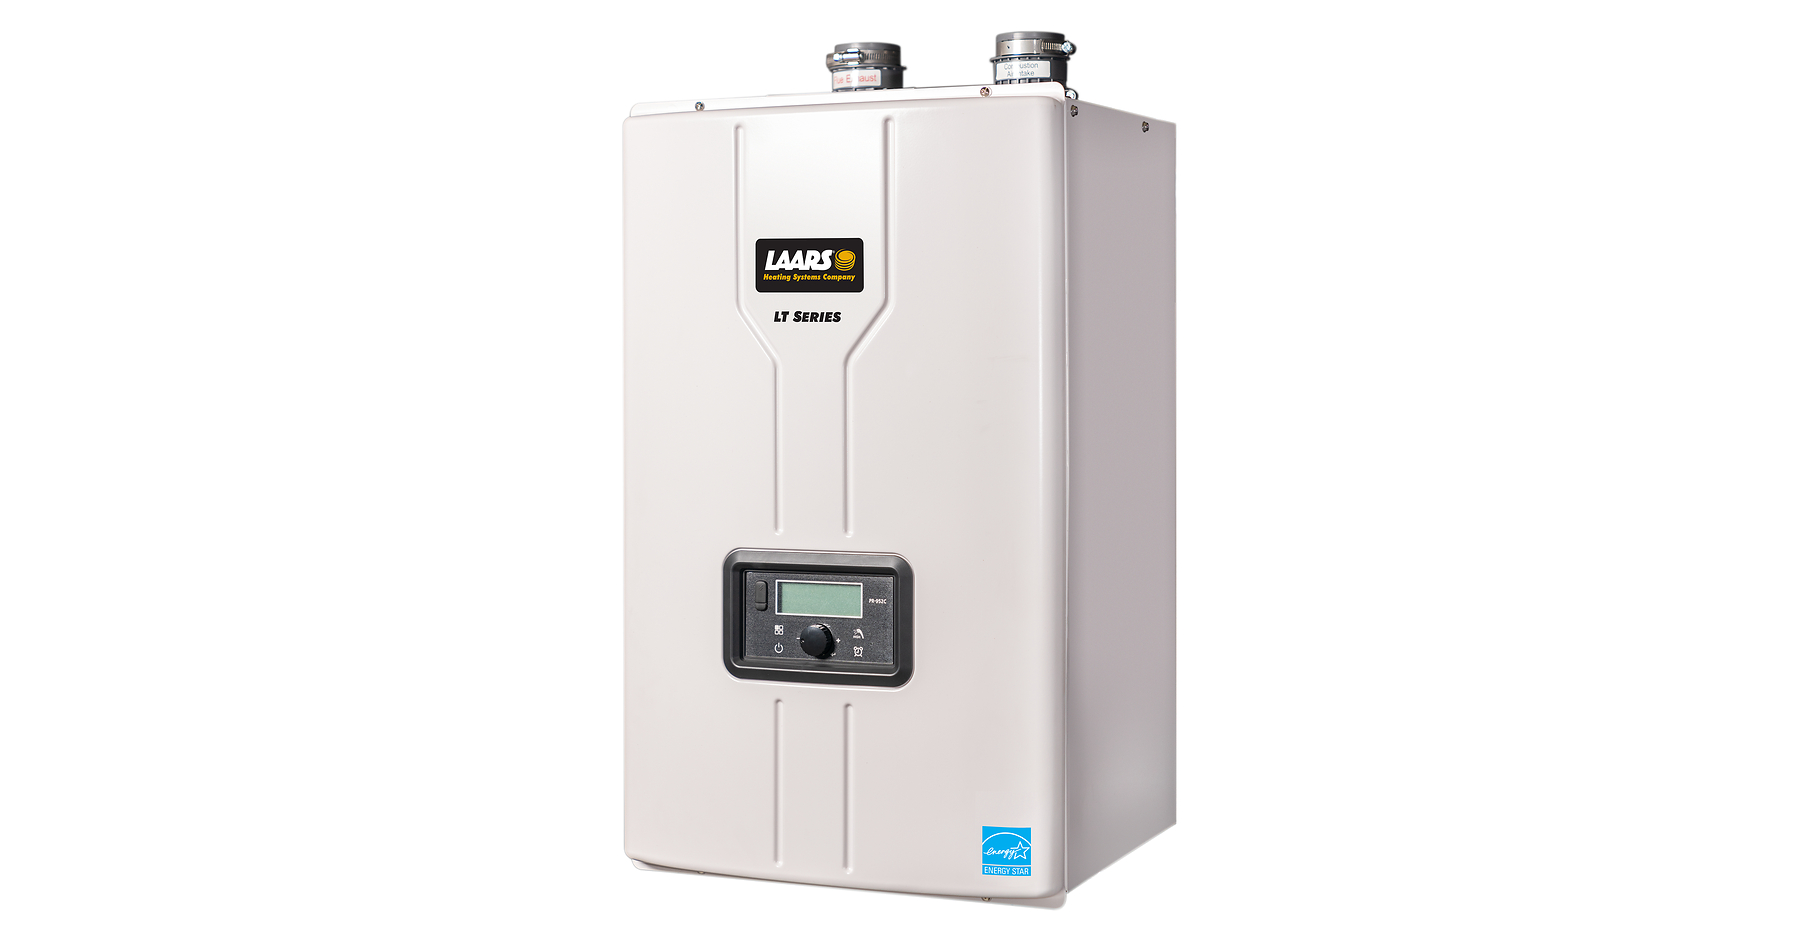
Laars Heating Systems launched a 150,000 BTU/Hr LT Series condensing tankless water heater, expanding its commercial and residential product range. The ENERGY STAR-certified LT 150 has a 0.98 UEF, while the 199,000 BTU/Hr LT 199 has a 0.96 UEF; both are designed to meet stringent NOx requirements. The launch adds installation, fuel-type and recirculation flexibility, but the announcement provides no financial guidance or expected sales impact.
Analysis
This is not independently actionable for public equities: Bradford White/Laars is privately held, and a line extension in a fragmented replacement market is unlikely to alter industry earnings estimates. The relevant read-through is that compliance-ready, high-efficiency gas tankless products are becoming table stakes rather than a differentiated premium feature, raising the risk of incremental price competition among public HVAC/water-heating exposures such as A. O. Smith (AOS), Rinnai’s parent Rinnai Corp. (5947 JP), and Bosch’s private heating business.
Near term, the primary mechanism is channel rather than unit demand: a broader SKU can improve distributor shelf placement and contractor conversion in retrofit jobs, particularly where local emissions rules narrow product eligibility. That may modestly pressure AOS’s North American water-heater mix if competitors use compliant tankless offerings to win multi-unit light-commercial bids; however, AOS’s earnings sensitivity remains far more exposed to U.S. housing turnover, replacement volumes, steel/input costs, and China demand than to one competitor SKU.
Over 6-18 months, tighter NOx standards and utility efficiency incentives could shift value from conventional storage heaters toward condensing/tankless systems, benefiting component suppliers with stainless-steel heat-exchanger capacity and installers able to manage venting, gas-line, and recirculation complexity. The contrarian point is that retrofit economics can slow adoption: installation labor and infrastructure modifications often dominate equipment savings, leaving the addressable market dependent on rebates and regulation rather than advertised efficiency. Watch state incentive revisions, contractor-channel inventory data, and AOS commentary on tankless mix or gross-margin pressure; absent evidence there is no trade signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No immediate position: treat this as a competitive-intelligence datapoint, not an earnings catalyst, given the private issuer and low apparent revenue materiality.
- Add an alert for AOS quarterly disclosures: reassess if North American water-heater volume, tankless mix, or gross margin misses guidance alongside distributor inventory increases; that combination would support a 1-3 month tactical underweight versus XHB.
- Monitor California and other high-NOx-regulation-state rebate/mandate changes over the next 6-18 months. A broad incentive expansion would be a sector demand catalyst, but requires channel sell-through evidence before taking a directional AOS position.
- For Japan-listed exposure, monitor 5947 JP for North American tankless growth and margin commentary; only consider relative long 5947 JP versus AOS if U.S. tankless share gains are confirmed while AOS reports conventional-product mix pressure.
More News
- Australia’s central bank chief warns inflation risks materialising
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Jensen Huang says Nvidia will sell twice as many chips next year
- Waymo to launch robotaxis in Singapore, its first Southeast Asia market, by 2028
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations
- Selecting an AI Research Platform for Institutional Investors