
Circus Circus Las Vegas apuesta por la nostalgia, las ofertas al estilo de antaño y la diversión en familia para ofrecer más de Las Vegas por menos dinero
Source: PR Newswire
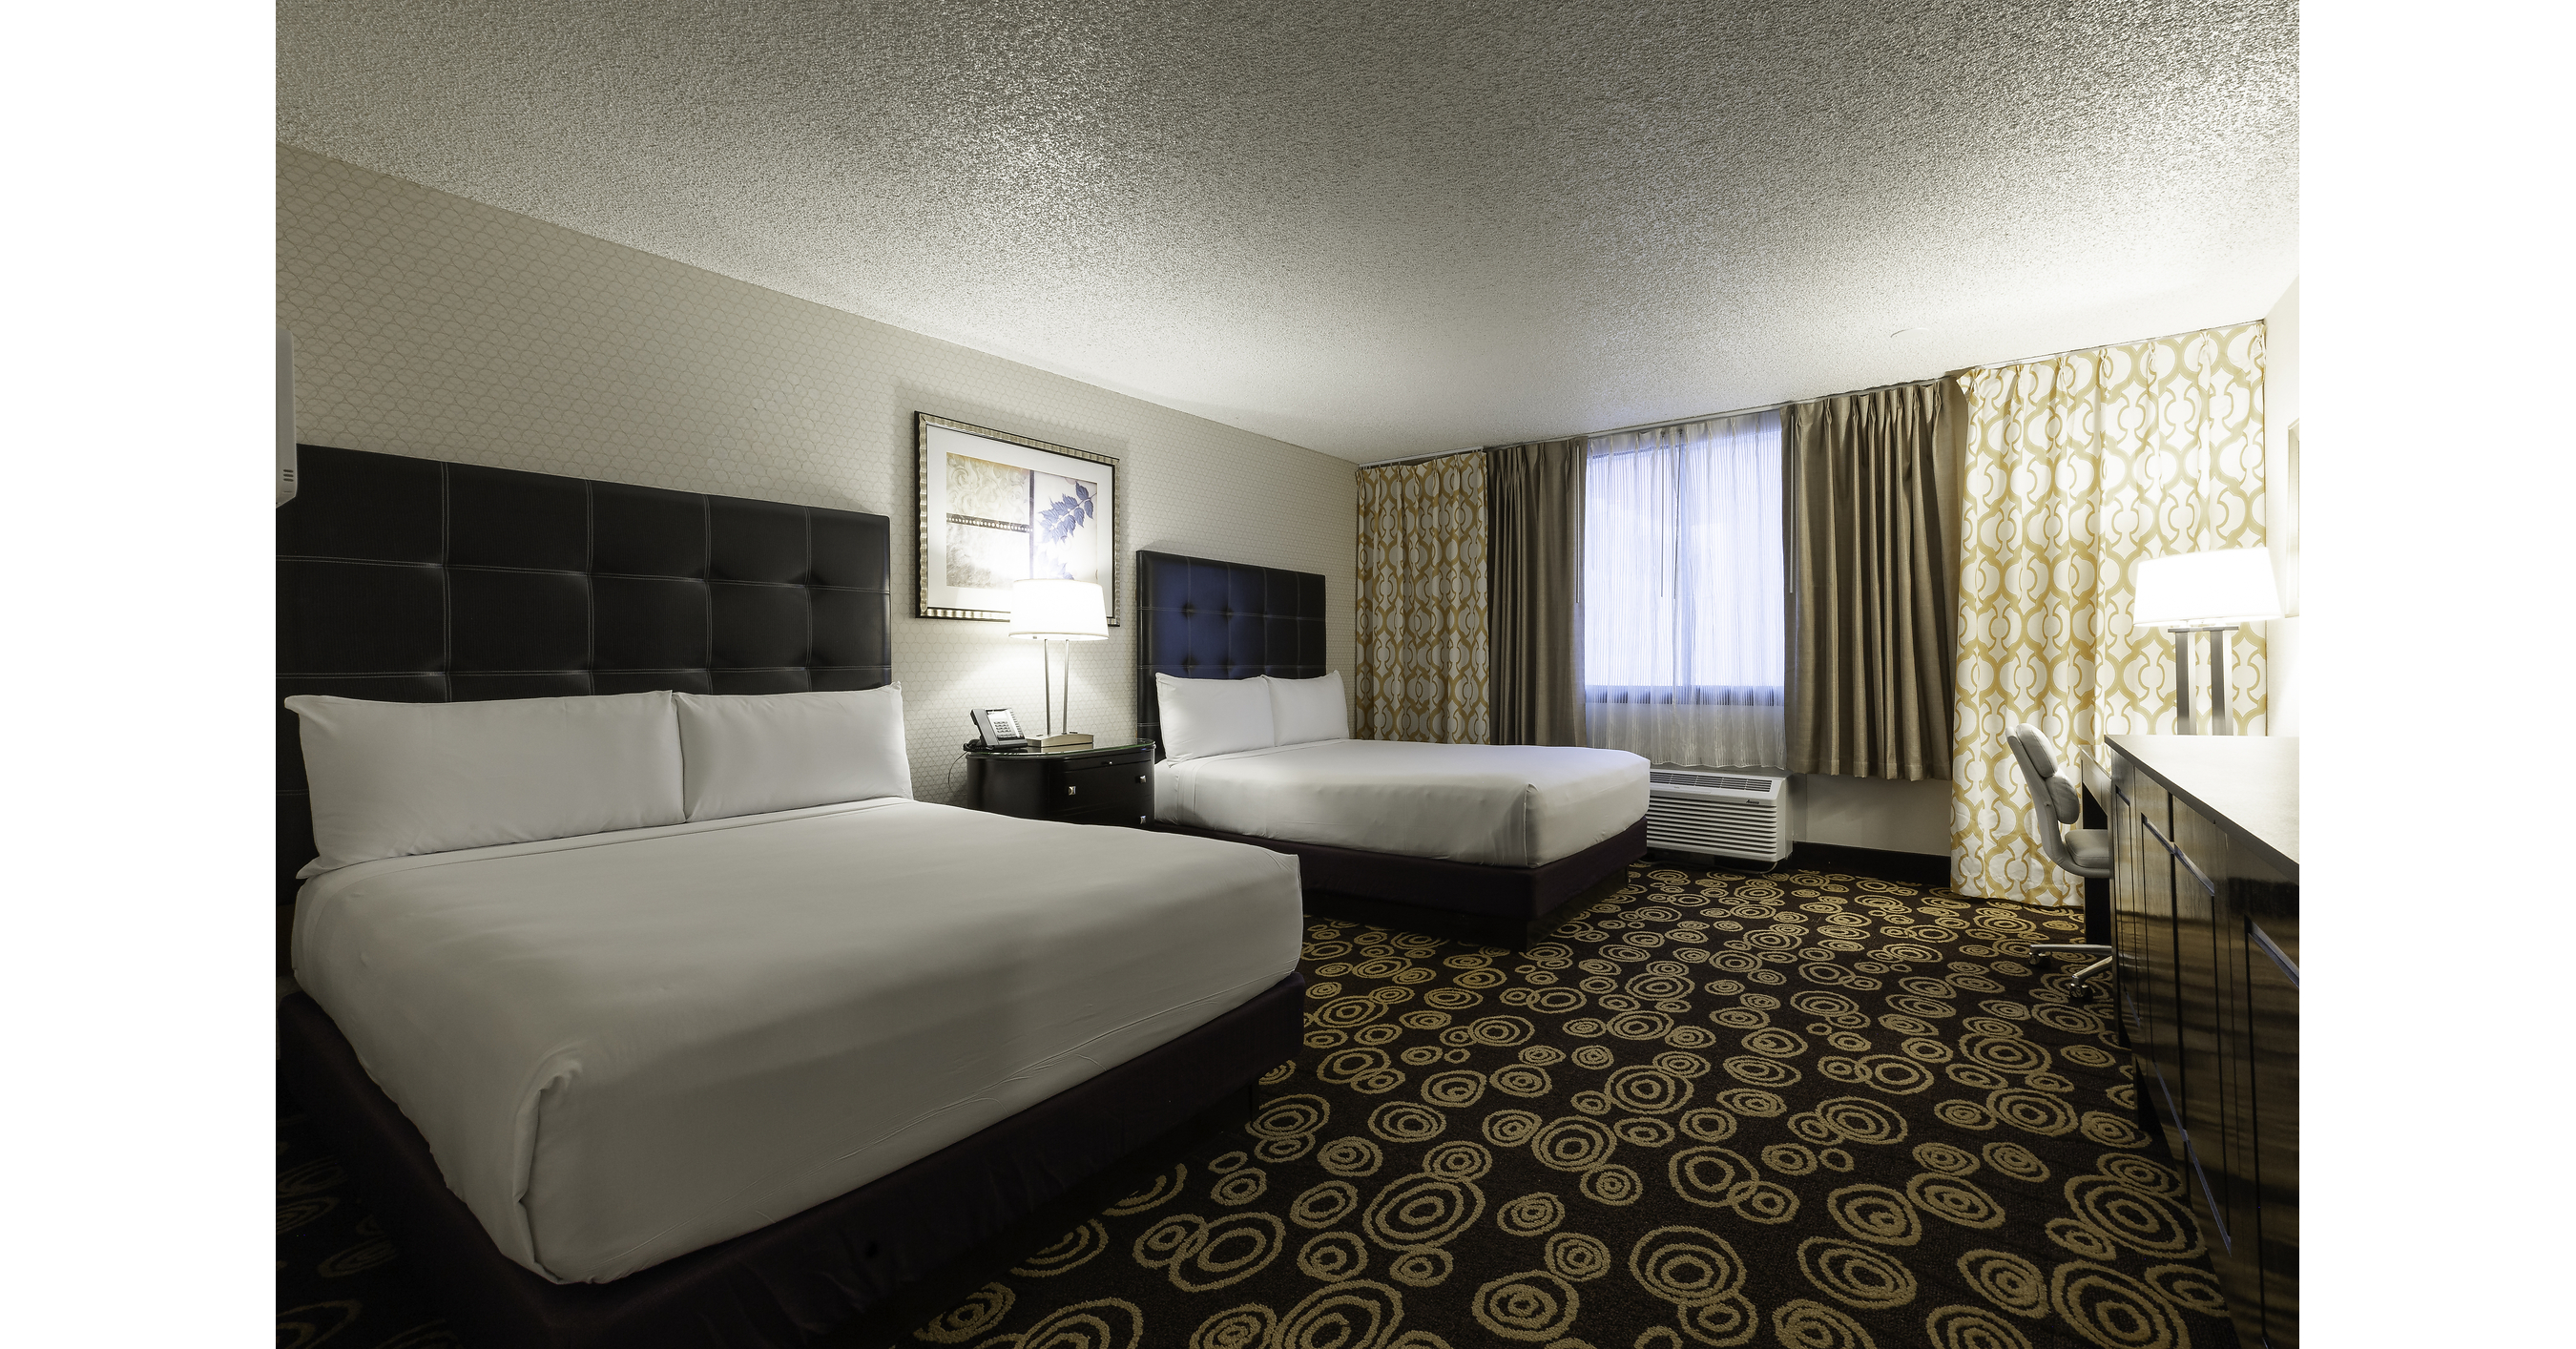
Circus Circus Las Vegas launched stay-and-play promotions through December 31, pairing room rates starting at $38.95, with no resort fee, with gaming, dining and Adventuredome incentives. Packages include $10 in slot play, a $60 buffet or bingo value, $120 in Adventuredome wristbands, and a $40 Midway game card; Nevada residents also receive 25% off Adventuredome wristbands. The privately held resort is positioning its roughly 4,000-room property around lower-cost, family-oriented Las Vegas entertainment, including $2 drinks and food offerings.
Analysis
This is a tactical occupancy-and-footfall yield-management initiative, not evidence of a durable change in Las Vegas demand. The relevant read-through is that a major Strip operator sees value in lowering the all-in trip cost and monetizing ancillary spend rather than relying on room-rate yield; that is modestly negative for RevPAR expectations at higher-priced, family-adjacent Las Vegas properties if copied. MGM Resorts (MGM) and Caesars (CZR) have greater exposure to resort-fee economics, premium food-and-beverage pricing, and convention/weekend mix, so a broad value pivot would pressure ancillary revenue per occupied room before it necessarily appears in headline occupancy data.
The more important second-order effect is segmentation: discounting can pull price-sensitive regional drive-in visitors away from off-Strip independents and local gaming operators, while providing limited substitution for luxury leisure demand. Red Rock Resorts (RRR) is the cleaner listed watchpoint because its Las Vegas locals franchise competes for discretionary gaming, dining, and family entertainment spend; however, the promoted property is privately held and the offer window is short, so there is no direct public-equity earnings signal yet. Watch Las Vegas visitor volume, airport passenger growth, weekend ADR/RevPAR commentary, and RRR same-store gaming revenue through the next two reporting cycles for confirmation.
Consensus may overinterpret highly visible low prices as a citywide demand warning. These packages may instead be economically rational during low-compression periods if incremental guests carry positive contribution margins across gaming and attractions, particularly where fixed operating costs are already incurred. The bearish thesis is falsified if MGM/CZR maintain or raise full-year Las Vegas RevPAR and property-level EBITDA guidance while promotional intensity remains isolated to lower-tier inventory; it is reinforced by sequential ADR cuts, rising promotional allowances, or softer casino-revenue trends over the next 1-3 months.
No immediate directional trade is warranted from a private operator's promotional release. The actionable signal is whether value-led offers spread into publicly reported Strip pricing and promotional metrics; that would create a more credible 6-18 month risk of lower Las Vegas margin capture as operators defend occupancy through lower all-in customer spend.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Maintain no new position solely on this release; set an alert for MGM and CZR third- and fourth-quarter commentary on Las Vegas ADR, resort-fee realization, promotional allowances, and property EBITDA margins.
- If MGM and CZR each guide to sequential Las Vegas ADR pressure or materially higher promotions, initiate a 1-3 month relative-value trade: short CZR / long MGM. CZR has greater balance-sheet sensitivity to a modest EBITDA shortfall; exit if CZR reaffirms Las Vegas EBITDA and deleveraging targets.
- Monitor RRR quarterly same-store casino and dining revenue for regional substitution. A sustained deceleration versus prior guidance would support a tactical underweight in RRR; do not act on a single month because local gaming results are highly calendar- and event-sensitive.
- For sector exposure, prefer MGM over CZR during any emerging value-war narrative: MGM's broader non-Las Vegas earnings base and asset-light fee streams provide relatively better downside insulation. Thesis risk is a strong convention and premium international-leisure recovery that restores Strip pricing power.
More News
- Your health insurance premiums may take a big jump in 2027 — here's why
- Nike falls to 13-year low. Why analysts don't think the selling is over yet
- California leads lawsuit against Trump fuel efficiency standards rollback
- Wall Street Week | Your Brain on AI, Rare Earth Race, College Enrollment Cliff
- Nike’s Worsening Slump Forces CEO to Rethink Turnaround
- US Payrolls Awaited While Investors Flee French Debt