
Ernest Health Announces Six-Hospital Inpatient Rehabilitation Facility Expansion Across North Carolina
Source: PR Newswire
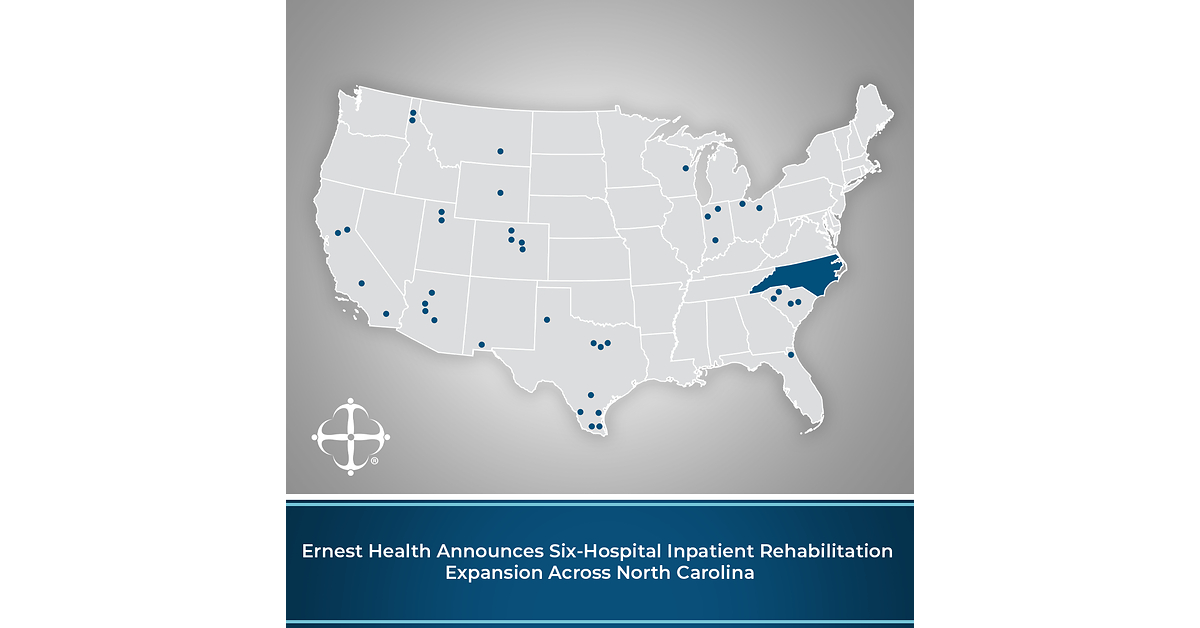
Ernest Health announced Phase 1 of a North Carolina expansion plan involving six freestanding inpatient rehabilitation hospitals in Winston-Salem, Mooresville, Gastonia, Hickory, South Asheville/Arden and Goldsboro. All six sites have been secured under development partner Summit Healthcare Group, positioning the company to advance through planning, permitting and regulatory review. Bed counts, opening dates and local clinical partnerships remain undisclosed, while Ernest said additional North Carolina markets are being evaluated for later phases.
Analysis
The investable read-through is competitive rather than a direct beneficiary trade: EHC and SEM face a localized referral-share and labor-cost challenge if the projects reach licensure and opening. New freestanding IRF capacity can pull high-acuity, commercially insured and Medicare Advantage discharges from incumbent hospital-based rehab units, while leaving hospitals with lower-margin skilled-nursing or long-stay patients. The greatest pressure should fall on operators with existing Carolinas exposure or dependence on acute-care referral partnerships; the effect on national earnings is likely immaterial initially but could matter for local census, payer mix and de novo return assumptions.
The announced footprint is not yet equivalent to funded beds or operating capacity. North Carolina’s regulatory, certificate-of-need, zoning and hospital-partnership processes remain the key gating items, and the absence of bed counts, capital commitments, lease terms and opening dates prevents a credible revenue or construction-spend estimate. Over the next 1-3 months, permitting filings, identified acute-care partners and disclosed bed counts are the relevant catalysts; without them, this is a strategic signal rather than an earnings event.
Consensus may overvalue the apparent speed implied by site control. Freestanding IRFs require sustained referral capture, specialized staffing and compliance with Medicare’s 60% rule; attractive hospitality features do not solve these operating constraints. Conversely, if incumbents have capacity bottlenecks in the Charlotte/Piedmont corridors, the expansion could validate unmet demand rather than create destructive competition, supporting EHC/SEM de novo valuation multiples rather than compressing them over a 6-18 month horizon.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No immediate position: the private sponsor/developer and missing bed, capex and timing data make this non-actionable for public-equity portfolios.
- Place EHC and SEM on a North Carolina capacity watchlist for the next 90 days; reassess only after bed counts, permits and acute-care referral partners are disclosed. A cluster of 40+ bed facilities near an incumbent market would justify modeling local census dilution and a tactical underweight in the more exposed operator.
- For a 6-18 month competitive-risk hedge, consider a small long EHC / short SEM pair only after mapping each company’s Carolinas facilities and payer exposure; EHC’s scale and de novo operating playbook could make it the relative winner if new capacity validates demand. Exit if regulatory approvals stall or regional IRF occupancy remains above roughly 80-85%, indicating supply remains constrained.
- Monitor CMS IRF reimbursement updates, Medicare Advantage authorization trends and rehabilitation labor inflation. A reimbursement cut, tighter MA utilization management or worsening therapist wage pressure would turn new supply from a share-gain opportunity into a margin-risk event for all IRF operators.
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- UK to refuel Saudi jets to help counter Houthi attacks
- +17% in a single session: This AI-picked stock catches a data-center breakout
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations
- Selecting an AI Research Platform for Institutional Investors