
FOTON Showcases Its Full Product Portfolio in Hannover, Advancing a New Model for the Global Expansion of China's Commercial Vehicle Value Chain
Source: PR Newswire
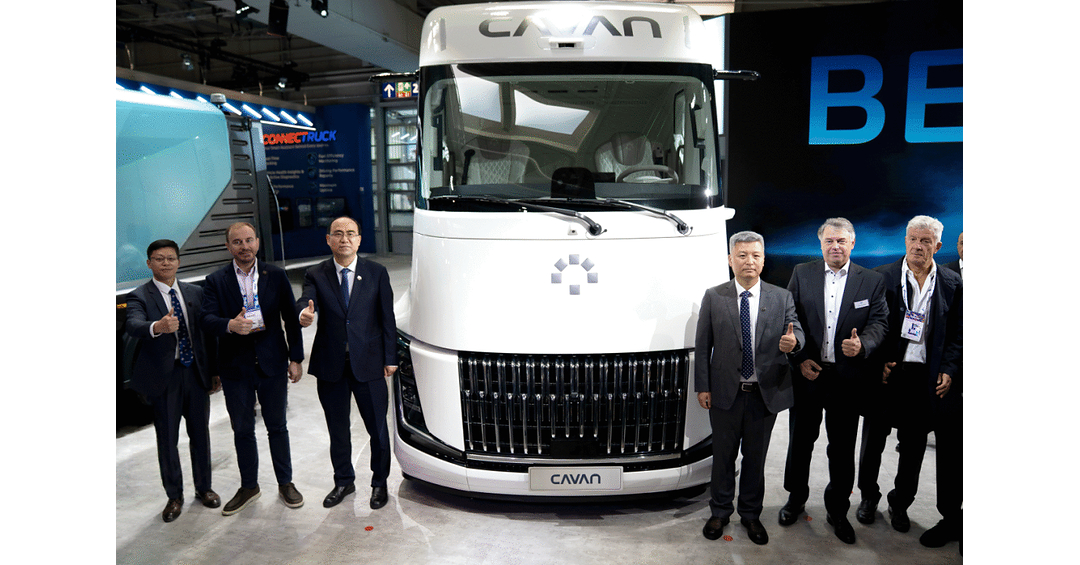
BAIC FOTON showcased its full commercial-vehicle portfolio at IAA Transportation 2026 and delivered its 13 millionth vehicle globally, the GALAXUS 9. The company unveiled the CAVAN BEACON zero-carbon heavy truck, offering over 600 km of battery-electric range, over 1,000 km of hydrogen range and 20%-80% megawatt charging in 18 minutes. FOTON targets new-energy vehicles at 50% of sales and international markets at 40% by 2030, supported by expansion into nearly 20 European markets, more than 300 service outlets and local assembly by 2028.
Analysis
This is strategically negative for European truck incumbents at the margin, but not yet an earnings event. A localized Chinese heavy-truck entrant can use lower component costs and vertically integrated electric drivetrains to compress the total-cost-of-ownership premium historically earned by Daimler Truck (DTG), Traton (8TRA.DE) and Volvo (VOLV-B.ST), particularly in fleet tenders where charging access and financing are bundled. The likely first effect over the next 6-18 months is higher selling expense, warranty provisioning and price competition rather than immediate unit-share loss; European fleets have long replacement cycles and remain highly sensitive to service-network reliability and residual values.
CVGI is not a supported read-through from the available information: there is no verified sourcing relationship or disclosed content-per-vehicle opportunity. The potential upside is that Chinese OEM localization in Europe could expand demand for seats, interiors and cab components, but this requires an announced supply award and local production qualification before it is investable. The contrarian point is that multi-powertrain product breadth can be economically dilutive: supporting battery, swap, hybrid and hydrogen architectures raises inventory, engineering and aftersales complexity, while European zero-emission adoption is constrained more by grid/depot infrastructure and fleet financing than by vehicle specifications.
Near term, treat the announcement as a competitive-intelligence catalyst rather than a directional equity catalyst. The thesis becomes material if European registrations, fleet-order disclosures, localized assembly commitments, or component sourcing contracts demonstrate that the entrant is converting showcase visibility into subsidized volume; absent those signals, incumbent installed-base service revenue and dealer networks should defend profitability better than headline product comparisons imply.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No immediate CVGI position: set an alert for a disclosed FOTON/CVGI supply agreement, awarded annual revenue, and European manufacturing location. Consider a long only after verified contracted revenue exceeds a meaningful share of CVGI segment sales and management quantifies tooling/capex requirements.
- Monitor a 6-18 month relative-value setup: long DTG or Volvo / short a European commercial-vehicle peer only if Chinese entrants begin winning European fleet tenders without broad incumbent price concessions. Falsify the incumbent-defense thesis if order intake, adjusted EBIT guidance, or service-margin commentary deteriorates for two consecutive quarters.
- For a higher-risk competitive-disruption basket, avoid preemptively shorting DTG, Traton or Volvo on this release alone. Reassess if European registration data show sustained Chinese-brand share gains above 2% in heavy-duty BEVs, accompanied by a 200bp-plus decline in incumbent order-book pricing or margin guidance.
- Watch European megawatt-charging deployment and hydrogen-fueling economics over the next 12 months. Faster-than-expected depot charging buildout would shift competition toward vehicle acquisition price and favor low-cost Chinese OEMs; delayed infrastructure rollout favors incumbents with service, leasing and diesel installed-base cash flows.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target