
CLF Ships Taiwan's First 5000-Ton Injection Molding Machine, Its Largest in 60 Years, to a Top-Tier US Logistics Supplier
Source: PR Newswire
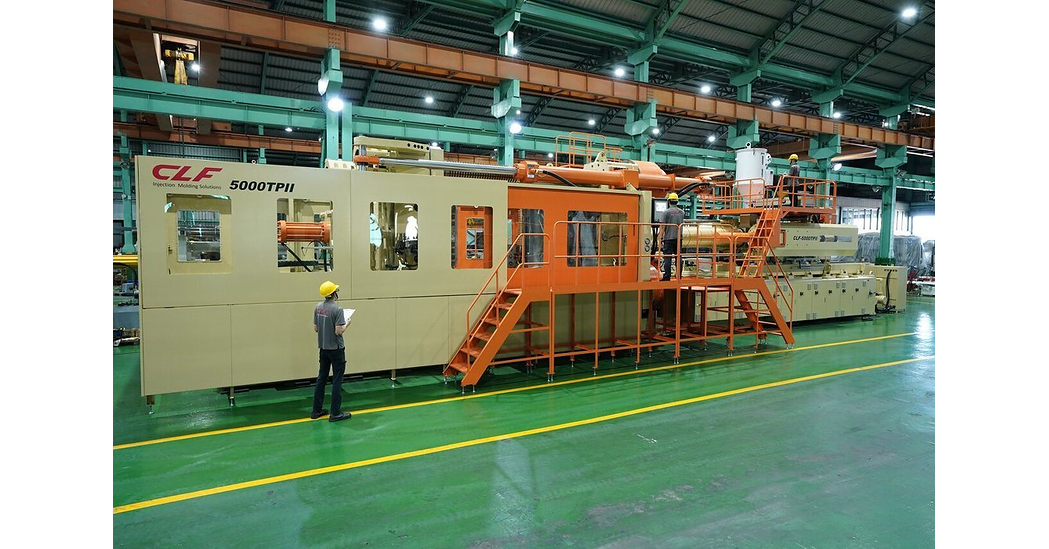
CLF shipped Taiwan’s first 5,000-ton ultra-large two-platen injection molding machine (CLF-5000TPII), CLF’s largest in 60 years, to a top-tier US logistics/retail equipment supplier. The two-platen design is 15%–20% shorter than an equivalent toggle machine and targets 20%–50% lower power consumption in volume production versus conventional hydraulic drives. The release frames the move as supporting low-carbon transformation and expanding capacity for North America logistics bulk bin production.
Analysis
The investable signal is not the shipment itself; it is whether large industrial buyers are starting to pay for lower footprint and lower electricity intensity in heavy equipment. If that trend broadens, the second-order winner is the installed-base replacement cycle for older toggle/hydraulic platforms, because the economic case shifts from pure capacity expansion to OPEX payback. That matters most in logistics, food handling, and packaging where power costs are visible and equipment downtime is expensive.
For public markets, there is no clean direct ticker expression here. TSM is not a meaningful proxy for this thesis, and the release is too idiosyncratic to translate into an earnings revision for any listed name. The likely winners are private industrial machine builders and adjacent Taiwanese precision machining suppliers; the losers are legacy OEMs with slower, less energy-efficient architectures that may have to discount to defend share.
The key catalyst is not days but 1-3 quarters: a second or third similar U.S. order, backlog commentary, or proof that buyers are choosing two-platen machines over cheaper alternatives because the power savings offset higher capex. Falsifiers are simple: if follow-on orders do not appear, if pricing is concessionary, or if end-market logistics volumes weaken, this remains a branding win rather than a structural demand inflection. Over 6-18 months, only a broader capex cycle or regulatory push on industrial energy use would make this actionable for listed industrials.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate position in CRMT, TSM, or WWRL on this release; the revenue linkage is too indirect and this is not a public-earnings catalyst.
- Add CLF-style heavy-tonnage, energy-efficient machinery demand to the 1-3 month watchlist; only consider a listed industrials expression if follow-on orders or backlog growth confirm the theme.
- If U.S. logistics and packaging capex data improve, consider a small long in XLI as a broad confirmation trade, but only after independent evidence that energy-saving machinery is converting into recurring orders.
- Set a falsifier alert: if no additional large-tonnage orders are disclosed within 2 quarters, or if quoted pricing is discount-driven, treat the thesis as marketing noise and stay flat.
More News
- ‘How many canaries have we killed in the coal mine?’ — Wall Street debates if the latest AI bubble warnings are another head fake or the real thing
- TSMC posts a sixth straight record profit but turns cautious on 2027
- TSMC: The AI Boom Is Bigger And Longer Than Expected
- Elon Gets the Headlines; These Stocks Could Get the Gains
- TSMC: The AI Cycle Just Sent Another Signal
- As Chip Stocks Sell Off, This Is the Flight-to-Safety Play I Would Choose