
Maggie Frerejean-Taittinger Nominated for Wine Enthusiast's 2026 Innovator of the Year Award for French Bloom's leading role in the evolution of the non-alcoholic landscape
Source: PR Newswire
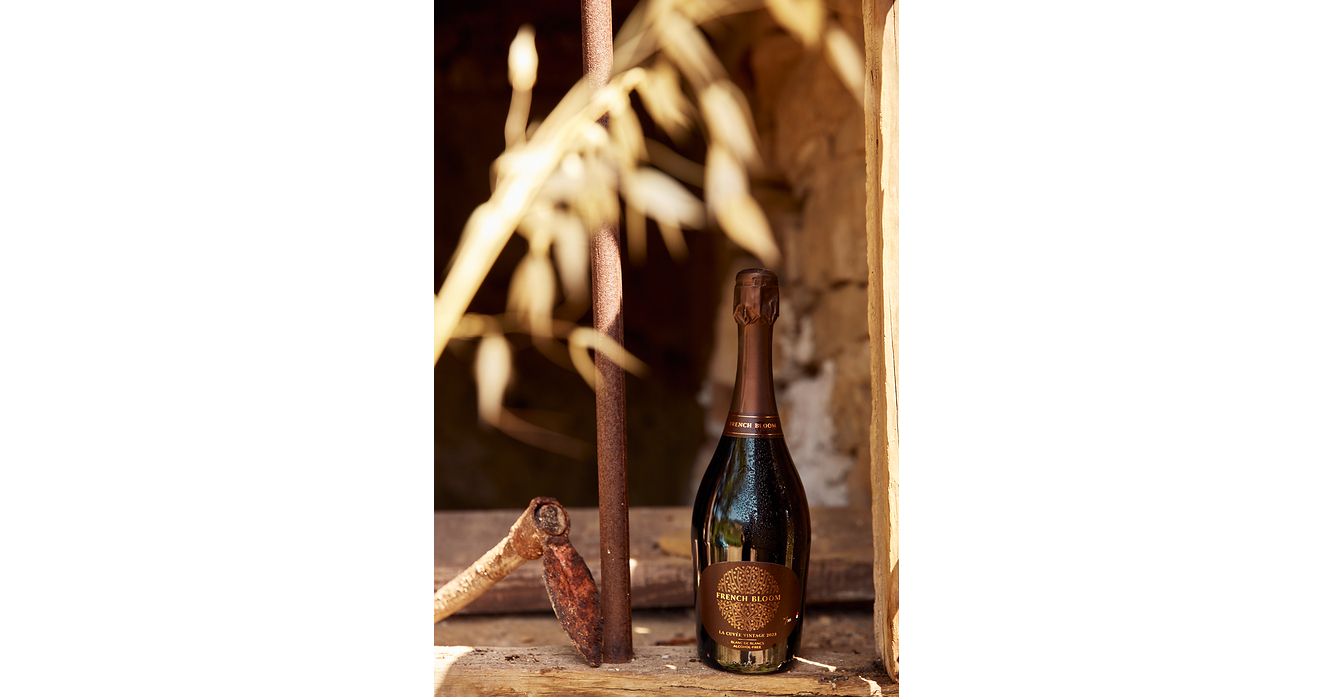
French Bloom founder Maggie Frerejean-Taittinger was nominated for Innovator of the Year in Wine Enthusiast's 2026 Wine Star Awards, recognizing the company's role in premium alcohol-free sparkling wine. The company says it has doubled growth annually since its 2019 founding, expanded to more than 70 countries since 2021, and secured luxury distribution including Formula 1, Air France La Première, Soho House and Auberge Collection. The nomination reinforces French Bloom's brand positioning in the growing non-alcoholic luxury beverage segment but is unlikely to have material public-market impact.
Analysis
This is not a near-term earnings catalyst for LVMH (MC); the relevant read-through is strategic optionality in a premium adjacency where a small minority investment can create disproportionate value if the brand establishes pricing power and distribution scarcity. The key financial question is whether alcohol-free sparkling is incremental to Champagne occasions or cannibalizes Moët/Veuve Clicquot consumption. At luxury venues, the likely initial effect is mix-accretive: it allows a single table to maintain a prestige consumption ritual while broadening the addressable guest count, with little incremental fixed-cost burden for LVMH's existing hospitality and distributor relationships.
The more material 6-18 month implication is competitive defense. Pernod Ricard (RI.PA), Rémy Cointreau (RCO.PA), and Diageo (DEO) face a weak position if premium zero-proof becomes a branded luxury category rather than a low-price functional substitute; their portfolios lack an equally visible luxury sparkling platform. However, the press-release growth claims are not independently useful without French Bloom revenue, gross margin, repeat-purchase data, and the economics of its long-term sports/hospitality agreements. Award recognition itself should not change MC valuation or estimates.
Contrarian view: investors may overstate the health-and-wellness benefit for global spirits groups. Zero-proof growth can be revenue-dilutive if it substitutes for high-margin Champagne and cognac at premium occasions, while production complexity and small-scale sourcing pressure gross margin. The investable signal would be evidence that MC can cross-sell zero-proof consumers into its broader luxury ecosystem, rather than merely purchase external growth at a premium multiple.
Near term, treat this as a channel-data watch item, not a trade trigger. A measurable acceleration in premium on-premise placements, airline/hotel reorders, or broader Moët Hennessy distribution over the next two reporting periods would support a modest uplift to the quality of MC's Wines & Spirits growth mix; flat reorder rates or heavier discounting would falsify the premiumization thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No standalone MC trade on the nomination. Maintain existing MC exposure; require evidence of material distribution expansion or disclosed financial contribution before attributing any earnings value to the stake.
- Create a 1-3 month diligence alert around MC results: monitor Wines & Spirits organic growth, Champagne pricing versus volume, and management commentary on alcohol-free portfolio rollout. A widening price/volume divergence without margin pressure supports the incremental-demand thesis.
- For a relative-value expression only after data confirmation, consider long MC / short RI.PA over 6-12 months if MC demonstrates premium zero-proof distribution through its luxury channels while RI.PA remains dependent on conventional spirits volume recovery. Exit if MC Wines & Spirits margin declines despite positive organic sales growth.
- Monitor DEO and RCO.PA for premium zero-proof acquisitions or partnership announcements; such actions would reduce MC's first-mover advantage and could signal that category economics are becoming strategically relevant rather than promotional.
More News
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Paramount agrees invest $1.5 billion in domestic movies and create a board for editorial independence at CNN, CBS as part of deal for Warner Bros.
- World Leaders Converge on United Nations General Assembly
- Paramount and state AGs will settle lawsuit, allowing Warner Bros. merger to proceed, reports say
- Here's who we know is going to the Trump-Xi dinner so far
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Software for Buy-Side Teams: Build the Research Stack
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit