
Renova Technology Launches Renova 360
Source: PR Newswire
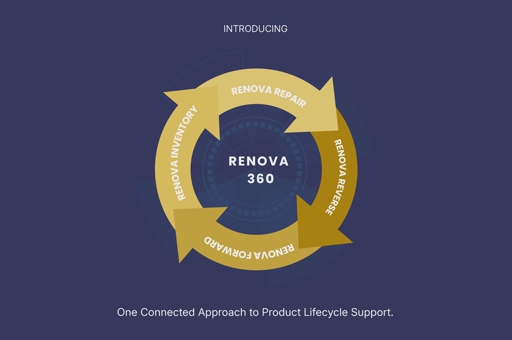
Renova Technology launched Renova 360, combining repair, reverse and forward logistics, inventory management, and product-lifecycle support for enterprise customers under one provider. The company says same-facility replacement shipping and RMA repair can reduce lead times, costs, and spare inventory tied up in transit; the service is available now. The launch coincides with Renova’s 30th year and a record year of growth, though the article provides no financial figures.
Analysis
The launch is strategically coherent but not, on the available evidence, an investable catalyst: Renova is private and the announcement provides no contract wins, revenue contribution, customer retention data, or capital requirements. The economic opportunity is to capture more of each OEM’s service and returns workflow, while reducing handoffs that delay replacement and repair. If customers consolidate vendors, specialized repair/logistics providers could gain share; OEMs could benefit from lower downtime and less fragmented spare-parts handling. The countervailing effect is that same-day exchange and broader inventory management may shift working-capital and inventory-obsolescence risk toward the service provider unless contracts price those risks appropriately.
The near-term signal is mainly commercial positioning, not proven earnings acceleration. Over 1–3 months, evidence to watch is whether Renova discloses customer additions, expanded programs, or measurable utilization of the new packages. Over 6–18 months, the thesis depends on repeatable operating economics across long-lifecycle equipment—not simply bundling more services. Large contract manufacturers and electronics-services firms such as Jabil (JBL), Flex (FLEX), and Celestica (CLS) offer adjacent public-market exposure, but this announcement does not establish that Renova is taking share from them. Contrarian point: same-facility integration may improve cycle times, yet customers may retain multiple providers to preserve negotiating leverage and resilience. No direct trade is warranted absent evidence of material scale.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade on the announcement alone: Renova is not a listed issuer in the supplied identity data, and no public-company earnings linkage or contract value is disclosed.
- Treat JBL, FLEX, and CLS only as broad adjacent-sector watchlist names, not as confirmed winners or losers. Reassess only if evidence shows material customer outsourcing or share shifts into repair, reverse logistics, or configure-to-order services.
- Monitor for customer/program wins, contract duration and pricing, inventory ownership and obsolescence terms, service-level performance, and utilization. These determine whether added services create attractive recurring economics or merely add working-capital and execution burden.
- Falsify the growth thesis if follow-up evidence shows limited adoption, no incremental customer programs, worsening delivery/service metrics, or inventory exposure that is not compensated by contract terms.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
- Microsoft's Big Bets on AI Start to Pay Off
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off