
Humanity propose l'analyse de l'âge biologique aux États-Unis via questhealth.com
Source: PR Newswire
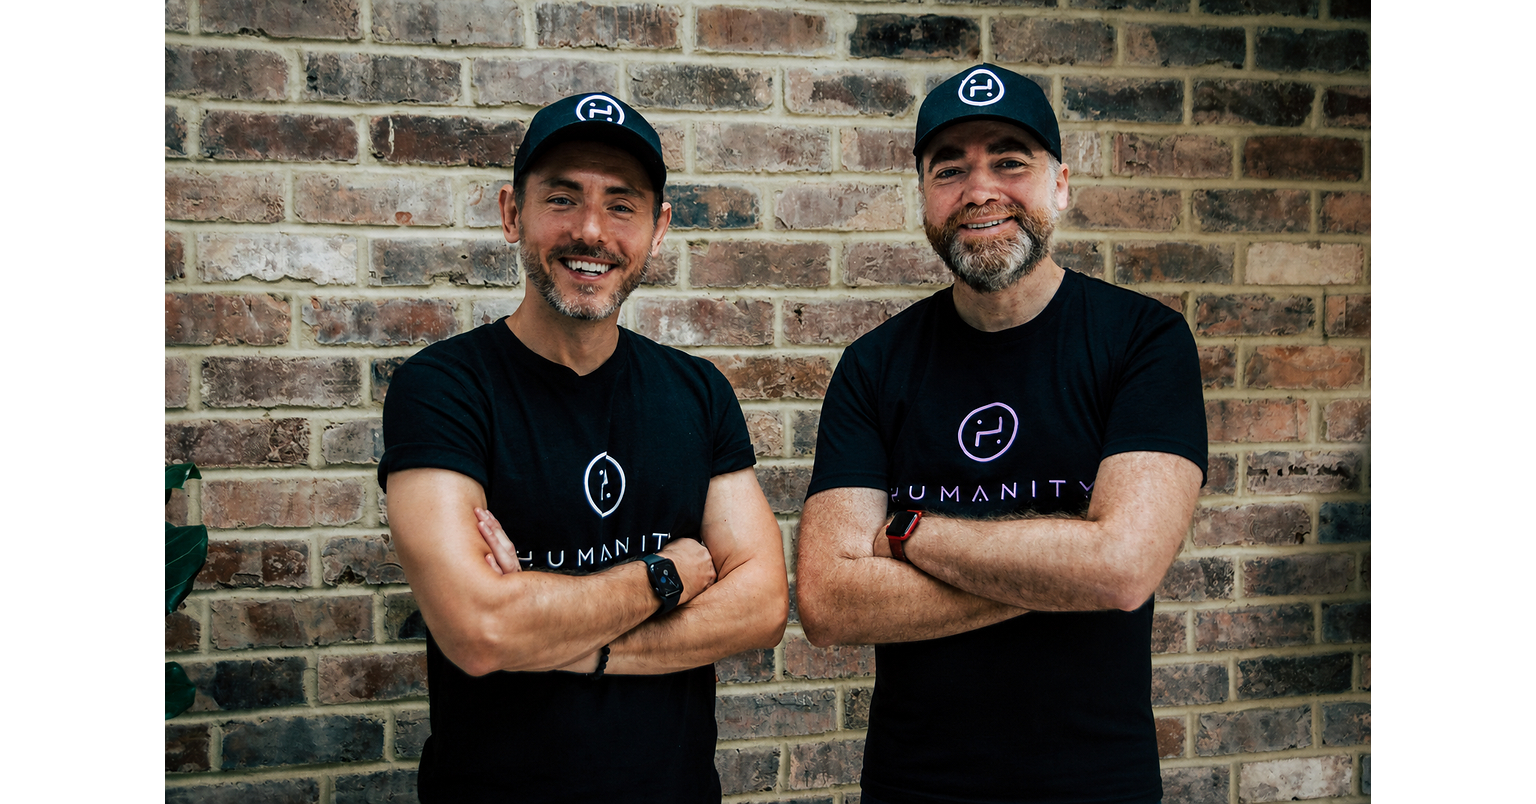
Humanity Biological Age is now available to U.S. consumers via Quest’s questhealth.com, purchasable as a $29 add-on on select health profile tests (e.g., Elite, male/female, Fitness Profile—Elite) with no additional blood draw. The biologically validated model provides an estimated biological age and “age difference” from chronological age, derived from routine biomarker lab results, with guidance on the systems and lifestyle factors influencing the score. The launch expands Humanity to five countries and is framed by both firms as enabling more proactive, prevention-focused health monitoring, though Quest notes no refunds for third-party (Humanity) reports.
Analysis
DGX is being used as a distribution layer for a niche wellness product, which matters more strategically than financially. The economics look modest on the surface, but the real upside is in higher consumer engagement: if this add-on lifts repeat testing cadence from annual to semiannual, it can improve utilization of Quest’s existing draw network with little incremental capex. That is the kind of mix shift the market often underappreciates because it shows up first in order frequency and customer retention, not headline revenue.
The competitive implication is that Quest is trying to own the consumer-facing layer while outsourcing the IP to a third party. That is a defensible model for now, but not a moat: Labcorp, at-home diagnostics, and wellness apps can likely replicate similar add-ons if the conversion economics prove real. The second-order risk is that the category becomes commoditized fast, leaving Quest with distribution but no pricing power beyond a small attachment fee.
Near term, the stock reaction should be limited unless management later discloses meaningful attach rates or repeat testing lift. Over 1-3 months, the catalyst is whether questhealth traffic and consumer-test mix improve; over 6-18 months, the thesis only matters if consumer-directed testing becomes a larger share of DGX revenue and supports multiple expansion. The main falsifier is evidence that this is just a novelty add-on with no incremental order frequency or retention benefit.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade in DGX; treat this as a watch item until Quest discloses attach rate and repeat-order data over the next 1-2 quarters.
- If DGX sells off on the headline, consider a small tactical long for 1-3 months; the upside is modest multiple support from consumer mix optionality, but only if consumer traffic data inflects. Exit if there is no sequential uplift in consumer testing volume at the next print.
- Relative-value idea: long DGX / short a broader healthcare services basket only if you want to express the thesis that consumer-direct diagnostics gets incremental share; keep size small because the revenue contribution is likely immaterial in the near term.
- Do not use options here unless implied vol is unusually cheap; the event is more a strategic option on consumer engagement than a near-term earnings catalyst.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand
- Schott Pharma drops after Deutsche Bank downgrades on demanding valuation
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Research Agent?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction