
Midea präsentiert auf der IFA 2026 seine Vorreiterrolle bei R290 und nachhaltige HVAC-Innovationen
Source: PR Newswire
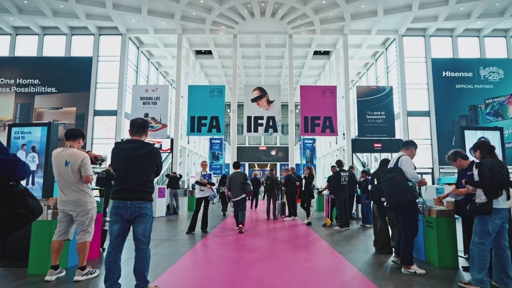
Midea showcased R290-based HVAC, heat-pump and home-energy-management products at IFA 2026, highlighting more than 10 million R290 air conditioners sold globally since 2018 and an estimated 5.2 million tonnes of CO2e emissions avoided. Its R290 technology is claimed to deliver roughly 10% higher energy efficiency, while the new Raynor Pro heat pump maintains 100% heating capacity at -25°C and is rated to operate down to -40°C. The company also introduced award-winning VitaBreeze air-conditioning technology and MHELIOS, a German EnWG §14a-compliant system integrating EV charging, heat pumps, solar and battery storage to optimize consumption against dynamic power prices.
Analysis
This is strategically more relevant for European HVAC pricing than for Midea’s near-term earnings. R290 commercialization shifts value from the refrigerant itself toward certified safety architecture, installer training, and service networks; incumbents with dense European channels—Daikin (6367 JP), Carrier (CARR), Trane (TT), and NIBE (NIBE-B SS)—retain an advantage where permitting, liability, and retrofit complexity determine conversion. Midea’s likely wedge is lower installed cost in constrained urban housing, which could pressure entry-level heat-pump ASPs before it materially displaces premium brands.
The non-obvious beneficiary is residential energy-management integration rather than standalone HVAC. Dynamic-tariff optimization increases the economic value of heat pumps, EV charging, batteries, and solar operating as one controllable load; SMA Solar (S92 GR) and inverter/storage peers could benefit if German grid-flexibility rules and retail tariff adoption accelerate. Conversely, HVAC manufacturers without credible controls ecosystems risk becoming hardware suppliers with lower gross margins as energy orchestration becomes the customer interface.
Near term, this is not a trade catalyst: the claims are company-supplied, lack pricing, order intake, certification status, and European channel commitments, and product rollout appears staggered. Over 6-18 months, monitor EU F-gas implementation, R290 installation standards, German heat-pump subsidy policy, and winter demand; any safety incident, installer bottleneck, or subsidy retrenchment would slow adoption and preserve incumbent pricing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No immediate directional position on the release; set an alert for Midea (000333 SZ) disclosures of European HVAC revenue, heat-pump order growth, and gross-margin progression over the next 2-4 quarters. A credible thesis requires evidence that low-cost hardware is converting into profitable installed-system share.
- Watch-list pair for a 6-12 month regulatory catalyst: long SMA Solar (S92 GR) / short a broad European HVAC proxy only after evidence of accelerating German dynamic-tariff enrollment and residential battery attachment. Thesis fails if subsidy cuts reduce total heat-pump installations or grid-interoperability standards fragment adoption.
- Maintain caution on premium European heat-pump OEM multiples, particularly NIBE (NIBE-B SS), if lower-cost indoor/retrofit systems begin appearing in distributor checks. Initiate a relative short only if quarterly pricing or gross margin weakens while unit growth remains positive—evidence of competitive mix pressure rather than cyclical demand softness.
- For CARR and TT, treat R290 adoption as a channel-defense test rather than an immediate earnings risk; reassess long exposure if European residential share loss coincides with rising warranty/service costs. Their installed base and service attach should offset hardware price pressure unless low-cost entrants gain installer trust.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- American embassies tighten security as Iran threat warnings intensify ahead of U.S. midterm elections
- Saudi-led coalition says it intercepted Houthi ballistic missiles targeting Saudi cities
- Biotech stocks are surging. How investors can play the new drug innovation boom
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market