
Micron: More For Longer
Source: seekingalpha.com
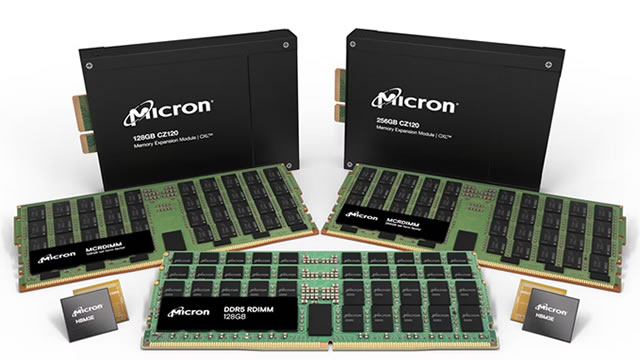
Micron was upgraded to Strong Buy as AI-driven demand makes memory a strategic bottleneck. Its September 30 results beat guidance, with Q4 revenue of $54.23B and non-GAAP EPS of $33.42; management expects sequential growth to continue in FY2027. Strategic Customer Agreements cover over 35% of revenue through 2030, with binding commitments, cash deposits and contractual price floors supporting margins.
Analysis
Do not underwrite the bullish upgrade from this excerpt yet: the reported $54.23B quarterly revenue and $33.42 non-GAAP EPS look materially inconsistent with Micron’s scale and require confirmation against the company’s earnings release and SEC filing. The claimed customer agreements, coverage, deposits, and price floors also need primary-source verification; if misstated, they materially overstate earnings visibility. If verified, committed demand could lower downside volatility and support a higher through-cycle multiple, but it would not eliminate memory cyclicality. The second-order risk is that capacity and capital are pulled toward contracted AI-related products, leaving conventional DRAM/NAND more exposed to oversupply or weaker pricing; customer concentration and contract terms could also constrain Micron’s flexibility. Over days, the key risk is a credibility-driven reversal if the figures do not reconcile. Over 1–3 months, verify guidance, contract disclosures, and realized product pricing. Over 6–18 months, the thesis depends on AI infrastructure demand translating into sustained shipments and returns on capacity investment—not just bookings. A bullish thesis is weakened by lower-than-guided sequential revenue, deteriorating memory pricing, or evidence the agreements lack enforceable floors; confirmation in filings and subsequent results would strengthen it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.70
Ticker Sentiment
Key Decisions for Investors
- Do not chase MU on this excerpt alone. First reconcile the cited results and FY2027 outlook with Micron’s official release, filing, and call transcript; treat the figures and agreement terms as unverified until then.
- If primary sources confirm the claims, consider a staged long MU rather than a full-size immediate entry, with reassessment at the next earnings update. Track HBM/DRAM pricing, shipment growth, and realized margins as thesis tests.
- Watch for a relative-value opportunity between MU and broader memory exposure only after checking current valuation, positioning, and product mix; the article alone does not support a specific pair trade.
- Falsification triggers: official results materially differ from the excerpt, guidance no longer indicates sequential growth, or memory pricing and margins weaken despite claimed customer commitments. In that case, avoid adding and reassess downside exposure.
More News
- Cramer: Starbucks tells me Chipotle takeover won't happen and that's good for the stock
- Micron makes a statement with the latest clue about its cash windfall
- Why is SanDisk stock sliding today?
- CXMT: How big is its market threat to Samsung, SK Hynix and Micron?
- Stocks making the biggest moves midday: eBay, Sandisk, Meta Platforms, IonQ, Lumentum & more
- Micron Q4 FY2026 Review: The Earnings Did The Work, The Multiple Did Not
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Index and ETF Holdings Data for AI Research
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)