
Veridian Credit Union launches Money Moves to help members build financial confidence, achieve goals
Source: PR Newswire
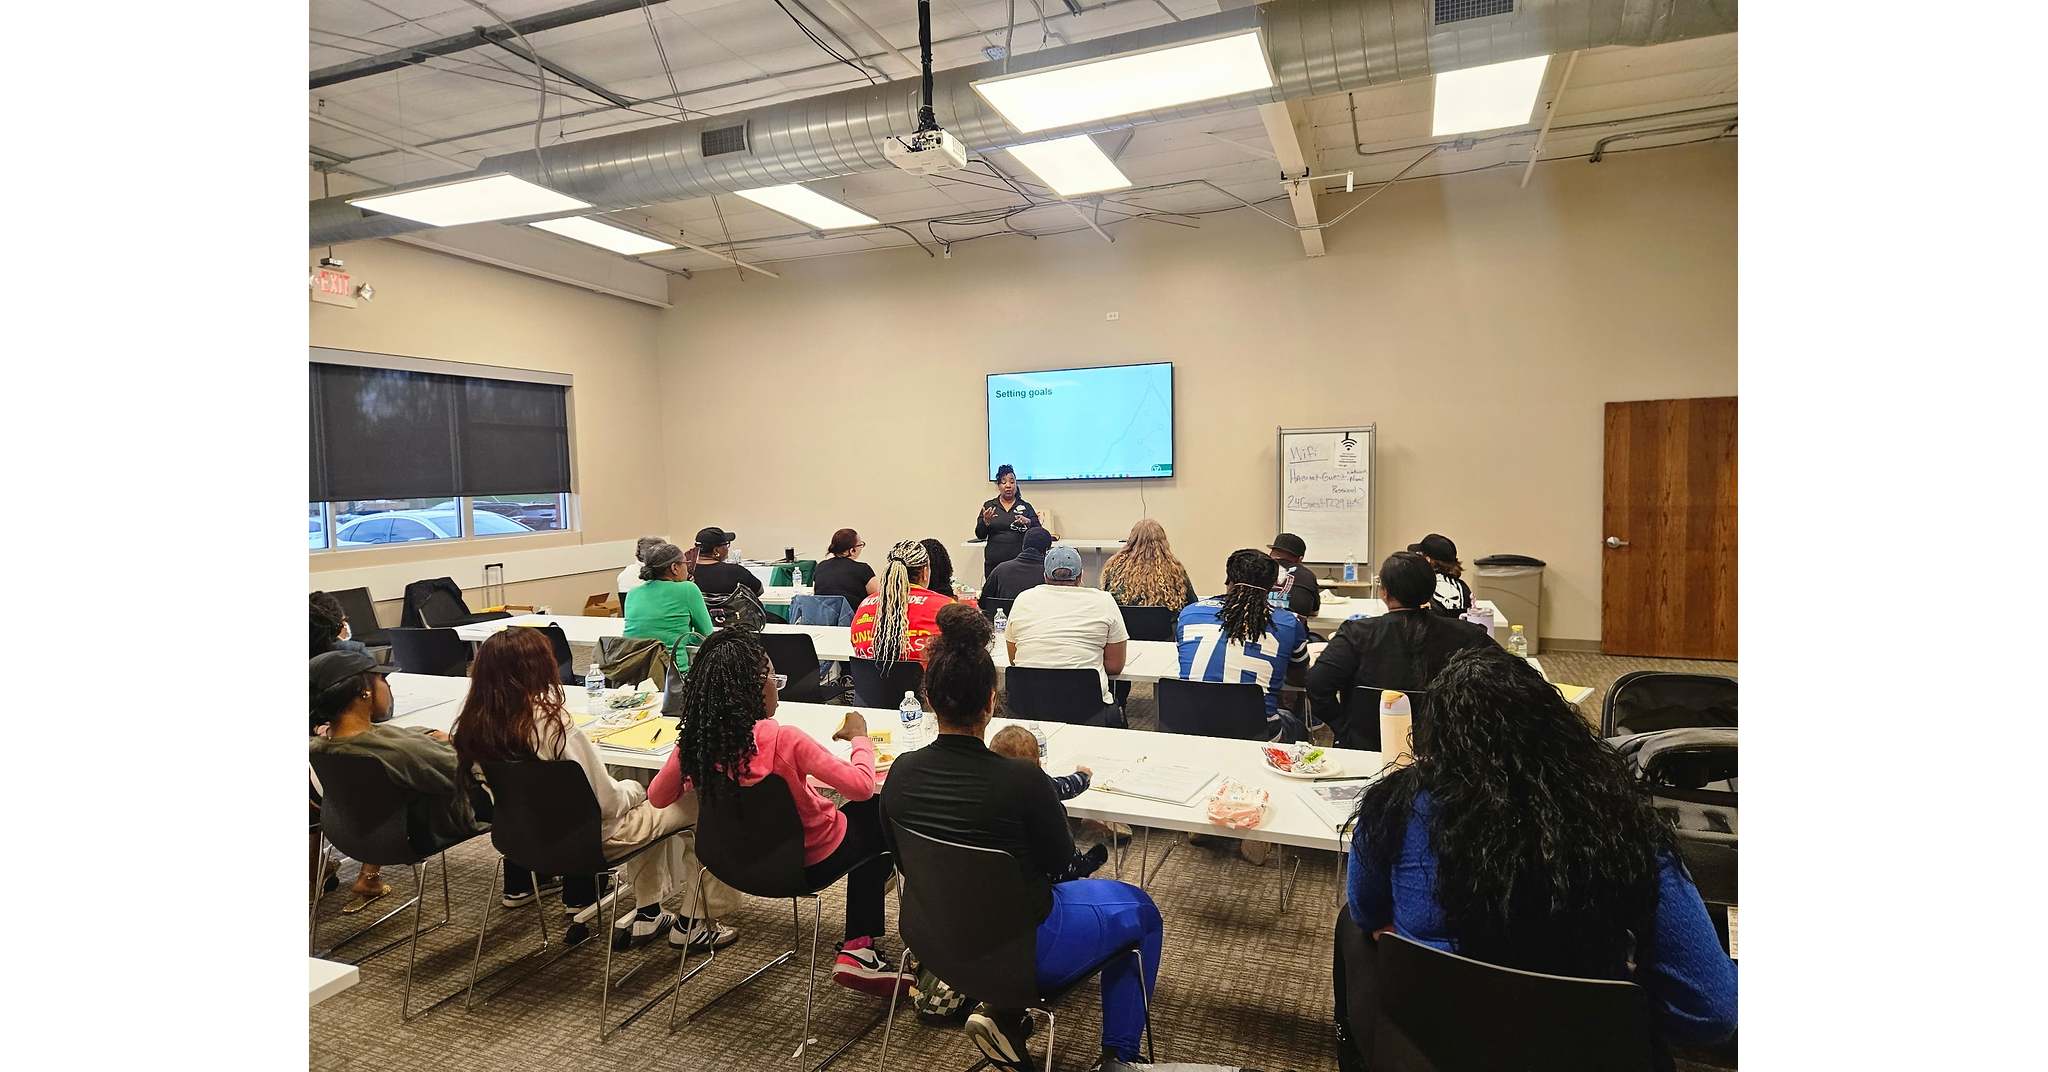
Veridian Credit Union launched “Money Moves,” a free financial empowerment program combining education, personalized coaching, and incentives to help members save more and reduce debt. Participants who complete the program may receive a $250 matching incentive usable toward a secured credit card, starter CD, or debt repayment. Program sessions begin mid-September in Cedar Rapids, Waterloo, and Omaha, and Oct. 1 in Des Moines, with registration required.
Analysis
This reads as a member-retention and relationship-deepening tactic, not a meaningful earnings lever. The economic value is in lowering churn, improving deposit stickiness, and nudging a subset of borrowers toward secured credit products that are easier to underwrite and cross-sell; the $250 carrot is too small to matter on its own, but it can improve activation and completion rates if paired with coaching. For public comps, the most relevant read-through is not to Veridian itself but to any bank or CU competing for primary financial relationships among younger, lower-balance households.
Second-order, if this model works at scale, it is modestly bearish for subprime/near-prime lenders over 6-18 months because better credit habits reduce roll rates and future late-stage delinquencies. That said, a local program does not move national credit trends, so I would not trade consumer finance names off this headline alone. The more plausible beneficiary is a prime card/franchise bank that can capture the same customer after credit repair, while fintech lenders remain dependent on broader macro easing rather than financial education alone.
The contrarian point is that markets often overestimate the investability of “financial wellness” initiatives. The real variable is not sentiment but whether participants change utilization, savings velocity, and charge-off behavior over 2-4 quarters; without hard data, this is marketing with a small behavioral nudge. Immediate price impact should be nil, and any sector read-through should be deferred until consumer credit prints confirm whether household balance-sheet repair is actually broadening.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No standalone trade in KRE/XLF on this headline; the signal is too small to justify risk before consumer credit data confirm any behavioral shift. Reassess only after the next 1-2 monthly delinquency prints.
- Conditional relative-value idea: long COF / short KRE over 3-6 months if card charge-offs and 30+ day delinquencies continue to ease. Rationale: card-centric lenders capture improved borrower health faster than deposit-heavy regionals; falsify if delinquency trends re-accelerate.
- For consumer-credit exposure, prefer SYF on a pullback only if upcoming earnings show lower net charge-offs and stable utilization. The upside is a modest multiple re-rate from improving credit quality; the risk is that this headline proves non-scalable and sector credit costs stay sticky.
More News
- Why a Starbucks takeover of Chipotle would — and wouldn't — make sense for both companies
- OpenAI Sees $70B Revenue; Airtel Money Seeks Biggest UK IPO Since 2021
- 'Last Night I Had Nightmares' Says Airtel Money CEO Before IPO
- SSP shares fall 4% as N. America weighs on profit, cash flow below expectation
- America’s Hybrid Hype Has Hit the Used Market
- Airtel Money Becomes London Stock Exchange’s Newest Big IPO
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- AI Software for Buy-Side Teams: Build the Research Stack