
Orogen Royalties Acquires the Serpent Gold Project in Nevada
Source: Newswire
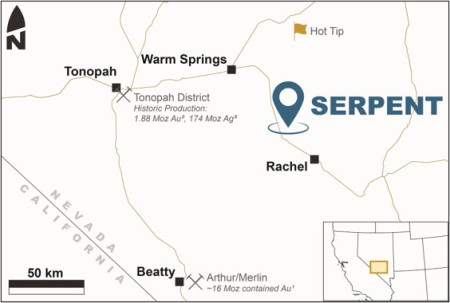
Orogen Royalties acquired the 18.8 sq. km Serpent gold project in central Nevada, an undrilled, district-scale low-sulphidation epithermal target spanning an 8-km alteration trend. Reconnaissance samples returned gold grades of up to 0.95 g/t at the Cobra corridor, 0.52 g/t in a perpendicular structure, and 0.4 g/t at Ant Hill; assays from additional northern structures remain pending. The early-stage asset is available for option or sale, supporting Orogen's project-generator and royalty-creation strategy, but no transaction price or drilling program was disclosed.
Analysis
This is an option-value addition rather than a near-term NAV event. Without drilling, metallurgy, or a funded earn-in agreement, Serpent should not alter Orogen's royalty valuation; the relevant re-rating mechanism is a third-party option that transfers exploration spend while preserving a retained NSR. The absence of systematic QA/QC in the initial sampling also means surface results cannot support a credible grade/tonnage inference, making any sharp post-release move in OGN/OGNNF primarily a liquidity-driven reaction.
The September 16 project event is a modest days-to-weeks catalyst only if management identifies a credible partner, work commitment, and royalty economics. Over the next 6-18 months, the asset becomes relevant only if a well-capitalized Nevada-focused explorer funds first-pass drilling and demonstrates subsurface continuity; a failed partner process or low-priority holding costs would instead reinforce the market's discount to the project-generator model. AG's operational cash flow and valuation are immaterially affected, while ALS benefits strategically from validation of its generative alliance but has no meaningful earnings sensitivity.
Consensus may overvalue the Nevada address and analogous-district language: project generators create asymmetric portfolios, but the probability-weighted payoff remains low before a partner commits capital. Conversely, the market may underappreciate the strategic value if Orogen can repeatedly monetize early-stage targets without issuing equity; the key evidence is not additional reconnaissance assays but the economics and counterparty quality of an option agreement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No directional position in AG or ALS on this development; require an announced earn-in with defined minimum exploration spend, cash/share consideration, and retained NSR before reassessing valuation impact.
- Place OGN/OGNNF on an event-driven watchlist through September 16: consider only a small long after confirmation of a third-party option or funded drill program, not on presentation-driven volume. Target a 6-12 month catalyst path; exit if no partner/work commitment is secured within two quarters.
- For any OGN position, size as venture-exploration optionality and use liquidity discipline: thesis is falsified by a dilutive financing absent a partner-funded program, an option agreement with immaterial minimum spend, or first drilling that fails to show meaningful subsurface mineralization continuity.
- Monitor Nevada-focused junior explorers and royalty buyers for the likely counterparty rather than treating this as an AG read-through; a credible partner can create a valuation catalyst for OGN, whereas self-funded exploration would increase cash-burn and financing risk.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit