
Baker Donelson Elects Kristine L. Roberts as Next President and COO
Source: PR Newswire
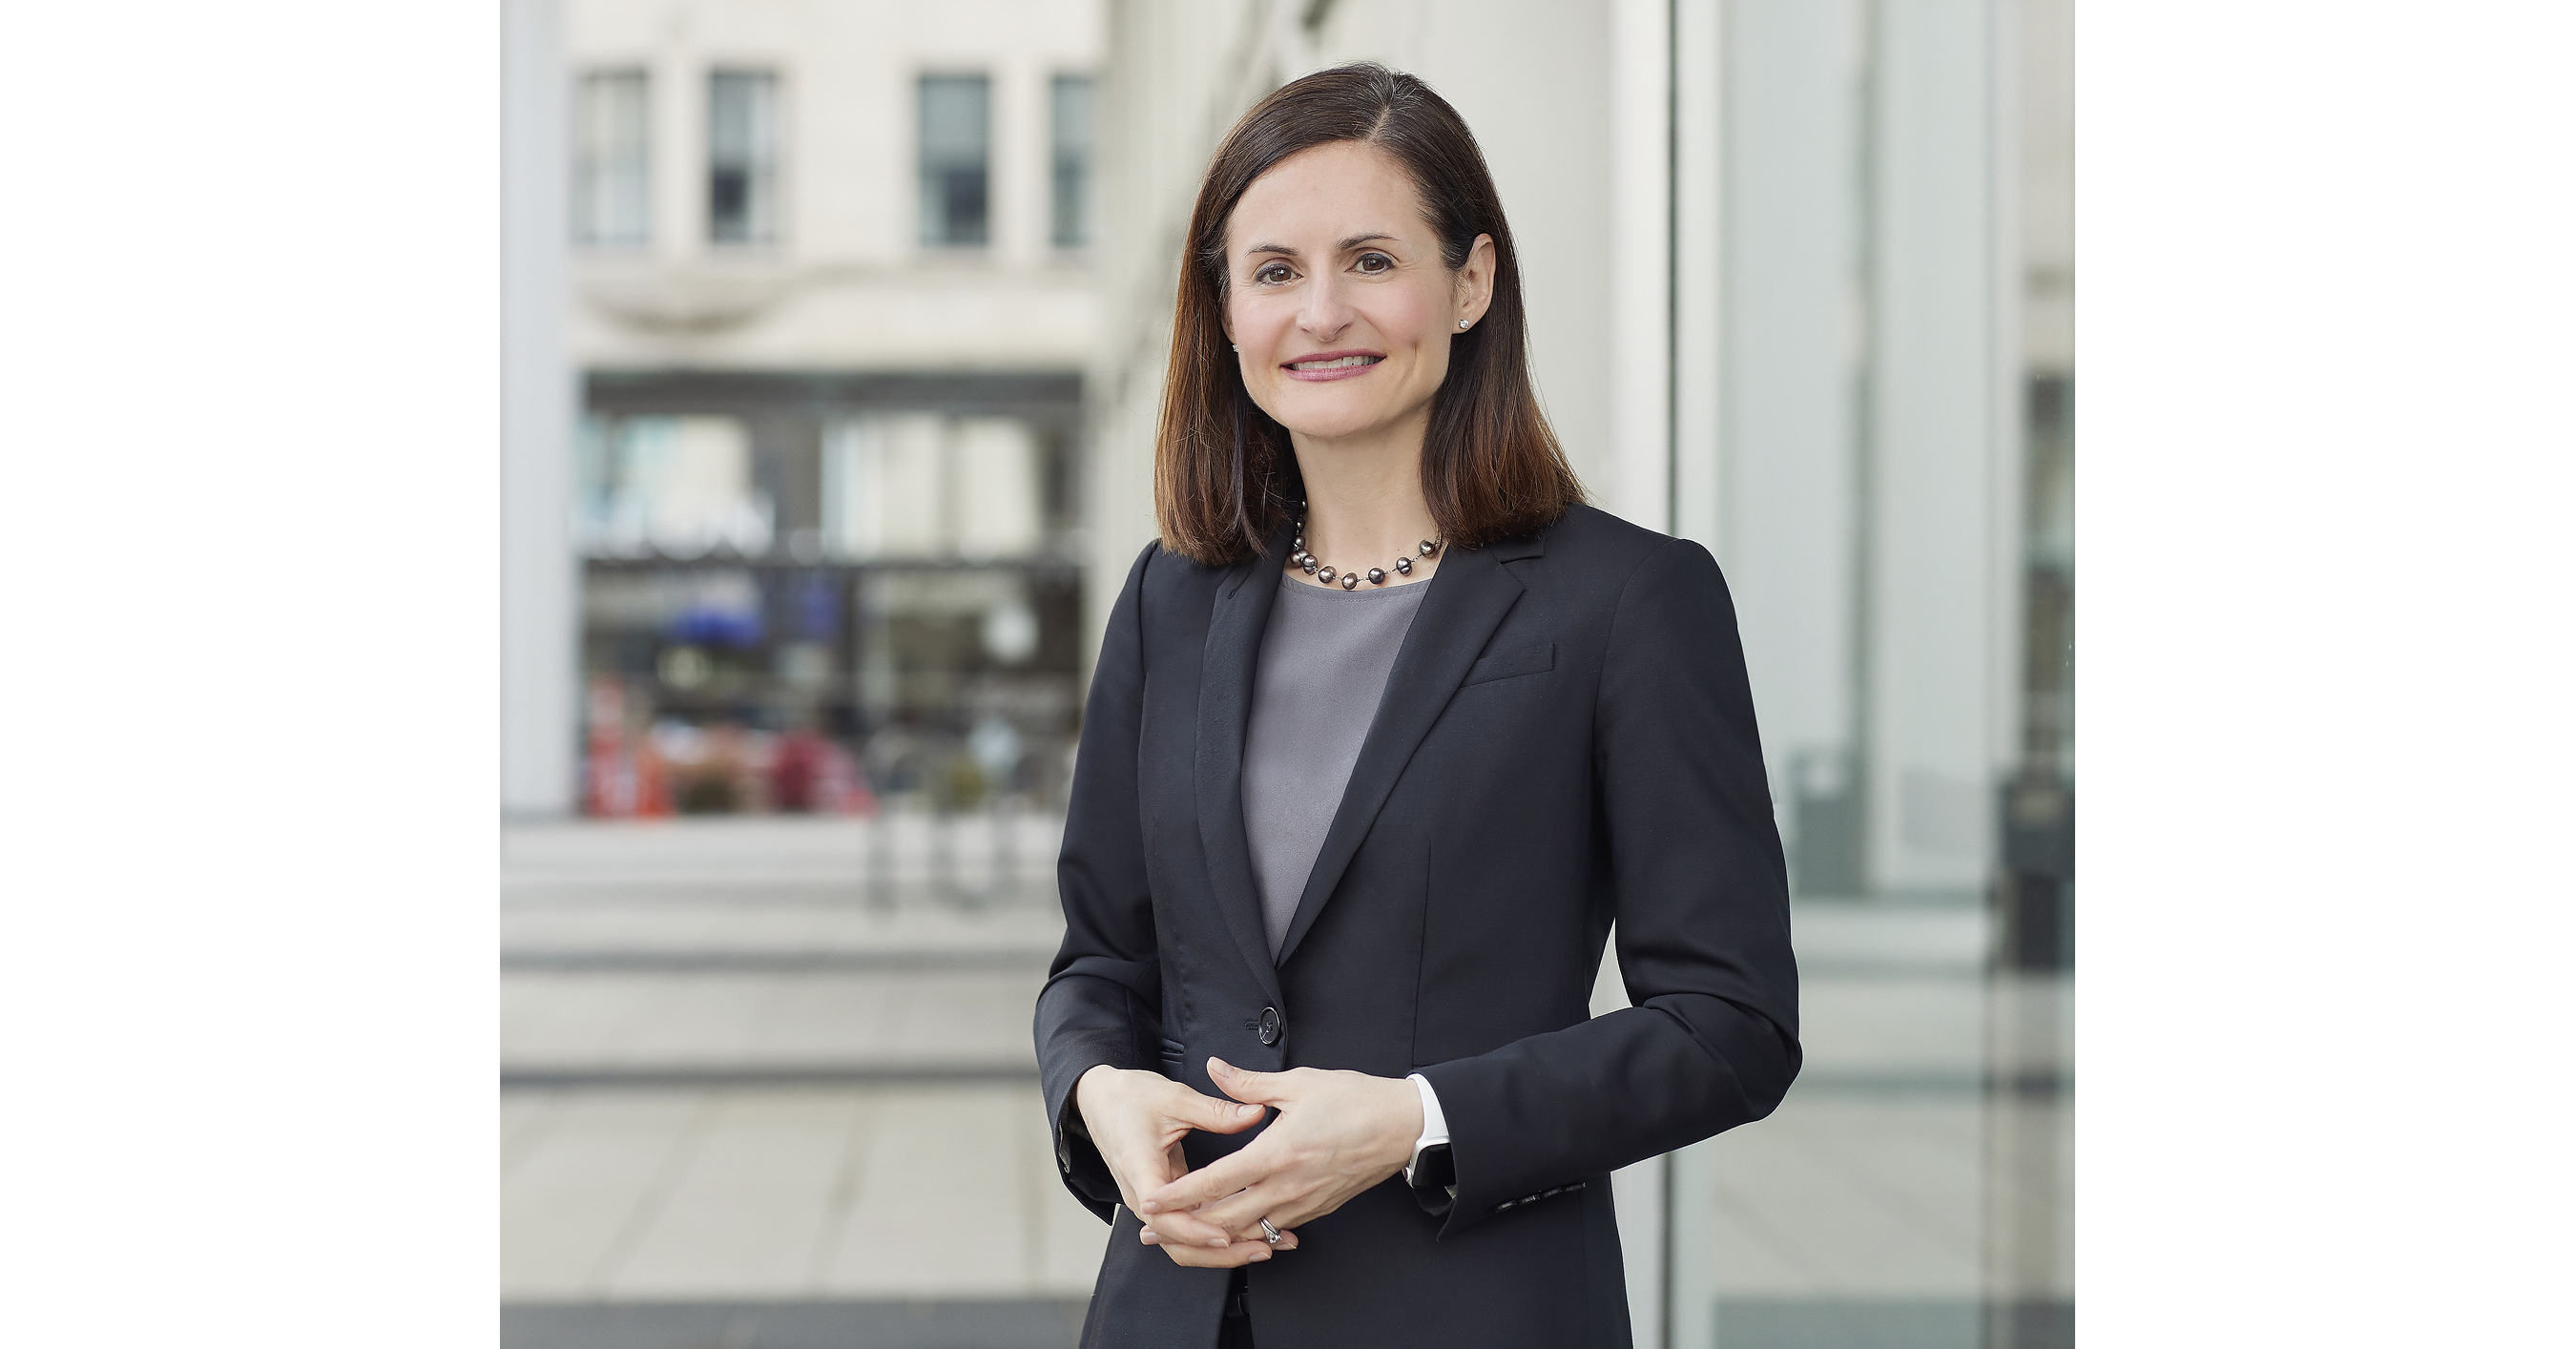
Baker Donelson elected Kristine S. Roberts as its next president and COO, with her appointment effective May 2027. Jennifer P. Keller, who has held the roles since 2015, will step down then and remain with the firm; the announcement gives no financial figures or expected business impact.
Analysis
This is a low-information governance transition at a privately held law firm, with no direct public-equity exposure identified. The long handoff period and continued involvement of the outgoing leader reduce near-term execution risk; the more meaningful variable is whether leadership change alters attorney retention, lateral hiring, or client origination over the next 6–18 months. Roberts’s financial-services litigation background could reinforce Baker Donelson’s positioning with banks and other financial institutions, but the announcement provides no evidence of a change in strategy, revenue, or client demand. Any competitive impact on other firms is therefore speculative. The contrarian point is that a named succession can look like a growth signal while conveying little about economics: awards and internal endorsements do not establish improved profitability or share gains. No listed-company catalyst or defensible valuation signal is apparent.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No trade based on this announcement alone; Baker Donelson is not a publicly traded security in the supplied company mapping, and no direct listed-company read-through is established.
- Treat as a monitoring item through the May 2027 transition: look for independently verifiable changes in partner departures, lateral hiring, client retention, or practice-group leadership before inferring competitive gains or losses.
- Reassess only if the succession is accompanied by measurable strategic changes or client/talent disruption; absent those signals, the likely market impact remains negligible.
More News
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- ‘I drive a Tesla’: After Elon Musk said he’d lose his job, Delta CEO Ed Bastian says there’s ‘no tit for tat’ as airline unveils earnings miss
- Why is the Chinese stock market missing the AI rally
- Tesla drops 'Full Self-Driving' brand name in Europe after regulator pushback
- Why is T-Mobile stock tumbling today?
- SpaceX makes big move into wireless. These once 'obsolete' tech stocks could benefit