
Segway rassemble ses partenaires internationaux de la micromobilité partagée pour ouvrir un nouveau chapitre dans l'histoire du secteur
Source: PR Newswire
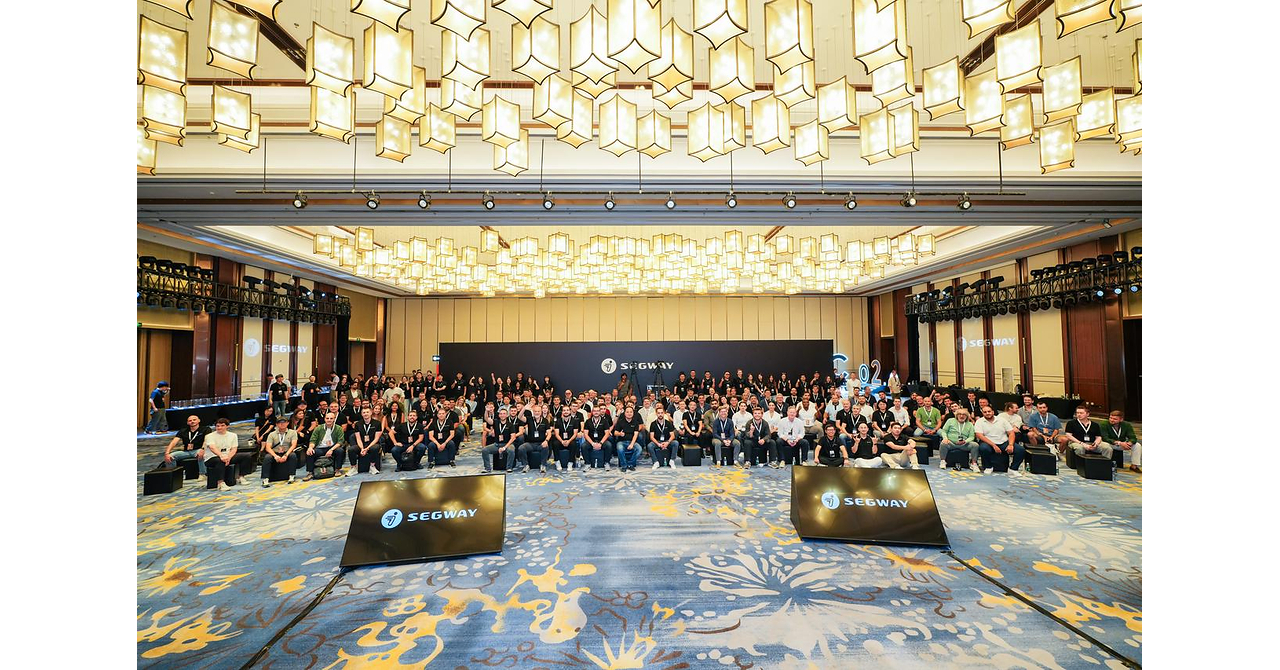
Segway unveiled its third-generation shared e-scooter, the R1, alongside the C100 and C200 shared e-bike series and F100 delivery e-bike. The company is targeting improved shared-micromobility fleet economics through a total-cost-of-ownership framework emphasizing vehicle uptime, maintenance, energy use and longer asset life. The launches add modular hardware, integrated IoT and enhanced positioning and rider-assistance features, but the announcement provides no financial guidance or sales figures.
Analysis
This is directionally positive for the economics of mature shared-mobility operators, but it is not yet an investable revenue catalyst for public equities. A shift from fleet expansion toward utilization, maintenance and vehicle-life optimization favors scaled operators with dense city footprints, proprietary rebalancing data and municipal permits; it raises the cost of competing for subscale fleets that have historically relied on cheap hardware. The second-order effect is likely lower replacement demand per ride, partially offset by a larger share of recurring software, telematics, servicing and parts revenue for suppliers able to lock in fleet standards.
For public proxies, Uber (UBER) and Lyft (LYFT) have indirect upside through better unit economics and retention in bikes/scooters where they operate or partner, but the contribution is immaterial relative to ride-hail. The cleaner structural beneficiary is Ninebot, Segway's listed parent (SSE:689009), if its product cycle converts hardware sales into higher-margin lifecycle services; however, the release provides no pricing, order backlog, warranty-cost or operator-adoption data to underwrite that thesis. Over 6-18 months, more durable fleet hardware could also improve delivery-bike economics for DoorDash (DASH) and Uber, though it may reduce addressable replacement-unit volumes for commodity component suppliers.
Consensus may overread the product refresh as evidence of a shared-mobility demand recovery. City caps, permit renewals, vandalism/theft, insurance costs and local restrictions—not vehicle specifications—remain the binding constraints on fleet profitability. The key falsifier of a TCO-led recovery is not product launch volume but evidence that operators can sustain higher ride frequency and lower maintenance expense without using subsidies or expanding capex; absent that, this remains supplier marketing rather than a sector inflection.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone trade on the announcement. Treat SSE:689009 as a watchlist candidate until the next earnings release discloses commercial-mobility revenue growth, service/parts mix, gross-margin progression and independently identifiable R1/C-series orders.
- Monitor UBER and LYFT over the next 1-3 months for disclosures on shared-mobility gross bookings, partner economics or municipal permit expansion; do not extrapolate a hardware refresh into consolidated EBITDA upside without segment-level evidence.
- For a 6-18 month thematic expression only after verified operator adoption, prefer long SSE:689009 versus a broad China consumer-discretionary proxy: lifecycle-service attachment could support margin expansion, while the principal risk is price competition and lower fleet replacement volumes. Exit if commercial-mobility margin fails to improve over two reporting periods.
- Set an alert on major municipal permit decisions and operator consolidation. A regulatory tightening or a large operator failure would impair fleet purchasing and service demand quickly, outweighing any efficiency benefit from improved hardware.
More News
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Houthi attack on Mecca, Medina would cross ‘red line’, Pakistan PM tells UN
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying
- Anthropic Goes Big on Compute, Microsoft Rethinks AI
- Wall Street Week | China’s Trade Reckoning, Syracuse’s Second Chance, Humanoids in Healthcare
- Iran says it's up to U.S. to end war as China presses for de-escalation
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit
- AI Research Systems for Hedge Funds: A Pilot Design